
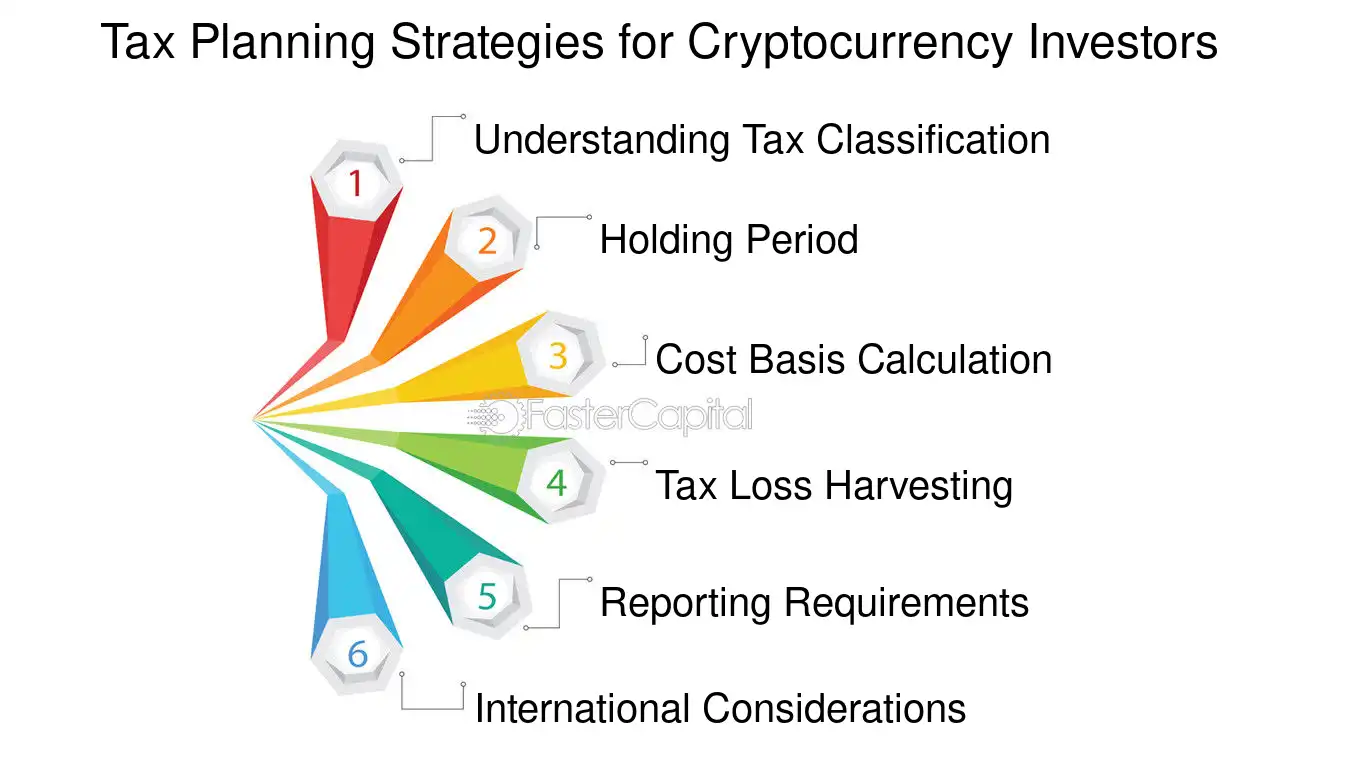
In the rapidly evolving world of cryptocurrency, understanding the tax implications of your investments is more important than ever. As digital assets gain popularity, so too do the regulations, and staying informed can save you from costly errors when tax season arrives. In this article, we will explore everything investors need to know about cryptocurrency taxes, ensuring you feel confident navigating the complex landscape of crypto taxation.
Understanding Cryptocurrencies and Taxation
Cryptocurrencies, digital currencies that utilize blockchain technology for secure transactions, have grown to represent a significant portion of global investment portfolios. Bitcoin, Ethereum, and Litecoin are just a few prominent examples. However, with great investment opportunities come various responsibilities, including tax obligations.
The Internal Revenue Service (IRS) treats cryptocurrencies as property, rather than currency. This classification implies that traditional capital gains tax rules apply. Therefore, if you have bought, sold, or traded cryptocurrencies, it’s crucial to understand the tax ramifications of your actions.
Capital Gains Tax Explained
Capital gains tax applies to the profit you make when you sell or exchange a capital asset like stocks, real estate, or—yes—cryptocurrencies. When you sell your crypto for more than you paid, you incur a capital gain. Conversely, if you sold it for less than you paid, you realize a capital loss.
The IRS distinguishes between two types of capital gains:
-
Short-term Capital Gains: These apply if you hold your asset for one year or less. Short-term capital gains are taxed at your ordinary income tax rate, which can be as high as 37% depending on your total income level.
-
Long-term Capital Gains: If you hold the asset for more than one year, your gains qualify for long-term capital gains tax rates, which range from 0% to 20%, based on your taxable income. This preferential treatment encourages long-term investing.
Reporting Your Cryptocurrency Transactions
Properly reporting your cryptocurrency transactions is crucial to ensure compliance with IRS regulations. Here’s how to do it step-by-step:
-
Record Your Transactions: Keep a detailed record of every transaction, including the date, amount, type of cryptocurrency, transaction value in USD at the time of sale, and the purpose of the transaction.
-
Calculate Gains and Losses: Determine whether your transactions resulted in profits or losses. Use the formula: (Selling Price – Purchase Price) = Capital Gain or Loss.
-
Complete Form 8949: This IRS form is used to report capital gains and losses from the sale or exchange of assets, including cryptocurrencies. You’ll need to fill out the form with your gain/loss calculations.
-
Transfer Data to Schedule D: Once you’ve completed Form 8949, summarize your totals onto Schedule D, which is part of your primary tax return.
-
File Your Taxes: Include your crypto transactions along with your standard income on your tax return by the April deadline, ensuring that all income is reported, including income received in the form of cryptocurrencies.
Handling Different Types of Crypto Transactions
Different types of crypto transactions can lead to varying tax liabilities. Here are some key scenarios that investors may encounter:
-
Selling Cryptocurrency for Cash: This is the most straightforward scenario. If you sell your cryptocurrency for cash, you will realize either a capital gain or loss based on the difference between the sale price and your purchase price.
-
Trading One Cryptocurrency for Another: When you trade one cryptocurrency for another, the IRS treats this swap as a taxable event. You need to calculate any gain or loss on the cryptocurrency you’re giving up, even if you haven’t received cash.
-
Receiving Cryptocurrency as Payment: If you receive cryptocurrency as payment for goods or services, the value of the cryptocurrency at the time you received it is treated as ordinary income. You’ll owe income tax on that amount.
-
Mining Cryptocurrency: Income generated from mining cryptocurrencies is also considered taxable income. You’ll need to report the fair market value of the cryptocurrency at the time it was mined.
-
Staking or Earning Crypto Interest: If you earn cryptocurrency through staking or interest from lending platforms, this too is taxable as ordinary income. Keep in mind that some platforms may issue a Form 1099 for earned income, making reporting easier.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
Tax-Loss Harvesting Strategies
Tax-loss harvesting can help offset your capital gains and lower your overall tax liability. It involves selling a losing investment to realize a loss, which can then be used to offset gains elsewhere. Here’s how to effectively implement tax-loss harvesting in your cryptocurrency portfolio:
-
Identify Losing Investments: Analyze your crypto portfolio and determine which assets currently have losses.
-
Sell the Investments: To realize the loss and take advantage of this strategy, you must sell the losing investments. Be cautious about IRS’s “wash sale rule,” which applies to stocks but currently does not apply to cryptocurrencies.
-
Reinvest Strategically: After selling a losing investment, consider reinvesting in a different asset or waiting 31 days to repurchase the same cryptocurrency to avoid potential issues if the wash rule changes.
-
Use Losses to Offset Gains: Apply your realized losses against any capital gains to reduce your taxable income.
Common Cryptocurrency Tax Mistakes to Avoid
Navigating cryptocurrency taxes can be tricky, and many investors make mistakes that could lead to penalties or increased tax liabilities. Here are some common errors to be aware of:
-
Failing to Report All Transactions: Even minor transactions, such as trading small amounts or purchasing goods with cryptocurrency, should be reported.
-
Not Keeping Track of Basis: Failing to accurately track your purchase price for cryptocurrencies can result in incorrect gain/loss calculations.
-
Mixing Personal and Business Activity: If you use cryptocurrency for both personal and business purposes, maintain separate records to avoid confusion and possible audits.
-
Ignoring State Taxes: Cryptocurrency transactions might also be subject to state taxes, which vary by jurisdiction. Be sure to check local regulations.
-
Not Seeking Professional Help: Tax regulations can be complicated, especially as they relate to cryptocurrencies. If you’re unsure, consult a tax professional experienced in crypto-related tax laws.
Upcoming Changes and Trends in Cryptocurrency Taxation
Staying informed about changes in cryptocurrency regulations is vital for investors. The landscape of cryptocurrencies and taxes is dynamic, and a few noteworthy trends are emerging:
-
Increased Regulatory Scrutiny: Government agencies, including the IRS, have ramped up efforts to ensure compliance, especially regarding unreported crypto income. Expect more audits and investigations in the coming years.
-
More Comprehensive Reporting Requirements: There have been discussions about more detailed reporting requirements for cryptocurrency transactions. Platforms might soon be required to report to the IRS transactions exceeding certain thresholds.
-
Inclusion of NFTs and DeFi: As non-fungible tokens (NFTs) and decentralized finance (DeFi) projects gain traction, their tax implications are being scrutinized. Investing in these areas will likely require additional understanding of their tax environment.
-
Increased International Cooperation: Tax authorities globally are increasingly working together to standardize reporting and compliance measures for cryptocurrency transactions.
Conclusion
Understanding cryptocurrency taxes is crucial for anyone involved in crypto investments. While the landscape may appear complex, with diligent record-keeping and an awareness of regulations, you can ensure compliance and potentially minimize tax liabilities. Whether you are trading, mining, or utilizing crypto for business purposes, taking the necessary steps now can help simplify your tax process down the road.
As tax regulations continue to evolve, it’s critical to stay informed and potentially consult with experts. By being proactive about your cryptocurrency tax obligations, you can focus more on the exciting potential of your investments, rather than worrying about tax consequences. Now that you know what to expect, embrace your journey into the world of cryptocurrency with confidence!


