
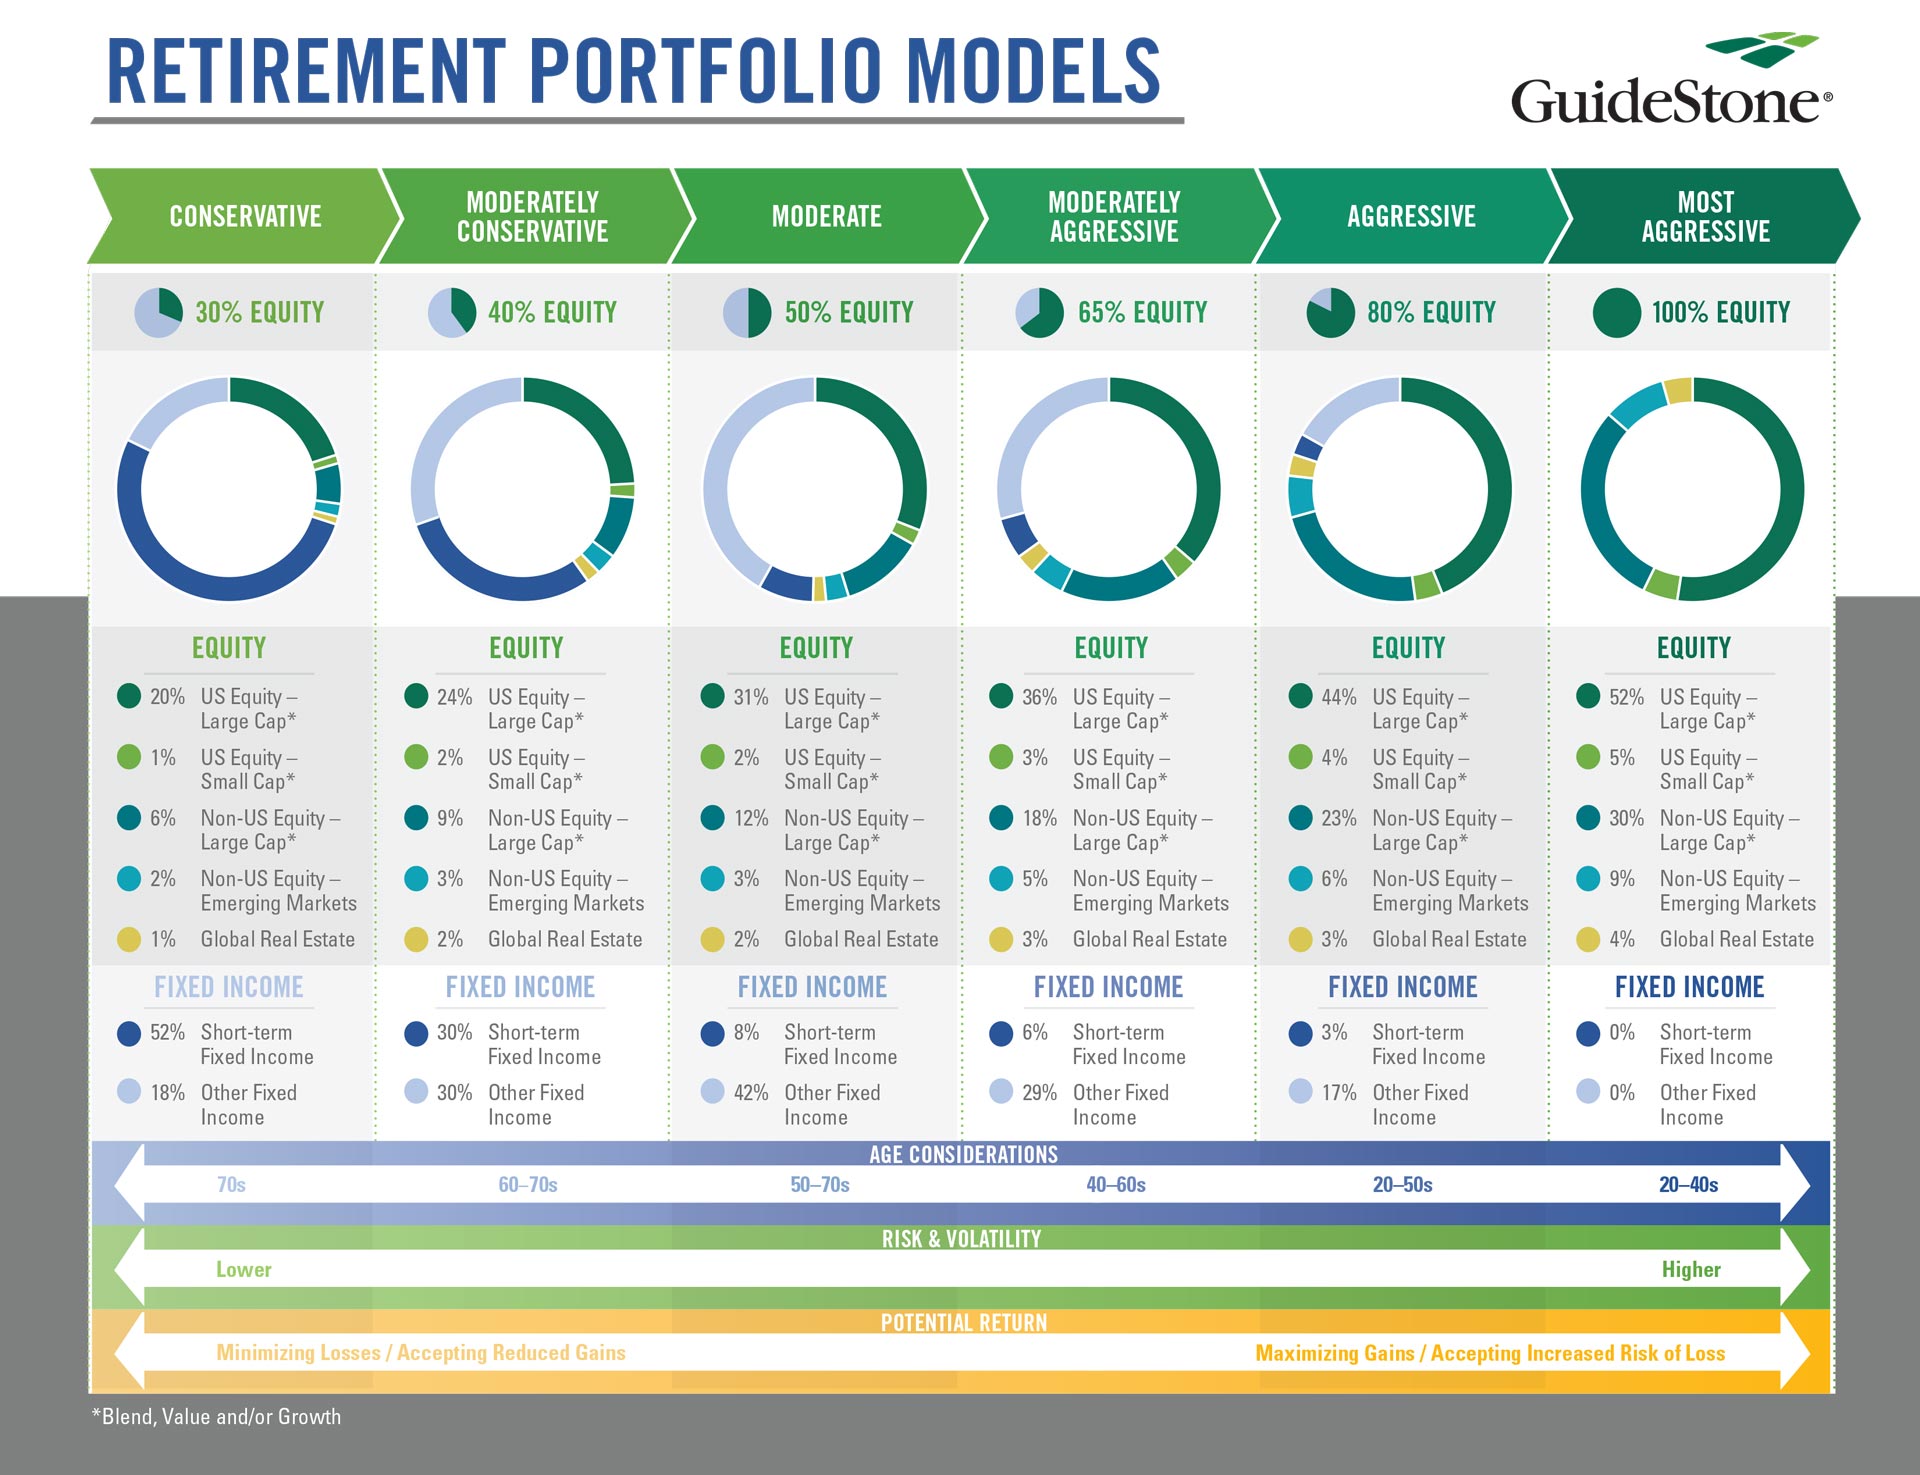
When it comes to retirement planning, an investment portfolio tailored to your financial goals is crucial. After all, the last thing you want is to stress about money during your golden years. That’s why we’ve crafted this comprehensive guide on how to plan your investment portfolio for a comfortable retirement. Whether you’re just starting or a seasoned investor, this article offers insights to help you secure your financial future and enjoy your retirement to the fullest.
Understanding the Importance of Retirement Planning
Before diving into portfolio specifics, understanding why retirement planning is vital is essential. According to various studies, many Americans underestimate the amount needed to retire comfortably. The general rule of thumb is that you should aim to replace about 70% to 80% of your pre-retirement income. This can translate into a multi-million dollar nest egg, depending on your lifestyle choices. So, how do you arrive at that number, and perhaps more importantly, how do you build a portfolio that aligns with that target?
Start with the Basics: Assessing Current Financial Status
The first step toward planning your investment portfolio is assessing your current financial situation. This means evaluating your assets, liabilities, income, and expenses. A financial planner can offer insights, but here are the steps you can take on your own:
-
List All Assets: Include savings accounts, retirement accounts (like 401(k)s and IRAs), stocks, bonds, real estate, and any other investments.
-
Evaluate Liabilities: Outline your debts, including mortgages, student loans, and credit card debts.
-
Determine Income and Expenses: Analyze your monthly income and recurring expenses. Understanding your cash flow is key to establishing how much you can invest.
Setting Retirement Goals
Once you have a solid grasp of where you currently stand financially, it’s time to set clear retirement goals:
-
Determine Your Retirement Age: When do you plan to retire? Consider how much time you have until then and how that timeframe affects your investment strategy.
-
Decide on a Lifestyle: What kind of lifestyle do you envision for yourself in retirement? This includes travel, hobbies, and living arrangements.
-
Estimate Retirement Expenses: Calculate the total expenses you expect during retirement, taking into account healthcare costs, travel plans, and other lifestyle choices.
Calculating Your Retirement Needs
After setting your goals, it’s crucial to calculate how much you will need to save to reach those objectives. Tools like retirement calculators can provide invaluable insights based on variables like:
- Expected retirement age
- Monthly contributions
- Rate of return on investments
- Current savings
It’s always recommended to err on the side of caution, so consider adding at least 20% to your estimated retirement needs to account for unforeseen expenses or economic downturns.
Choosing the Right Investment Strategy
With a clearer picture of your retirement goals and financial standing, it’s time to develop an investment strategy that aligns with your needs. Here are some investment options to consider:
1. Stocks
Investing in individual stocks can offer significant growth potential. Historically, stocks have outpaced inflation and provided higher returns than other asset classes. However, they also come with higher volatility, making it essential to understand your risk tolerance.
2. Bonds
Bonds are generally considered safer than stocks but also have lower expected returns. They can provide a steady income stream and help balance your portfolio’s risk. Consider bond funds or ETFs to diversify your bond investments.
3. Mutual Funds and ETFs
These are pooled investments that allow you to invest in a diversified portfolio without purchasing each asset individually. They come in various types, from aggressive growth funds to conservative income funds.
4. Real Estate
Investing in real estate can be an excellent way to generate passive income. Whether through buying rental properties or investing in Real Estate Investment Trusts (REITs), this asset class can offer cash flow along with potential price appreciation.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
5. Retirement Accounts
Utilizing tax-advantaged accounts like 401(k)s and IRAs can maximize your savings. Many employers offer matching contributions for 401(k)s, which is essentially free money. Research the providers that suit you best, whether that’s robo-advisors, traditional brokers, or while utilizing a combination of several methods.
Diversification: Your Best Friend
One of the central principles of investing is diversification – don’t put all your eggs in one basket. A diversified portfolio spreads the risk and can improve your chances of achieving your long-term financial goals. Here’s how to make that happen:
-
Mix Asset Classes: Include a balance between stocks, bonds, real estate, and cash. Depending on your age and risk tolerance, you may want a higher percentage of stocks when you’re younger and gradually shift towards bonds as you approach retirement.
-
Sector and Geographical Diversification: Don’t limit yourself to one sector or geographical area. The global economy is interconnected, and various sectors perform differently at different times.
-
Rebalancing: Periodically review and rebalance your portfolio to maintain your desired asset allocation. This might mean selling some assets and buying others to keep your strategy aligned with your risk tolerance and retirement goals.
Assessing Risk Tolerance
Understanding and assessing your risk tolerance is crucial when planning your investment portfolio. Age, financial situation, and personal comfort with market fluctuations all play significant roles.
-
Risk Assessment Questionnaires: Taking a risk assessment questionnaire can help you gauge your risk tolerance level. Financial advisors often provide these tools to give you insight into the best investment strategy for you.
-
Reevaluate Regularly: Risk tolerance can change with life events, economic conditions, and changes in your health. Regularly reassess your portfolio to ensure it still meets your risk level.
Creating an Action Plan
Now that you’ve gathered all the necessary information and have a solid investment strategy, it’s time to create an actionable plan:
-
Set Up Automatic Contributions: Automate your investment transfers to your retirement accounts to ensure consistent saving.
-
Determine Withdrawal Strategy: Consider how and when you will start withdrawing funds once you retire. Options include the 4% rule or more tailored strategies depending on your portfolio composition and market conditions.
-
Consult with Professionals: If you’re unsure, consult a financial advisor. A professional can provide tailored advice based on your individual circumstances and help you navigate the intricacies of retirement planning.
Staying Informed and Adjusting Your Plan
Staying informed is crucial for long-term investment success. Financial markets fluctuate, new financial products emerge, and personal circumstances can change drastically over time. Here are some tips to keep you in the driver’s seat:
-
Keep Learning: Whether through books, podcasts, or online courses, never stop educating yourself about investing and personal finance.
-
Adjust Accordingly: As you get closer to retirement, it may be wise to adjust your portfolio to include more conservative investments.
-
Review Annually: Make it a habit to review your financial plan and investment portfolio at least once a year or sooner if significant life changes occur.
In Conclusion
Planning your investment portfolio for a comfortable retirement is essential for achieving your financial goals. By assessing your current financial situation, setting clear goals, diversifying your investments, and staying informed, you will put yourself on the right path. It may seem daunting at first, but remember that every small step counts, and the earlier you start planning, the better off you will be.
A comfortable retirement doesn’t happen overnight. With dedication, research, and a clear strategy, you can enjoy the freedom and peace of mind that comes with knowing your financial future is secure. So, what are you waiting for? Start planning today for the retirement you deserve.


