
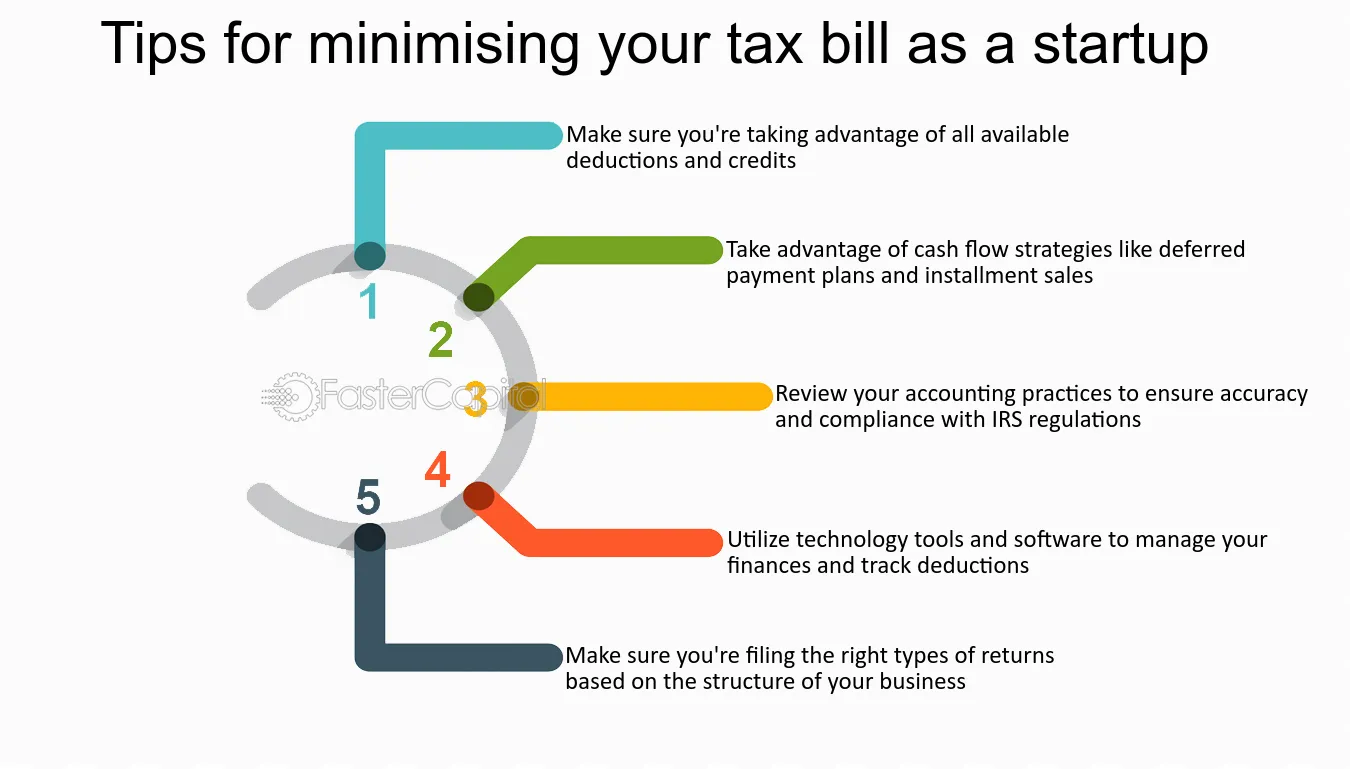
Starting a business can be an exhilarating journey filled with passion, innovation, and the promise of success. However, alongside this excitement comes the daunting reality of navigating the complexities of taxes. For startups, understanding tax deductions is not just an obligation; it’s a crucial aspect of financial health that can make or break your business. In this article, we’ll dive deep into the essential tax deductions every startup should know about to ensure you’re making the most of your investments and minimizing your liabilities.
Why Tax Deductions Matter for Startups
Before delving into the specifics of tax deductions, let’s first clarify why they are significant for startups. Tax deductions reduce the amount of income that is subject to taxation, thus lowering your overall tax bill. For a startup, every dollar counts, and maximizing deductions can free up resources for growth, such as hiring new employees, investing in research and development, or marketing initiatives.
Understanding which expenses are deductible is crucial, as it can lead to significant savings. Additionally, being aware of tax deductions helps startups comply with IRS regulations, thereby avoiding penalties or audits down the road.
Common Tax Deductions Every Startup Should Consider
- Startup Costs
If you are in the early stages of your business, you may incur various costs that can be deductible. The IRS allows startups to deduct up to $5,000 in startup expenses in the first year of business. These expenses may include costs related to market research, advertising, and fees for professional services. However, startup costs exceeding $50,000 must be amortized over 15 years.
- Business Operating Expenses
Ongoing costs that contribute to the daily operations of your business can typically be deducted. This section includes:
– Office Supplies: Pens, paper, and other office essentials.
– Utilities: Electric, gas, water, and phone bills necessary for your business.
– Rent: Regular payments for the office or retail space.
– Salaries and Wages: Employee compensation is one of the most significant business expenses and is fully deductible.
- Professional Services
With a startup, you may find it beneficial to engage in professional services. Expenses associated with hiring accountants, attorneys, or consultants can usually be deducted. This deduction is essential for startups that require expert guidance to navigate legal, financial, and operational aspects.
- Research and Development (R&D)
If your startup is engaged in developing new products or services, your R&D expenses may qualify for significant tax credits and deductions. The IRS Section 41 allows for a tax credit on expenditures related to qualified research—this includes wages for employees engaged in R&D, costs for supplies, and some contract research expenditures. Remember that detailed documentation is essential to support these claims.
- Marketing and Advertising Costs
For a startup, getting the word out is vital, and thankfully, marketing costs are generally deductible. This category can include:
– Website Development: Creating a business website can include various costs, all of which may be deducted.
– Social Media Advertising: Ads and promotions on platforms like Facebook, Instagram, and Google.
– Print Advertising: Flyers, brochures, posters, and other promotional materials.
- Travel Expenses
Travel can be a significant part of doing business, whether it’s meeting clients, attending industry conferences, or exploring new markets. The IRS allows deductions for necessary business travel expenses. This can cover:
– Transportation: Costs associated with flights, car rentals, and taxis.
– Lodging: Hotel accommodations for business-related trips.
– Meals: A portion of meal costs related to business functions, typically up to 50%.
- Vehicle Expenses
If you use a vehicle for business purposes, the IRS allows you to deduct either the actual car expenses or the standard mileage rate (which is periodically adjusted). Keep detailed records, including mileage logs, and receipts for any vehicle-related expenses.
- Home Office Deduction
If you are running your startup from home, you may be eligible for the home office deduction. This deduction applies to the portion of your home used exclusively for your business. You can deduct a percentage of your rent or mortgage, utilities, and other associated costs. Note that it’s essential to meet specific criteria to qualify for this deduction.
- Insurance Premiums
Insurance is a necessary expense for many startups. Premiums for general liability insurance, professional liability insurance, and workers’ compensation insurance can typically be deducted from your taxable income. Ensuring your business is properly insured not only safeguards your operations but also offers a tax advantage.
- Education and Training
Investing in yourself and your team can be a significant step towards success. Costs associated with education, training, seminars, and conferences that enhance skills for business growth may be deductible. This is a powerful way to foster professional development while reaping tax benefits.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
State-Specific Deductions
While we have covered federal tax deductions, it’s crucial also to consider state-specific tax deductions, as they can vary significantly. Many states have their tax codes, which may provide additional deductions or credits for small businesses. It’s essential to familiarize yourself with local regulations and consult with a tax professional to ensure compliance and maximize your savings.
Important Considerations
-
Documentation is Key: Maintain meticulous records of all business-related expenses. Having receipts, invoices, and financial statements will support your deductions during tax time and protect you in case of an audit.
-
Consult a Tax Professional: Tax laws can be intricate and subject to change. Working with a CPA or tax advisor can help you identify deductions you may overlook and ensure that you’re filing accurately.
-
Be Aware of Changes: Tax codes evolve. Keep an eye on updates from the IRS or consult with a professional to stay informed about changes that could affect your deductions.
Final Thoughts
Navigating the world of tax deductions can seem overwhelming, especially for new entrepreneurs who are often focused on building and growing their startups. However, understanding the available deductions can lead to substantial savings that can be reinvested back into your business, laying a stronger foundation for future success.
Remember, every deduction you can claim not only reduces your taxable income but also represents a strategic approach to managing your startup’s finances. As you embark on your entrepreneurial journey, make it a point to equip yourself with the knowledge and resources necessary to navigate these financial waters confidently.
Your startup’s tax obligations do not have to be a looming cloud of stress; instead, they can be a pathway to sustainability, growth, and ultimately, success. With careful planning, diligent record-keeping, and informed decision-making, you can position your startup to thrive—financially and beyond.
In conclusion, arm yourself with knowledge and take advantage of the many tax deductions available to you. This understanding is crucial not just for managing your current costs but for planning a future that is as bright and innovative as the vision you had when you started your business. Here’s to your entrepreneurial journey and taking charge of your financial destiny!


