
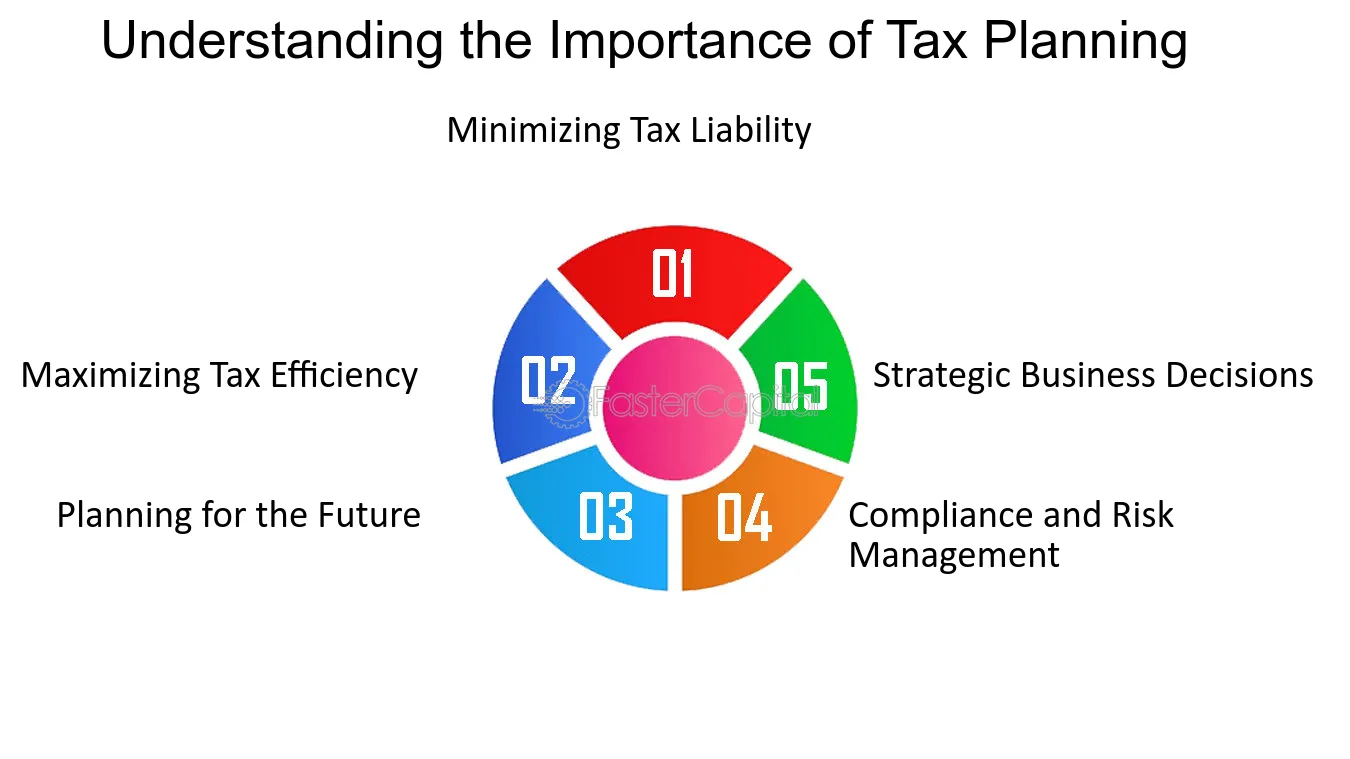
Starting a new business is an exciting venture, filled with dreams, ambitions, and countless responsibilities. As a startup founder, you might be focused on perfecting your product, attracting customers, and building your brand. However, one critical aspect you shouldn’t overlook in your inaugural year is tax planning. The importance of tax planning for startups in their first year cannot be overstated; it can mean the difference between financial success and costly pitfalls.
Why Tax Planning is Essential for Startups
In the U.S., navigating the tax landscape can be particularly challenging for new entrepreneurs. With so many rules, regulations, and potential deductions available, understanding the intricacies of tax planning can feel overwhelming. However, being proactive about your tax strategy offers numerous benefits, including saving money, maximizing deductions, and ensuring compliance with tax laws.
1. Minimizing Tax Liability
One key benefit of tax planning is the potential for minimizing your overall tax liability. Many startups are unaware of the deductions and credits they might qualify for. For example, business expenses such as equipment purchases, startup costs, and employee salaries may be deductible, reducing your taxable income. A good tax plan helps you identify these opportunities early on, allowing you to take advantage of savings before the fiscal year ends.
2. Cash Flow Management
Effective tax planning ensures that you have sufficient cash flow to meet your operational needs. Unanticipated tax expenses can disrupt your budget, especially for startups that often operate on tight margins. By estimating your tax obligations early, you can set aside the necessary funds to cover them, avoiding any cash flow problems that could hinder your business operations or lead to unnecessary stress.
3. Identifying Tax Structure Benefits
Choosing the right business structure—whether an LLC, S-Corp, C-Corp, or sole proprietorship—has significant implications for your tax liability. Each structure is taxed differently, which can affect your financial health. With a solid tax plan, you can better understand the advantages and disadvantages of various structures, enabling you to choose the one that will benefit you the most. Consulting with a tax professional will help you navigate this complex decision.
4. Avoiding Costly Mistakes
Tax regulations are intricate and subject to change, making it easy for new business owners to inadvertently make costly mistakes. A fundamental aspect of tax planning is ensuring compliance with federal, state, and local tax laws. Failing to comply can lead to penalties, back taxes, and even audits. With a well-thought-out tax plan, you can navigate the complexities of tax regulations and avoid pitfalls that could derail your startup’s future.
5. Strategic Planning for Growth
Tax planning is not just about the present; it also sets the stage for future growth. By understanding the tax implications of certain business decisions, you can make informed choices that foster growth while minimizing tax burdens. For instance, deciding whether to reinvest profits or distribute them as dividends can have significant tax implications. Having a comprehensive tax strategy in place allows you to align your growth goals with your financial planning to drive success without incurring unnecessary tax liabilities.
Key Tax Considerations for Startups in Their First Year
As you embark on your entrepreneurial journey, there are several key tax considerations to keep in mind. By paying attention to these factors, you’ll be well on your way to developing an effective tax strategy.
1. Understand Your Eligible Deductions
Startup expenses can quickly accumulate, but many of those expenses are deductible. Common deductible startup costs include:
- Market Research Costs: Expenses associated with researching your target market.
- Legal Fees: Costs related to setting up your business structure, drafting contracts, and protecting intellectual property.
- Office Supplies: Any supplies, equipment, or inventory necessary to launch your business.
- Advertising and Promotion: Costs incurred in promoting your startup.
- Travel Expenses: Business-related travel expenses can also be deducted, which can include transportation, lodging, and meals.
If your startup incurred expenses before officially launching, you may still be eligible to deduct those costs within your first year.
2. Keep Detailed Records
Maintaining detailed records of all business transactions is crucial for effective tax planning. Good accounting practices help you track expenses, revenue, and deductions, simplifying tax preparation at the end of the year. Invest in accounting software or hire an accountant to keep your financial records organized and accessible, making tax season less daunting.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
3. Pay Estimated Taxes
In many cases, you’re required to pay estimated taxes throughout the year, especially if you expect to owe more than $1,000 in taxes for the year. Planning for these quarterly payments is essential, as failing to do so can lead to penalties. Keep tabs on your income and expenses to make accurate estimated payments and avoid surprises come tax time.
4. Employee vs. Independent Contractor Designation
Understanding the distinction between employees and independent contractors is vital for tax purposes. Misclassifying workers can lead to serious tax implications, including penalties. If you hire independent contractors, be sure to issue 1099 forms, while employees will require W-2 forms. Make sure to understand how payroll taxes work and budget for them accordingly.
5. Explore Tax Credits
Depending on your industry, you may be eligible for various tax credits that can significantly reduce your tax liability. For example:
- Research and Development (R&D) Tax Credit: If your startup is involved in innovation, you may qualify for significant R&D tax credits.
- Work Opportunity Tax Credit: This credit may apply if you hire individuals from certain targeted groups who face barriers to employment.
Research available tax credits in your state and industry to maximize savings during your first year.
The Role of Professional Advisors
While understanding tax regulations and deductions is crucial, enlisting professionals to help can provide a significant advantage. Consider working with a tax advisor or accountant who specializes in assisting startups. They can guide you through complex regulations and tailor a tax strategy to your specific business model, ensuring you optimize tax savings. Additionally, they can help you stay updated on changing tax laws and assist with tax return preparations.
Future-Proofing Your Startup Through Tax Planning
Effective tax planning is not only about survival; it’s about building a solid foundation for growth. As your startup grows and evolves, your tax needs will change. Periodic assessments of your tax strategy will ensure you’re still aligned with your financial goals. Here are some areas to consider for future-proofing your tax planning:
1. Scaling Your Tax Strategy
As your startup grows, so too will your revenues and complexities. What worked in your first year may not be suitable as you expand. Revisit your tax plan regularly and adjust it in response to growth strategies like branching into new markets or product lines.
2. Succession Planning
Determining how your business will be managed in the event of unforeseen circumstances is crucial for sustainability. Whether it’s through passing it on to a family member, selling, or dissolving, a robust succession plan considers tax implications for you and your beneficiaries.
3. Looking Ahead to Potential Exits
If you plan on selling your startup or going public, tax planning can influence your decision-making process. Understanding tax implications of gaining exits can help you maximize profits and avoid unnecessary burdens. Seek advice on potential tax liabilities associated with exits or changes in structure.
Conclusion: Make Tax Planning a Priority
The importance of tax planning for startups in their first year cannot be overstated. By prioritizing tax strategy early on, you can navigate the complexities of the tax landscape, reduce liability, conserve cash flow, and set a strong foundation for ongoing growth.
Remember, tax laws are dynamic and ever-evolving, making it imperative to stay informed and agile. As you embark on your entrepreneurial journey, meticulous tax planning will not only help protect your financial interests but also empower you to pursue your startup dreams with confidence. Invest time in understanding your tax responsibilities, leverage professional expertise, and embrace a proactive approach to tax planning—your future self will thank you!
By keeping tax planning at the forefront of your operation, you are not just preparing for a successful launch; you are laying the groundwork for a thriving enterprise that can weather any financial storm and emerge ready for long-term success.


