
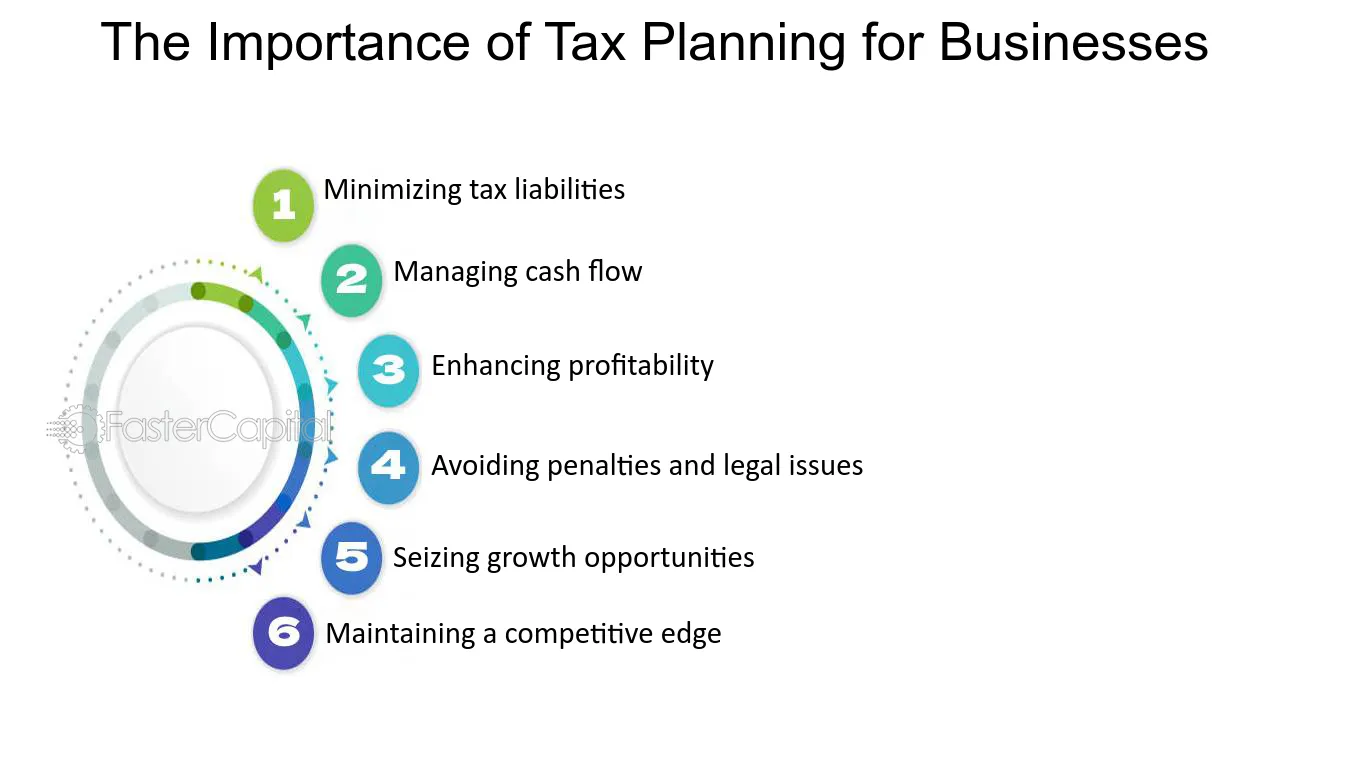
Starting a new business can feel like riding a roller coaster—there are thrilling highs, nerve-wracking lows, and a few unexpected twists and turns along the way. For many entrepreneurs, understanding the intricacies of tax planning is one of those twists that can significantly impact their startup’s growth trajectory. This article seeks to dissect why tax planning is crucial for startup growth and expansion and provide insights for new business owners looking to navigate this often-overlooked aspect of entrepreneurship.
Understanding Tax Planning
At its core, tax planning involves the analysis of a financial plan or situation to ensure tax efficiency. Think of tax planning as a strategic game that requires you to map out how to make the most of your financial resources while minimizing your tax liabilities. Proper planning can lead not just to immediate savings, but to long-term stability for your startup.
The Start of Your Journey
When you launch a startup, one of your primary focuses will be acquiring customers, building your brand, and ultimately achieving profitability. However, inadequate tax planning can cloud these goals and create unanticipated headaches. Without a clear tax strategy in place, startups can face various issues, including cash flow problems, missed deductions, and even penalties.
Cash Flow Management and Stability
Cash flow is the lifeblood of any business, particularly for startups, where finances can be tight. A sound tax planning strategy helps ensure that adequate cash flow is maintained throughout the year. By understanding and estimating tax liabilities, you can better manage your budget, allocate resources more effectively, and plan for future expenses.
For instance, if you know that your tax liability will be due in three months, you can set aside a portion of your income each month specifically for that expense, preventing a cash crunch just when you need funds for other operational costs. Additionally, tracking your income and expenses more closely can help you identify potential savings opportunities that can enhance your cash flow.
Maximizing Deductions and Incentives
One of the most compelling reasons for diligent tax planning is the ability to maximize deductions and credits. For startups, this can include business expenses such as:
- Operational Costs: Rent, utilities, salaries, advertising, and office supplies can all be deducted.
- Research & Development Costs: If your startup is involved in innovation, you might be eligible for R&D tax credits that can significantly lighten your tax burden.
- Home Office Deductions: If you operate from home, you may qualify for deductions related to your home office.
Making a habit of documenting your expenses can help you identify potential deductions and credits that you may not otherwise consider. Tax software and professional help can streamline this process and assure you’re not leaving money on the table.
Avoiding Common Pitfalls
Many startups fall prey to the ‘set it and forget it’ mindset when it comes to taxes. Initial excitement can mask potential oversights. Younger businesses may not realize that tax laws can change annually. Moreover, not keeping abreast of changes in tax codes can mean you miss out on valuable credits or bonuses, setting you back when you could have been progressing.
Furthermore, tax mistakes can be expensive. Errors can result in costly audits, penalties, or even legal issues. By putting tax planning in your entrepreneur toolkit, you preempt potential pitfalls and keep your company on a path to growth.
Building Business Credit and Reputation
As your startup matures, building a solid credit history can be vital for expansion. Tax planning can play a key role in this process. A well-managed tax profile signals to banks and investors that you are responsible and can handle financial commitments.
Timely tax payments and transparent financial practices build a trusting relationship with the IRS and other financial institutions. Additionally, maintaining accurate financial records, facilitated through effective tax strategy, can make it easier to obtain loans when expansion opportunities arise.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
Attracting Investors
Investors are keenly interested in the financial health of startups. Clear tax compliance can serve as a strong indication that your business model is well thought out. If your startup has a solid tax strategy in place, it can also showcase to potential investors that you are proactive and prepared for challenges down the road.
Investors want to see a business that can scale without stumbling over tax liabilities. A strong tax plan reassures them that both risks have been assessed and manageable growth strategies have been determined. Being able to share a concrete tax strategy during pitches can bolster your credibility significantly.
Strategic Business Decisions
Effective tax planning is not merely a reactive measure; it also informs strategic decision-making processes. A clear understanding of tax ramifications can guide important business choices, such as:
-
Choosing a Business Structure: The entity you select (LLC, Corporation, S-Corp, etc.) can significantly impact tax obligations. Early tax planning can help you make the right choice based on your long-term goals.
-
Timing Purchases: Depending on the nature of your expenses, it may make more sense to incur expenses in a different tax year to decrease tax liabilities appropriately.
-
Employee Hiring and Compensation: The structuring of incentivization could include tax considerations, appealing for recruiting talent while managing overall tax implication.
Planning for the Future
Startups often grow into larger businesses, and having a robust tax strategy in place prepares you for scaling. As your revenue increases, so will your tax liability. Knowing this will allow you to effectively set aside the proper funds and adjust expenditures accordingly.
Moreover, thinking ahead can help you anticipate challenges such as cross-border taxation, mergers and acquisitions, or navigating multi-state tax obligations if you plan to expand geographically.
Engaging a Tax Professional
While self-learning can be helpful, partnering with a tax professional or consultant can elevate your tax strategy. A qualified expert can steer you in the right direction based on the current landscape of tax laws, local regulations, and latest developments. This partnership can save you time, ensure compliance, and optimize your overall tax situation.
Best Practices for Startup Tax Planning
- Stay Organized: Implement an efficient record-keeping system to track income and expenses throughout the year.
- Set Aside Money for Taxes: Always maintain a fund for tax payments, ensuring you can cover liabilities when due.
- Review Your Tax Strategy Annually: Tax laws are in constant flux—make annual review part of your routine.
- Get Professional Help: Don’t hesitate to consult with tax experts who can offer tailored advice for your business model and industry.
Conclusion
Tax planning is not just a checkbox for compliance; it’s a vital component of health, sustainability, and growth for startups. Understanding tax laws, maximizing deductions, and planning for the future will empower you to weather the ups and downs of entrepreneurship.
Ultimately, being proactive rather than reactive can provide your startup the stability it needs to flourish in a competitive landscape. Consistent attention to tax strategy not only paves the path for day-to-day operations but also builds a sustainable future capable of expanding and adapting to market shifts.
By weaving thoughtful tax planning into your financial fabric now, you set your startup on a solid foundation from which to innovate, grow, and ultimately, thrive in the bustling world of entrepreneurship.


