
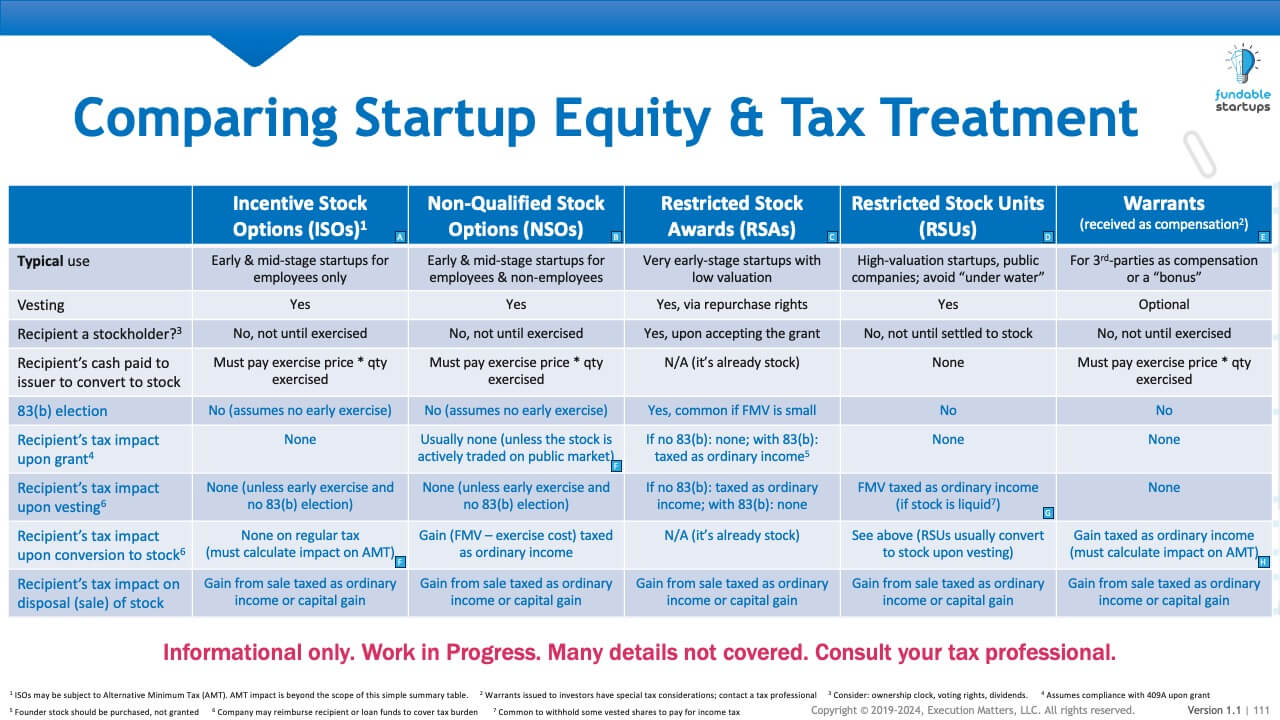
Equity compensation has become a cornerstone of startup culture, motivating founders and their teams to sweat through challenges with the promise of a substantial payoff. However, navigating the murky waters of tax implications tied to equity compensation can often feel like a daunting task. Whether you’re a startup founder or considering entering the entrepreneurial realm, understanding the tax landscape related to equity compensation is crucial for your financial health and long-term success. This article will explore the tax implications of equity compensation for startup founders, offering insights, tips, and actionable advice. So, let’s dive in!
Understanding Equity Compensation
Before jumping into the tax implications, let’s clarify what equity compensation entails. At its core, equity compensation refers to the practice of giving employees or founders an ownership stake in the company as part of their remuneration package. This could manifest as:
- Stock Options: These give an employee the right to purchase shares at a predetermined price within a specific time frame.
- Restricted Stock Units (RSUs): RSUs are company shares granted to an employee as part of a compensation package, but specific conditions must be met before the shares fully vest.
- Stock Grants: These involve the actual transfer of shares outright, often with some vesting restrictions.
Equity compensation is particularly appealing for startups looking to attract top talent without immediately burdening their limited cash flow. However, the tax implications can vary significantly based on the type of equity awarded.
Tax Implications of Stock Options
Incentive Stock Options (ISOs)
Incentive Stock Options, often referred to as ISOs, are a popular form of equity compensation for startups. With ISOs, employees can purchase company shares at the grant price and potentially benefit from favorable tax treatment. Here are some key tax points to consider:
-
No Immediate Tax on Granting or Exercise: Employees are not taxed when options are granted or when they exercise them (purchase the stock) if certain conditions are met. This is hugely beneficial as it allows employees to participate in a company’s growth without immediate tax liability.
-
Alternative Minimum Tax (AMT): While there is no immediate tax upon exercise, ISOs can trigger AMT. The difference between the exercise price and the fair market value (FMV) at the time of exercise can be calculated as income for AMT purposes. This can lead to an unexpected tax bill, so founders should consult a tax professional to navigate this loophole carefully.
-
Long-term Capital Gains Tax: If you hold shares bought through ISOs for at least one year after exercise and two years from the grant date, you may qualify for long-term capital gains tax on any profit when you sell the stocks. This tax rate usually ranges from 15% to 20%, which is often more favorable than ordinary income tax rates.
Non-Qualified Stock Options (NSOs)
Non-Qualified Stock Options, or NSOs, do not enjoy the same tax benefits as ISOs but are common in startup compensation packages. Here are the critical aspects:
-
Taxed at Exercise: Unlike ISOs, NSOs are taxed at the time of exercise. This means that when you exercise them, the difference between the exercise price and the FMV is taxed as ordinary income. It’s important to consider the timing of your exercise carefully to avoid a hefty tax swing.
-
No AMT Concerns: NSOs do not trigger AMT, making them slightly easier to manage from a tax perspective.
-
Capital Gains on Sale: Similar to ISOs, any gain made on the sale of shares obtained through NSOs is subject to capital gains taxes. If the stock is held for over a year, it will be taxed at long-term capital gains rates.
Tax Implications of RSUs
Restricted Stock Units (RSUs) are becoming increasingly popular in startup compensation packages due to their simplified tax treatment. Here’s what you need to know:
-
Tax at Vesting: The tax implications for RSUs are straightforward; taxes are triggered when the RSUs vest. At vesting, the FMV of the shares is considered ordinary income and is subject to payroll taxes.
-
Holding Period: Post-vesting, any gain from the sale of RSUs is taxed as capital gains. Holding onto the shares for at least a year will qualify you for the long-term capital gains rate, which is beneficial compared to ordinary income tax.
-
No Upfront Costs: Unlike stock options, RSUs have no upfront purchase price. This means there’s no exercise price to consider, making them easier to handle for founders who may not have immediate cash liquidity.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
Tax Implications of Stock Grants
Stock grants are the simplest form of equity compensation. Here’s how they work from a tax perspective:
-
Tax at Transfer: Stock grants are taxed as ordinary income at the time of transfer (when the shares are granted, not when they are sold). The amount that is taxable is the FMV of the stock at the time of transfer.
-
Capital Gains Tax on Sale: If the shares are held after the initial transfer, any gain from the eventual sale will also be taxed as capital gains, which can lead to favorable long-term rates if held for over a year.
Tax Strategies for Startup Founders
As a startup founder, navigating the tax implications of equity compensation doesn’t have to be a headache. Here are some strategic tips:
-
Consult a Tax Professional: Given the complexities of tax laws and potential changes over time, consulting with a tax advisor can help you build a suitable financial strategy. They can help you understand AMT implications, timing for exercising stock options, and more.
-
Understand Your Equity Compensation Package: Knowledge is power. Make sure you fully understand the terms of any equity grants you receive, including vesting schedules and the specific tax implications associated with them.
-
Plan Your Exercise Timing: Timing your option exercise is critical for minimizing tax liabilities. Consider your company’s future growth potential, current financial liquidity, and tax brackets to determine the best timing for exercising stock options.
-
Consider 83(b) Elections: If you’re granted stock outright or if you receive restricted stock, consider making an 83(b) election. This allows you to be taxed at the start on the overall value of the shares instead of at vesting, which could save you taxes in the long run based on the increased value of the shares.
-
Diversify Your Equity Portfolio: Holding too much of your net worth in stock from your startup can be risky. Diversification can help mitigate potential tax implications related to liquidity and market fluctuations.
-
Be Attentive to Changes in Tax Laws: The tax environment is continually evolving, especially for tech startups. Stay informed and adapt to any changes in legislation that may impact your equity compensation.
The Bottom Line
Equity compensation offers startup founders the opportunity to benefit significantly from their hard work and dedication. However, the associated tax implications can be complex and may catch individuals off guard if unanticipated. From understanding the difference between ISOs and NSOs to grasping the importance of capital gains taxes on RSUs and stock grants, knowledge is paramount. Engaging with a tax professional early and often can help navigate these waters more efficiently, ensuring you take full advantage of your equity compensation without falling prey to unforeseen tax pitfalls.
By preparing ahead and being proactive, you can focus on what really matters: building a successful business while maximizing the financial rewards of your equity compensation package. Always stay informed, be strategic about your decisions, and consult experts as needed, and you will be well on your way to financial success as a startup founder. Happy building!


