
Setting up a startup is an exhilarating journey—filled with innovative ideas, inspiring collaborations, and the potential for success. However, it can also be daunting, especially when it comes to navigating the complex world of business structure and taxation. One of the most popular legal structures for new businesses in the United States is the Limited Liability Company (LLC). If you’re a startup founder contemplating your options, you might be asking, “What are the tax advantages of an LLC for startup founders?” In this article, we’ll explore the benefits of forming an LLC, particularly from a tax perspective, and why it may be the right choice for your burgeoning venture.
Understanding LLCs: A Quick Overview
Before diving into the tax advantages, let’s briefly clarify what an LLC is. An LLC is a hybrid business structure that combines the characteristics of a corporation and a partnership. It provides limited liability protection for its owners—known as members—while offering the operational flexibility and tax benefits of a partnership. This unique combination makes LLCs especially appealing for entrepreneurs.
Why LLCs Are Popular Among Startup Founders
-
Limited Liability Protection:
One of the primary benefits of forming an LLC is the limited liability protection it offers. This means that members are generally not personally responsible for the debts and liabilities of the business. In the case of lawsuits or business debts, the finances of the individual members are typically protected. This crucial advantage allows startup founders to pursue their ideas without the constant fear of personal financial ruin. -
Flexible Management Structure:
Unlike corporations, which have strict management and operational requirements, an LLC allows for a flexible management structure. Startup founders can choose to manage the business themselves or appoint managers to run the day-to-day operations, giving them more control over their venture. -
Less Formality:
LLCs require less paperwork and ongoing compliance than corporations. This can be a significant advantage for startup founders who want to focus on growing their business rather than dealing with extensive regulatory filings and meetings.
Tax Advantages of LLCs for Startup Founders
Now that we’ve established why LLCs are popular, let’s delve into the tax advantages that make this structure particularly attractive for startup founders.
1. Pass-Through Taxation
One of the most significant tax advantages of an LLC is the pass-through taxation. In an LLC, the business itself does not pay federal income taxes. Instead, profits and losses are passed through to the individual members, who report their share on their personal tax returns. This means that the members avoid the “double taxation” that corporations typically face—where a corporation pays taxes on its profits, and then shareholders pay taxes on dividends.
For startup founders, this can result in substantial tax savings. When profits are reported on individual tax returns, they may be subject to lower tax rates, particularly for members in certain income brackets. Additionally, startup founders can offset income from the LLC with any losses incurred in the early stages, making it easier to manage cash flow during the crucial startup phase.
2. Flexibility in Profit Distribution
Unlike corporations, which are required to distribute profits based on ownership percentage, LLCs offer flexibility in how profits are allocated among members. This feature allows startup founders to tailor distributions based on different factors, such as capital contributions, roles within the company, or specific agreements made among members.
For example, if one member is more actively involved in the day-to-day operations while another contributes primarily as an investor, the startup can adjust profit distribution to reflect these contributions. This flexibility can enhance member relations and create a more equitable environment among the founders.
3. Deductible Business Expenses
Starting a business often comes with a range of expenses, from office supplies and insurance to marketing costs and employee salaries. One of the key tax advantages of an LLC is that many business expenses are tax-deductible. This means that members can reduce their taxable income by deducting these legitimate business expenses before calculating their taxes.
For startup founders, deducting business expenses can lead to significant cost savings. If your LLC incurs expenses in the early stages, you can claim those deductions when filing your personal tax return, which can help mitigate losses and help you break even sooner.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
4. Self-Employment Taxes
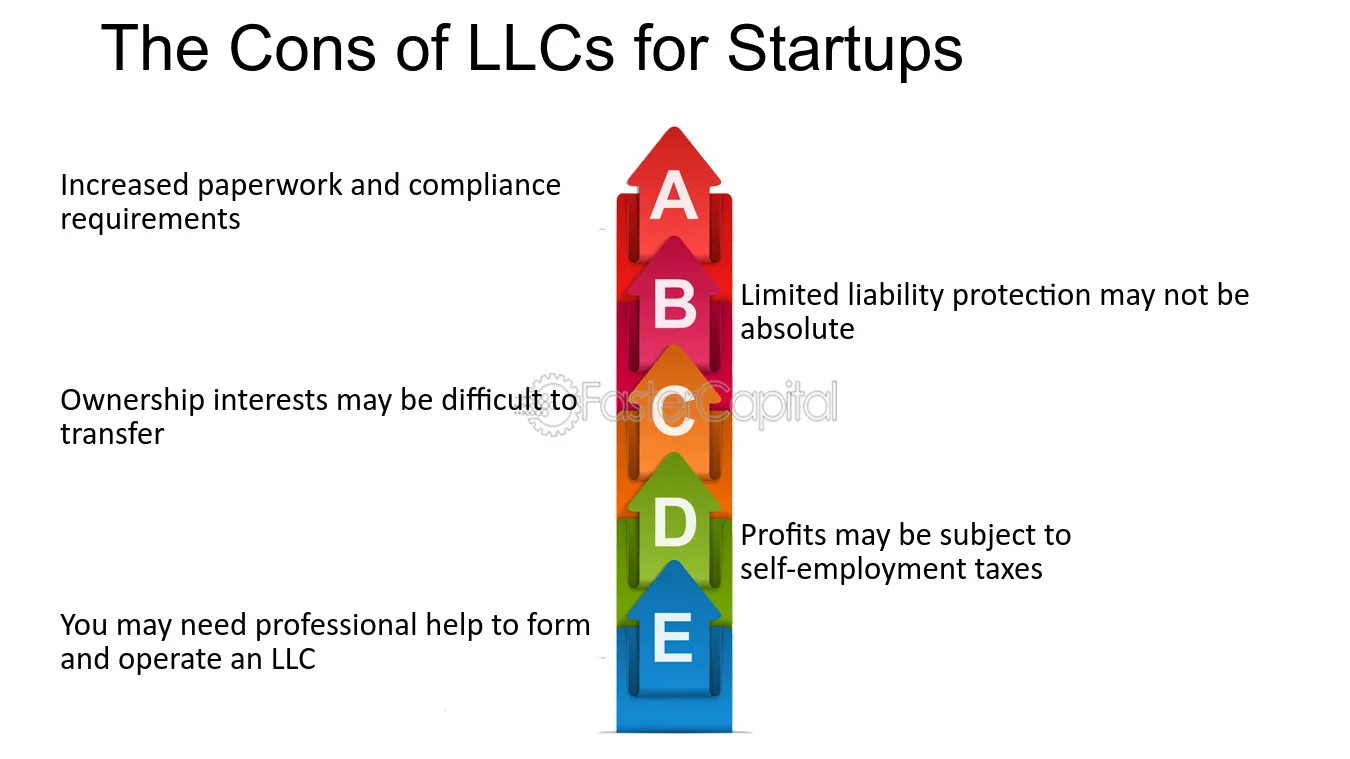
When operating an LLC, members typically pay self-employment taxes on their share of the business’s income. While this may initially seem like a downside, it can actually present an opportunity for tax optimization. Since self-employed individuals are responsible for both the employee and employer portions of Social Security and Medicare taxes, they can also deduct half of these taxes from their taxable income.
Moreover, members can structure their LLCs in a way that allows them to take a salary and also receive distributions from the business. By doing so, they can potentially lower their self-employment tax liability, resulting in further savings.
5. Qualified Business Income Deduction
Thanks to the Tax Cuts and Jobs Act of 2017, many LLC members may qualify for the Qualified Business Income (QBI) deduction. This provision allows eligible taxpayers to deduct up to 20% of their qualified business income when filing their tax returns, providing a significant advantage for startup founders.
However, it’s essential to understand the limitations and eligibility requirements for this deduction, as certain factors—like income level and type of service provided—can impact qualification. Nonetheless, if your startup qualifies, this deduction can be an excellent way to enhance your tax benefits.
Considerations When Forming an LLC
While the tax advantages of forming an LLC are substantial, it’s essential to consider certain factors when deciding if this structure is right for your startup:
-
State-Specific Regulations: The legal and tax treatment of LLCs varies from state to state, affecting fees, regulations, and tax advantages. Understanding your state’s specific laws is crucial before forming an LLC.
-
Ongoing Compliance: While LLCs have fewer formalities than corporations, they still have some ongoing compliance requirements, such as annual reports and fees in many states. Keep these in mind to avoid penalties.
-
Employment Taxes: As an LLC member, you’re considered self-employed and must pay self-employment taxes. It’s essential to budget for these taxes to ensure you’re financially prepared.
Conclusion: Is an LLC Right for Your Startup?
In conclusion, the LLC structure provides numerous tax advantages that can benefit startup founders. From pass-through taxation and flexible profit distribution to access to deductible business expenses and potential self-employment tax savings, forming an LLC can lead to significant financial benefits for your startup. However, every business is unique, and factors such as industry, state regulations, and your specific financial situation should guide your decision.
If you’re considering forming an LLC, it’s advisable to consult with a tax professional or an attorney who specializes in business law. They can provide tailored advice that aligns with your vision and goals, ensuring that you make the best decision for your startup.
Establishing a new business is a bold step toward pursuing your dreams. By taking advantage of the potential tax benefits of an LLC, you can position yourself for greater success on your entrepreneurial journey. Remember, the right business structure can be a crucial component of your startup strategy, making it even more important to weigh your options carefully. Happy travels on your entrepreneurial adventure!


