
Starting a new business is an exciting adventure filled with countless decisions that can shape the future of your endeavor. Among the myriad choices you’ll face, one of the most crucial is selecting the right business structure. Among the popular options, partnerships stand out for their collaborative nature and shared responsibilities. However, while a partnership can foster unity and shared vision, it also introduces a host of tax implications that every entrepreneur should carefully consider. In this article, we’ll explore the intricacies of a partnership structure for startups, specifically focusing on the tax ramifications it entails.
Understanding Partnership Structures
Before diving into the tax implications, let’s clarify what a partnership structure looks like. Essentially, a partnership involves two or more individuals (or entities) who jointly own and operate a business. Partners share in the profits, losses, and decision-making processes. There are several types of partnerships:
-
General Partnership: In this arrangement, all partners share equal responsibility and liability for the business’s debts. This structure is straightforward and often preferred for small startups.
-
Limited Partnership (LP): This structure has both general partners and limited partners. While general partners manage the business and are personally liable for debts, limited partners contribute capital and enjoy liability protection but are not involved in daily operations.
-
Limited Liability Partnership (LLP): Similar to an LP, this structure protects each partner from personal liability for the misconduct or negligence of other partners. It’s a popular choice for professional service businesses, such as law or accounting firms.
-
Joint Venture: This is a partnership for a specific project or limited time, allowing parties to collaborate without merging their entire businesses.
The Benefits of Choosing a Partnership Structure
Before we delve into the tax implications, it’s essential to recognize some of the benefits of a partnership structure for startups:
-
Shared Burden: With partners, responsibilities, and workloads can be split, making the operational side of running a business less daunting.
-
Collaboration and Expertise: Different partners often have varied skills, expertise, and resources, which can contribute significantly to the venture’s success.
-
Flexibility: Partnerships offer flexibility in organization and management, allowing partners to develop a structure that best suits their needs.
-
Pass-Through Taxation: Many partnerships benefit from pass-through taxation, where income is taxed at the individual partner level instead of the business level, potentially minimizing the overall tax burden.
Diving into Tax Implications
As promising as partnerships can be, the tax implications involved can be complex and must be understood to make an informed decision. Here are some key tax considerations for startup partnerships:
1. Pass-Through Taxation
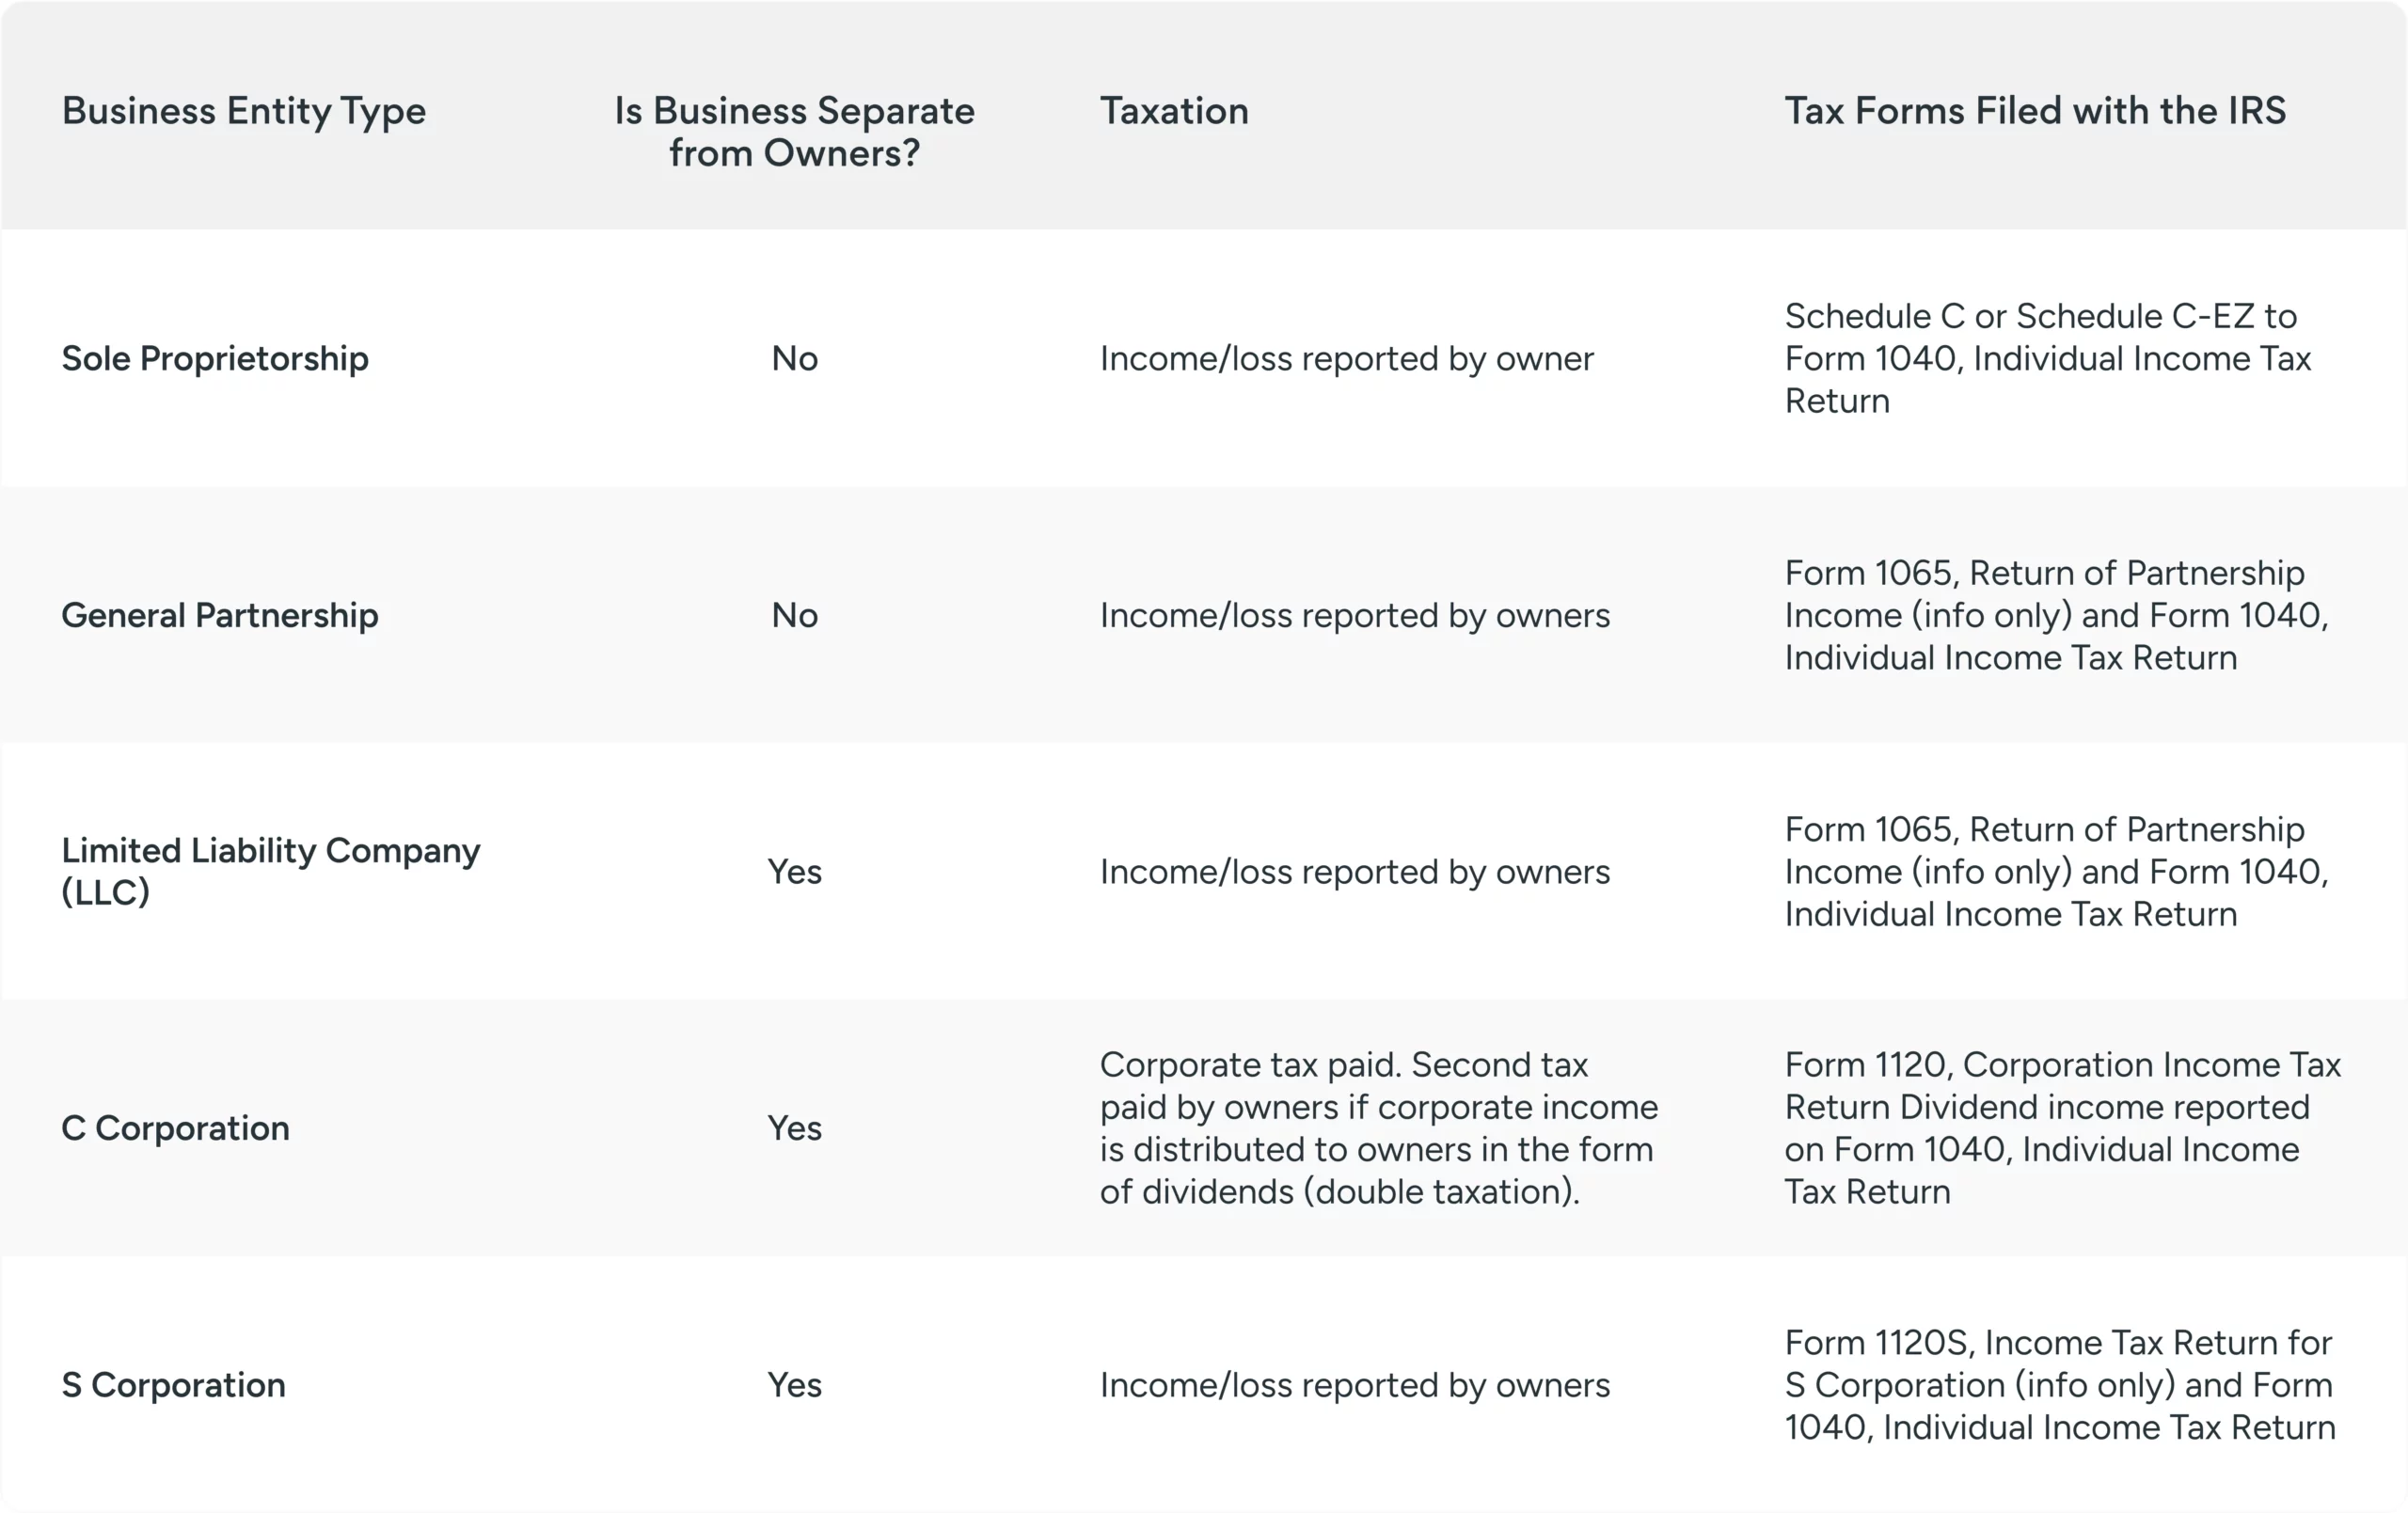
One of the most significant advantages of a partnership structure is pass-through taxation. In a partnership, the business itself does not pay federal income tax. Instead, profits and losses are passed through to the individual partners, who report them on their personal tax returns. This means that:
-
Tax Reporting: Each partner must report their share of the partnership’s income or loss on their tax returns. The partnership files an informational return (Form 1065), but that doesn’t incur a tax liability at the business level.
-
Self-Employment Tax: Because partnerships are often treated as self-employed individuals, partners are typically responsible for paying self-employment taxes on their share of the income. This is an essential consideration, as self-employment tax rates can be substantial.
2. Deductibility of Expenses
In a partnership structure, partners can generally deduct business expenses from their share of the partnership’s income. This can include:
- Operating expenses, such as rent, utilities, and salaries.
- Equipment purchases can often be amortized or deducted through depreciation.
- Start-up costs, including market research and other initial expenditures.
Properly documenting these expenses is critical, as it can significantly affect the taxable income reported by each partner.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
3. Guaranteed Payments
Sometimes, partners may receive guaranteed payments for services provided to the partnership. These payments are treated as ordinary income and are subject to self-employment taxes. However, guaranteed payments are typically tax-deductible for the partnership, reducing the taxable income that passes through to the partners.
4. Distributions and Tax Basis
Distributions from the partnership to partners can also influence tax implications. Here’s how:
-
Partners receive distributions that are generally considered a return of capital. This means they aren’t taxed immediately upon distribution.
-
However, once a partner’s capital balance is reduced to zero, further distributions may be taxable as capital gains. Understanding each partner’s tax basis—you may want to consult a tax professional—is essential in managing this effectively.
5. State Tax Considerations
State tax laws vary widely, and it’s crucial to understand how the state in which you operate your partnership treats partnerships for tax purposes. Some states may impose additional business taxes or fees on partnerships, while others may offer incentives or favorable tax treatments for certain types of partnerships.
6. Filing Requirements and Deadlines
Partnerships must also adhere to specific filing requirements. When filing taxes, partnerships must complete Form 1065 by March 15 of the following year after the tax year ends. Each partner receives a Schedule K-1, detailing their share of the partnership’s income, deductions, credits, and more.
It’s crucial to maintain accurate records throughout the year to meet these deadlines and maintain compliance with tax laws.
7. Impact on Personal Taxes
While partnerships primarily impact the business’s operational structure, the ultimate effect on personal taxes for each partner should not be overlooked. Each partner will calculate their taxable income based on their share of the partnership, and fluctuations in business profitability can significantly affect their tax liabilities from year to year.
8. Potential for Higher Tax Rates
Depending on the overall income levels of the partners involved, the pass-through nature of partnership income could lead to higher individual tax rates. If the partnership is very profitable, partners may end up in a higher tax bracket, increasing their total tax liability.
Conclusion: Making the Best Choice for Your Startup
Choosing a partnership structure for your startup offers many advantages but comes with unique tax implications that must be navigated carefully. As you embark on this entrepreneurial journey, it’s crucial to understand the potential impact on your personal finances and tax responsibilities.
Consulting with a tax professional or accountant experienced in business structures will provide you with customized advice tailored to your specific situation. They can help you understand the nuances of pass-through taxation, deductions, and local laws that could affect your startup.
Ultimately, while a partnership can enhance collaboration, sharing expertise, and minimizing workloads, it’s essential to consider how it aligns with your long-term financial goals and tax environment. By taking the time to understand these implications, you can set the foundation for a successful, compliant, and financially sound venture.
Whether your startup is an exciting new app, a cozy café, or an innovative consulting firm, being equipped with the right knowledge about partnership structures and their tax implications can make a significant difference in your journey ahead. Happy startups, and may your business flourish!


