
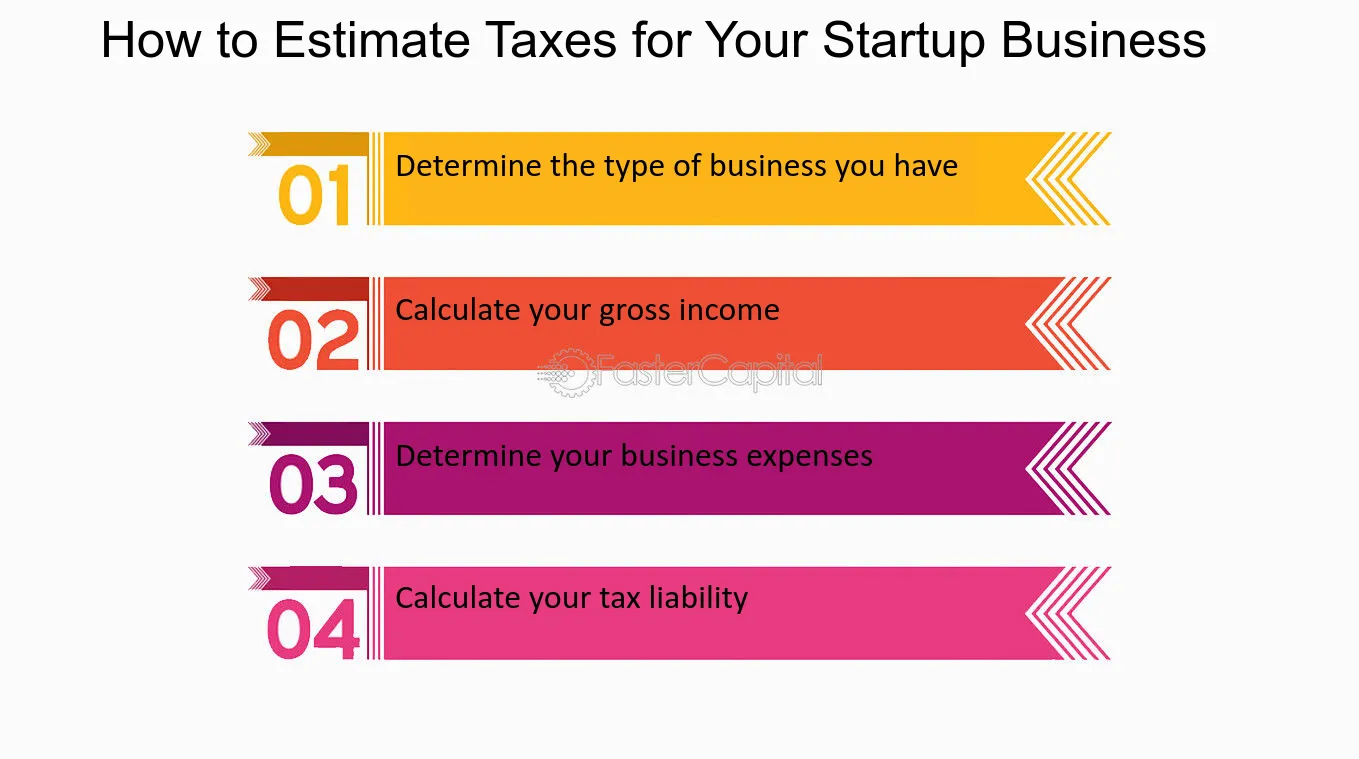
Starting a business is an exciting adventure filled with potential and challenges. For many entrepreneurs, the first year of revenue is a significant milestone that brings with it a host of new responsibilities, one of the most critical being taxes. Understanding how to calculate taxes on your startup’s first year of revenue is crucial for maintaining compliance, optimizing your finances, and planning for future growth.
Whether you’re a tech guru, a retail mastermind, or an aspiring restaurateur, knowing the ins and outs of taxation can save you from unpleasant surprises come tax season. This article will guide you through the various aspects of calculating taxes for your startup, providing valuable insights to help you navigate this essential aspect of running a business.
Understanding the Basics of Startup Taxes
1. Different Types of Taxes for Startups
When talking about taxes, it’s essential to understand that your startup may be subject to various types of taxation. These can include:
- Income Tax: Tax on your business’ profits.
- Self-Employment Tax: If you’re self-employed, you’ll be responsible for self-employment tax that covers Social Security and Medicare.
- Sales Tax: If you’re selling goods or services, you may need to collect sales tax from customers.
- Payroll Tax: If you have employees, you’ll need to file payroll taxes.
- Excise Tax: Relevant if your business is involved in specific activities, such as manufacturing or selling certain goods.
2. Different Business Structures and Their Tax Implications
Your startup’s legal structure plays a significant role in how you pay taxes. Here are the common types:
- Sole Proprietorship: All income is reported on your personal tax return. You will file a Schedule C along with your Form 1040.
- Partnership: Similar to a sole proprietorship but involves two or more individuals. Profit and losses pass through to the partners’ tax returns.
- LLC (Limited Liability Company): Can be taxed as a sole proprietorship, partnership, or corporation, depending on your choice.
- C Corporation: Separate legal entity, taxed separately from its owners. C corps face double taxation; the corporation pays taxes on its income and shareholders pay taxes again on any dividends they receive.
- S Corporation: Designed for small business owners, income passes through to shareholders, avoiding double taxation.
3. Determining Your Startup’s Tax Year
In the U.S., you must choose a fiscal year or a calendar year as your business’s tax year. Most startups use a calendar year (January 1 to December 31). However, if your business operates on a different fiscal year for accounting purposes, ensure that it aligns with your tax reporting.
Calculating Your Startup’s Revenue
1. What Constitutes Revenue?
Revenue is often referred to as the “top line” figure. It includes all income generated from your primary business activities, not accounting for any expenses. Understanding how to accurately determine your revenue is critical. Here’s how to categorize it:
- Sales Revenue: Income from sales of goods or services.
- Interest Income: Earnings from money that is invested or could be due to loans made to other parties.
- Rental Income: If your business includes leasing property.
Ensure every dollar earned is recorded accurately. This will set the foundation for your revenue calculations and tax implications.
2. Ways to Keep Track of Revenue
Keeping organized records is the key to hassle-free tax calculation:
- Use Accounting Software: Software like QuickBooks, FreshBooks, or Xero can simplify tracking revenue.
- Document Everything: Ensure every transaction, invoice, and receipt is documented. Use spreadsheets if software isn’t an option.
- Hire Professionals: Engaging a bookkeeper or accountant can help maintain accurate records and relieve you of the burden.
Understanding Business Expenses
Calculating taxes isn’t just about revenue; it’s equally about understanding your deductible expenses. These reduce your taxable income and ultimately lower the amount you owe in taxes.
1. Identifying Deductible Expenses
Common deductible expenses for startups include:
- Operating Expenses: Rent, utilities, internet, office supplies, etc.
- Cost of Goods Sold (COGS): Direct costs of goods sold in producing or purchasing products.
- Marketing and Advertising: Costs for promoting your business.
- Travel Expenses: Business-related travel expenses.
- Professional Fees: Fees paid for legal advice, accounting, or consulting.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
2. Separating Personal and Business Expenses
When you operate a startup, it’s crucial to keep your business expenses separate from personal expenses. Using dedicated bank accounts and credit cards for business is a recommended practice to avoid confusion and make tax preparation simpler.
Calculating Your Tax Liability
1. Income Calculation
Once you’ve determined your total revenue and identified your deductible expenses, it’s time to calculate your taxable income using the following formula:
[
\text{Taxable Income} = \text{Total Revenue} – \text{Total Expenses}
]
2. Applying the Tax Rate
Now that you have your taxable income, the next step is applying the applicable tax rate. Tax rates can fluctuate based on:
- Your business structure (sole proprietorship, LLC, etc.).
- Your total taxable income.
- State-level taxes, which vary greatly by state.
Consult the IRS guidelines and your local regulations for accurate tax brackets applicable to your business structure.
3. Consider Estimated Taxes
As a startup, you may be liable for estimated taxes if you expect to owe more than $1,000 when you file your return. Estimated taxes are paid quarterly, and it’s crucial to meet these deadlines to avoid penalties.
1. Business Expenses Deductions
As mentioned earlier, deducting business expenses is essential in minimizing taxable income. To make the most of deductions, familiarize yourself with:
- Standard Deduction vs. Itemized Deductions: Most small business owners skip itemizing and choose the standard deduction for simplicity. Understand which deductions apply to your situation.
- Section 179 Deduction: This allows you to deduct the full purchase price of qualifying equipment purchased or financed during the tax year.
2. Tax Credits for Startups
Tax credits directly reduce the amount of tax owed and are often available to startups focusing on innovation or specific sectors. Examples include:
- Research & Development Tax Credit: Available for businesses investing in research and development.
- Work Opportunity Tax Credit: Incentives for hiring employees from specific groups.
3. State and Local Tax Deductions
Some states offer additional incentives and deductions for businesses. Research your state’s specific programs and be sure to capitalize on any applicable credits or deductions.
Filing Your Taxes: What You Need to Know
1. When to File
Most businesses with a calendar year-end need to file by April 15. However, if you chose a different tax year, your filing deadline would change accordingly. Familiarize yourself with any extension options if needed, to avoid penalties.
2. Utilizing a Tax Professional
Navigating taxes can be complex, and many startups benefit from the expertise of a tax professional. An accountant familiar with small businesses can help you:
- Identify deductions and credits you may have overlooked.
- Ensure compliance with state and federal regulations.
- Optimize your tax strategy moving forward.
3. Keeping Future Records
Once you file, keep your tax records organized. These include profit-loss statements, receipts, and tax forms. The IRS recommends retaining records for at least three years, or longer in some cases.
Conclusion: A Roadmap to Tax Success for Startups
Calculating taxes on your startup’s first year of revenue can seem daunting, but breaking it down into manageable steps simplifies the process. From understanding the foundational concepts of income and expenses to recognizing deadlines and potential deductions, knowledge is your best ally.
Remember, as your startup grows, so too will the complexity of your finances and taxes. Proactive planning, diligent record-keeping, and consultation with qualified professionals will help pave the path for your business to not only survive but thrive in its financial journey.
In summary, focus on:
- Understanding your business structure and tax obligations.
- Diligently tracking revenue and expenses.
- Knowing your filing requirements and deadlines.
- Taking advantage of available deductions and credits.
By preparing yourself now, you can minimize stress when tax season rolls around, allowing you to focus on what truly matters—growing your startup and achieving your entrepreneurial dreams. With the right approach, taxes can become less of a burden and more of an organized part of your business strategy.


