
Starting a new venture is an exhilarating experience, filled with dreams, innovations, and opportunities. However, it often comes with the burden of expenses, especially when it comes to research and development (R&D). Fortunately, startups have various financial tools available to help them thrive, and one notable strategy is leveraging tax credits to offset research expenses. In this article, we’ll explore how startups can effectively use tax credits to safeguard their innovations while minimizing costs.
Understanding Research and Development Tax Credits
Research and Development Tax Credits are government-backed incentives designed to encourage innovation among businesses, particularly startups. These credits are primarily aimed at reducing the financial burden of R&D activities, allowing companies to reinvest more into their projects.
R&D tax credits can take various forms, including federal, state, and even local credits, each with its eligibility criteria and benefits. Understanding these nuances can empower startup founders to make informed decisions when planning their financial strategies.
The Importance of R&D for Startups
Innovation is the lifeblood of any startup. Whether you’re developing groundbreaking software, designing cutting-edge hardware, or simply trying to optimize an existing product, R&D plays a crucial role. However, R&D can be costly. According to the National Science Foundation, businesses spend around $400 billion annually on R&D in the United States alone.
For startups operating on tight budgets, the financial implications can be daunting. This is where tax credits come in—a lifeline that serves to cushion the financial impact while fueling growth and innovation.
Types of R&D Tax Credits
While many might be familiar with the federal R&D tax credit, numerous states offer their own credits, making it essential for startups to look beyond just federal benefits. Let’s delve into some of the most common types:
-
Federal R&D Tax Credit: Established by the Internal Revenue Code, this credit allows businesses to claim a percentage of their qualifying R&D expenditures. Generally, this involves activities focused on developing or improving products, processes, or software.
-
State R&D Tax Credits: Many states have enacted their own R&D tax credits, which can be combined with the federal credit. Each state has different rules regarding eligibility and the percentage of expenses that can be claimed.
-
Refundable Credits: Some states also offer refundable R&D tax credits, meaning that if your startup isn’t profitable yet, you can receive a cash payment instead of just a tax credit. This is particularly beneficial for early-stage startups.
-
Grants and Additional Incentives: In addition to tax credits, some local and state governments offer grants or other incentives aimed at promoting innovation. These can provide additional funding to offset R&D costs.
Qualifying Activities for R&D Tax Credits
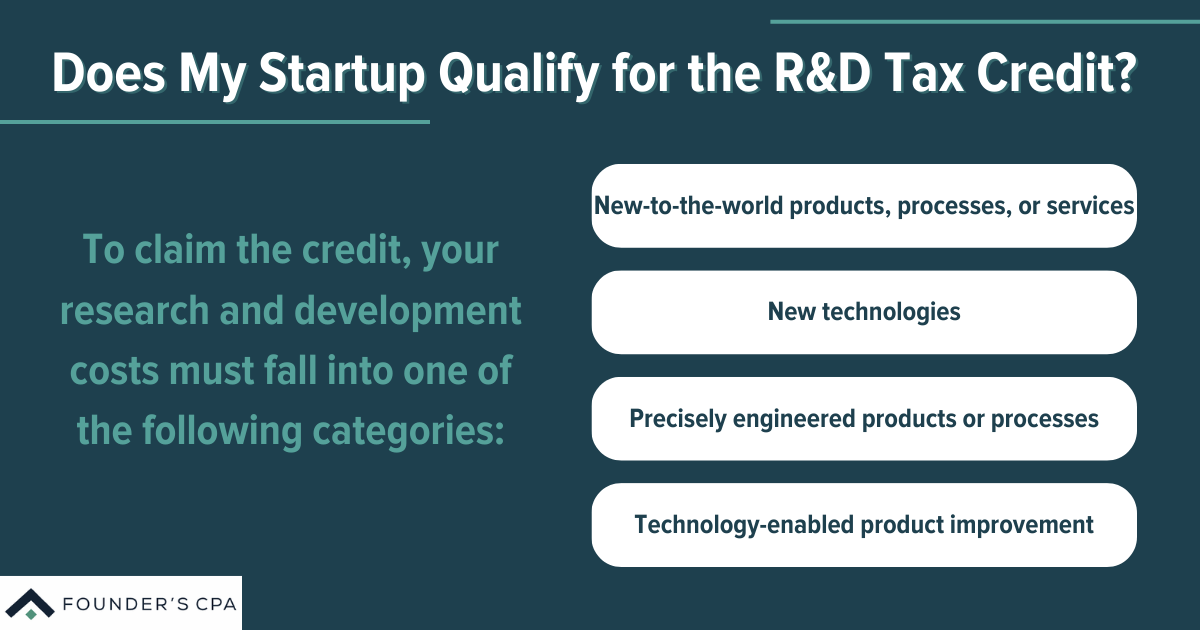
To effectively utilize these tax credits, startups must first understand what qualifies as R&D. The IRS defines qualified research activities as those that involve:
- Development or improvement of a product, process, technique, or software.
- Technical uncertainty, involving a substantial amount of experimentation, trial and error.
- The use of new or improved technologies or processes.
Understanding these criteria can help startups focus their R&D efforts on activities that maximize their eligible credit.
Steps for Startups to Leverage R&D Tax Credits
As a startup, navigating the world of tax credits can seem intimidating. However, the process is manageable by breaking it down into a few critical steps:
1. Conduct a Qualifying Activities Assessment
To begin with, startups should conduct an assessment of their R&D activities to identify what qualifies. This involves a thorough review of all projects, noting those that satisfy the IRS’s criteria. It can help to maintain detailed records of project timelines, budgets, experiments, and personnel involved in R&D.
2. Keep Detailed Documentation
One of the most significant aspects of successfully claiming R&D tax credits is having proper documentation to support your claims. This includes:
- Research plans and goals.
- Lab notebooks and experimental results.
- Payroll records for employees engaged in R&D activities.
- Costs associated with materials and supplies.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
3. Consult with a Tax Professional or Specialist
Once you’ve documented your R&D activities, consulting with a tax professional who specializes in R&D tax credits can prove invaluable. They’ll help ensure you’re claiming all eligible expenses and navigating the complexities of tax law. They can also assist in preparing and filing the necessary forms.
4. Claim the Credit on Your Tax Return
Once you’ve gathered your information and consulted with a tax professional, you can then claim the credit on your tax return. It’s essential to complete the appropriate forms (such as Form 6765 for federal and different forms for state credits) accurately and on time.
5. Monitor Changes in Legislation
Tax laws are constantly evolving, so staying informed about changes in R&D tax credits both federally and at the state level is crucial. Engaging a tax professional on an ongoing basis will help ensure that your startup continues to take advantage of any new incentives or amendments.
Tips for Maximizing R&D Tax Credits
Here are some additional tips to help your startup make the most of R&D tax credits:
1. Evaluate All Costs
Don’t just focus on salaries and direct costs. Make sure to account for expenses related to testing, overhead costs, supplies, and even utilities associated with your research activities.
2. Involve Your Whole Team
Encourage your team to actively think about R&D during the product development process. This can lead to more opportunities for R&D activities that qualify for tax credits.
3. Document Your Innovations
Regularly document the innovations and improvements that occur throughout your processes. This can make it easier to demonstrate the technical uncertainties and experimentation that the IRS requires for claiming credits.
4. Stay Up-To-Date on Deadlines
Most tax credits have specific deadlines and requirements. Ensure you’re organized and well ahead of crucial dates, as failure to meet these can result in losing out on potential credits.
Real-Life Case Study: A Startup’s Journey with R&D Tax Credits
Consider the case of Tech Innovations, a fledgling startup in the software industry. Like many startups, its founders faced the challenge of funding their research while attempting to carve out a niche in a competitive market.
By thoroughly assessing their R&D activities, they discovered that much of their work on developing a novel software algorithm qualified for federal and state R&D tax credits. With an organized tracking system in place, they documented their innovative efforts from early ideation to prototype development.
After consulting with a tax professional, they successfully claimed over $200,000 in tax credits on their first tax filing. This substantial savings allowed them to reinvest the funds back into their company, accelerating their product development timeline and enhancing their competitive advantage.
Conclusion
For startups, navigating the financial landscape of business can be complex and daunting. However, one of the most powerful strategies available is leveraging tax credits to offset research expenses. By understanding the available tax credits, qualifying activities, and the necessary steps to claim them, startups can prioritize innovation without succumbing to crushing financial constraints.
Startups like Tech Innovations have demonstrated the significant impact of R&D tax credits when strategically utilized. By staying informed and organized, taking advantage of the benefits available, and consulting professionals, startups can find themselves better positioned to succeed in their creative endeavors.
Remember, innovation fuels the future, and in a world that thrives on fresh ideas, harnessing tax credits might just be the key to unlocking a more sustainable and successful path forward.


