
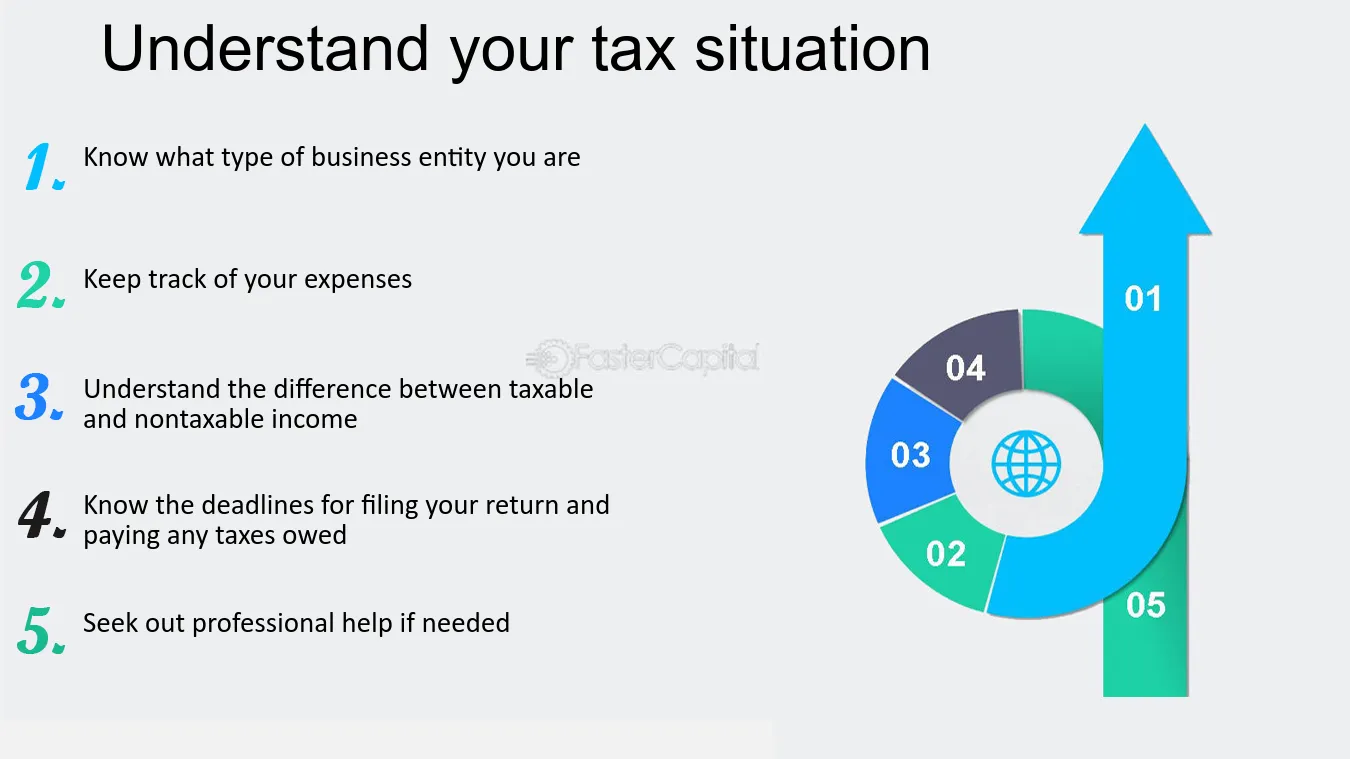
Navigating the world of taxes can feel overwhelming for any business owner, not least of all startup founders who are already juggling myriad responsibilities. As a startup founder, you’re wearing many hats—from product development to customer outreach—and tax preparation may feel like just one more daunting task on an endless to-do list. However, understanding how to prepare your startup’s taxes does not have to be a source of stress. In this guide, we’ll break down the essential steps to simplify the tax process and help you avoid common pitfalls.
1. Understand Your Startup Structure
Before delving into tax preparation, knowing your business structure is vital. Your startup may be organized as a sole proprietorship, partnership, Limited Liability Company (LLC), S Corporation, or C Corporation. Each structure has different tax obligations and implications.
- Sole Proprietorship: Simple to set up, but income is taxed as personal income.
- Partnership: Similar to sole proprietorship with pass-through taxation.
- LLC: Offers flexibility and limited liability; can be taxed as a sole proprietorship or corporation.
- S Corporation: Allows income to pass through to shareholders to avoid double taxation.
- C Corporation: Subject to corporate tax rates; income is taxed on both corporate and personal levels when dividends are distributed.
Understanding your structure will guide your tax obligations and the forms you’ll need to file.
2. Keep Detailed Financial Records
The foundation of effective tax preparation is meticulous record-keeping. Keeping track of income and expenses is crucial not just for taxes, but also for knowing the health of your business. Here are some tips:
- Use Accounting Software: Programs like QuickBooks, FreshBooks, or Xero can help streamline your financial record-keeping.
- Track Business Expenses: Keep all receipts, invoices, and relevant documents organized. This includes anything from office supplies to professional services.
- Separate Personal and Business Finances: Open a separate bank account for your business to make tracking income and expenses simpler.
3. Know Tax Deductions for Startups
Startups have access to various tax deductions that can significantly lower their taxable income. Familiarize yourself with potential deductions to maximize your savings:
- Startup Costs: You can deduct up to $5,000 in startup costs if your total expenses don’t exceed $50,000.
- Home Office Deduction: If you work from home, you may qualify for a home office deduction.
- Business Travel Expenses: If you travel for business, expenses like airfare, hotel stays, and meals can be deducted.
- Equipment and Supplies: Depreciation on equipment purchases can be deducted as well.
- Professional Fees: Legal, accounting, and consulting fees related to your business can also be deductible.
Understanding these deductions can have a significant impact on your overall tax bill.
4. Choose the Right Tax Year
Most businesses operate on a calendar year (January to December) for tax purposes, but you can also choose a fiscal year if it better suits your business cycles. Choosing the right tax year can affect how you report income and expenses, potentially leading to better cash flow management.
5. Set Aside Money for Taxes
Tax liabilities can catch you off guard if you’re not prepared. As a startup, it’s advisable to set aside a percentage of your income regularly to cover your tax obligations. A good rule of thumb is to reserve around 25-30% of your income for taxes.
6. Stay on Top of Tax Deadlines
Awareness of tax deadlines is crucial for avoiding penalties and late fees. Here are some important deadlines to keep in mind:
- April 15: Tax returns for individuals and single-member LLCs.
- March 15: Tax returns for S Corporations and partnerships.
- Quarterly Estimated Tax Payments: For many startups, estimated payments are due on April 15, June 15, September 15, and January 15 of the following year.
Mark these dates on your calendar to ensure you’re well-prepared and to avoid any last-minute rush.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
7. Consider Hiring a Tax Professional
While DIY tax preparation is an option, hiring a tax professional can save you time and reduce the risk of mistakes. An accountant or tax advisor specializing in startups can provide valuable insights on:
- Deductions you might miss.
- Structuring your business for optimal tax benefits.
- Planning for estimated taxes.
Investing in professional help could pay off significantly, especially if your startup experiences rapid growth.
8. Prepare Your Tax Forms
Once you have your financial records and deductions sorted, it’s time to prepare your tax forms. The forms you need will depend on your business structure:
- Sole Proprietorship: Schedule C (Form 1040)
- Partnership: Form 1065
- S Corporation: Form 1120S
- C Corporation: Form 1120
Ensure that you accurately report all income, expenses, and deductions. Check for changes in tax forms or regulations for the current year.
9. Review and Double-Check Your Returns
Before submitting your returns, it’s crucial to go through your forms meticulously to catch any errors. Mistakes can lead to audits or increased tax bills. Common areas to double-check include:
- Personal identification information
- Income calculations
- Deduction details
- Signatures before submission
10. File Your Taxes
After ensuring everything is correct, it’s time to file your taxes. You can do this electronically with e-filing services or by mail. If you owe taxes, you will want to make your payment as soon as possible to avoid additional interest and penalties.
11. Keep Records for Future Reference
Once your taxes are filed, don’t forget to keep copies of your tax documents and supporting records. The IRS typically recommends keeping records for at least three years. This documentation can be valuable if you ever face an audit or need to reference past tax returns.
12. Stay Informed About Changes in Tax Law
Tax laws frequently change, and it’s vital for startup founders to stay informed about any changes that could impact their tax obligations. Subscribe to newsletters from tax organizations or consult your accountant regularly to better understand how these changes affect your business.
13. Proactive Tax Planning for the Future
Tax preparation is not just a one-time event; it requires continuous planning and evaluation. Engage in proactive tax planning throughout the year by:
- Regularly updating your financial records.
- Reassessing your business structure if necessary.
- Consulting with your tax professional to discuss upcoming changes and strategies for the next tax year.
Conclusion
Preparing your startup’s taxes may feel like a daunting task, but breaking it down into manageable steps can make the process smoother and more efficient. From understanding your business structure to utilizing deductions and considering professional help, being proactive about your taxes will not only reduce stress but may also save you money.
Arming yourself with knowledge and good record-keeping habits ensures that your startup remains compliant and can thrive financially. Remember, tax season may come around each year, but with careful planning and informed strategies, you can face it head-on. In the words of Benjamin Franklin, “In this world, nothing can be said to be certain, except death and taxes.” So why not make the latter a little less painful? Happy filing!


