
Navigating the world of taxes can be a daunting task for anyone, but it becomes exponentially more complicated when you’re the owner of a startup. As a budding entrepreneur, your primary focus is often on growing your business, attracting customers, and innovating your products or services. However, understanding how to file taxes correctly is crucial for your startup’s success and sustainability. This article aims to provide you with essential insights into filing taxes as a startup owner, along with common pitfalls to avoid.
Understanding the Basics of Business Taxes
Before diving into the intricacies of tax filing, it’s vital to grasp the fundamental tax obligations that come with running a startup. In the United States, the IRS requires all businesses, regardless of their structure, to file annual returns. The type of return you file depends on how your business is organized—sole proprietorship, partnership, corporation, or limited liability company (LLC). Here are the common structures and their tax implications:
-
Sole Proprietorships: If you’re the only owner of your startup, you might be classified as a sole proprietorship. In this case, your business income and expenses are reported on your personal tax return (Form 1040, Schedule C).
-
Partnerships: If you own your startup with one or more partners, you’ll need to file a partnership return (Form 1065) and also report your share of the income on your individual tax return.
-
Corporations (C-Corps and S-Corps): Corporations are separate tax entities. C-Corps file Form 1120, while S-Corps file Form 1120S and pass corporate income, losses, and deductions to shareholders to report on their individual tax returns.
-
Limited Liability Companies (LLCs): LLCs can be taxed as sole proprietorships, partnerships, or corporations, depending on how many members are in the LLC and how they choose to file.
Understanding your business structure is fundamental to filing your taxes accurately. Now, let’s unpack some common mistakes startup owners make when tackling their taxes.
Common Mistakes to Avoid When Filing Taxes
1. Not Keeping Accurate Records
One of the most common mistakes startup owners make is failing to maintain accurate and organized financial records. Many entrepreneurs get caught up in the hustle and bustle of managing their business and overlook the importance of documenting income and expenses. Without precise records, you may end up underreporting or overreporting your income, which can lead to penalties or missed deductions.
Tip: Invest in accounting software or hire a bookkeeper to keep your records up-to-date. Regularly review your financial statements to make sure everything is in order.
2. Mixing Personal and Business Expenses
Another prevalent mistake is mixing personal and business expenses. If you use one credit card for both personal and startup expenses, it’s easy to lose track of what belongs where. This can make it difficult to accurately report business expenses while filing your taxes and may also raise red flags during an IRS audit.
Tip: Open a separate bank account and credit card specifically for your business. This will simplify your bookkeeping and help you keep things organized.
3. Overlooking Tax Deductions
Many startup owners are unaware of the numerous tax deductions available to them. From startup costs to business travel expenses, the IRS offers a range of deductions that can significantly lower your taxable income. Common deductions include:
- Business Equipment: You can deduct the cost of equipment such as computers and office furniture.
- Home Office Deduction: If you operate your startup from home, you may qualify for a home office deduction, which allows you to deduct a portion of your rent or mortgage and utilities.
- Travel Expenses: If you travel for business, you can deduct expenses related to transportation, lodging, and meals.
Tip: Regularly review potential deductions and keep all receipts and relevant documentation to support your claims.
4. Misunderstanding Employment Taxes
If you have employees, you need to familiarize yourself with employment taxes, which are separate from income taxes. This includes Social Security and Medicare taxes, unemployment taxes, and other state-specific taxes. Some startup owners mistakenly assume that they only need to pay personal income tax, neglecting their obligations as employers.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
Tip: Consult with a tax professional to ensure you fully understand your payroll tax responsibilities. Failing to meet these obligations can lead to hefty fines.
5. Ignoring Estimated Tax Payments
As a business owner, you may not receive a regular paycheck like an employee does, which is why you need to pay estimated taxes quarterly. Failing to make these payments can result in penalties and interest at tax time. Many startup owners overlook this requirement, which can significantly impact their finances.
Tip: Calculate your estimated taxes and set aside money each quarter. A tax professional can help you determine the correct amount to pay based on your projected income.
6. Not Keeping Up with Tax Law Changes
Tax laws are continually changing, and startup owners must stay informed about these shifts to avoid costly mistakes. Changes in deductions, credits, and tax rates can all affect how you file your taxes, and failing to keep up with these updates can lead to oversights.
Tip: Subscribe to tax-related newsletters and follow reputable accounting or tax blogs to stay up-to-date on relevant changes. Additionally, consider attending seminars or workshops tailored for small business owners.
7. Using Outdated Information
Many startup owners rely on outdated information or old tax strategies that may no longer comply with current laws. Tax rules can evolve, and strategies that worked last year may not be beneficial this year. Using old tactics can lead to missed opportunities for savings and compliance issues.
Tip: Review your tax strategy annually with a knowledgeable accountant who is updated on the latest tax laws that impact small businesses.
8. Not Seeking Professional Help
Although tax software might seem like a suitable DIY solution, many startup owners hastily underestimate the complexities of their tax situations. The implications of incorrect filings or missed deductions can far outweigh the cost of hiring a tax professional. While saving money might seem appealing in the short term, making costly mistakes can be detrimental in the long run.
Tip: Invest in a qualified tax professional, especially during your startup’s first few years. Their insights and expertise can save you money and ensure that you comply with tax regulations.
9. Forgetting About State and Local Taxes
While many startup owners focus on federal taxes, it’s essential not to overlook state and local tax obligations. Depending on where your business is located, you may be subject to various additional taxes, such as sales tax, franchise tax, or property tax. Failure to comply with these regulations can lead to additional fines and complications.
Tip: Research your specific state and municipality’s tax requirements. Again, a tax professional can provide valuable insight into local obligations.
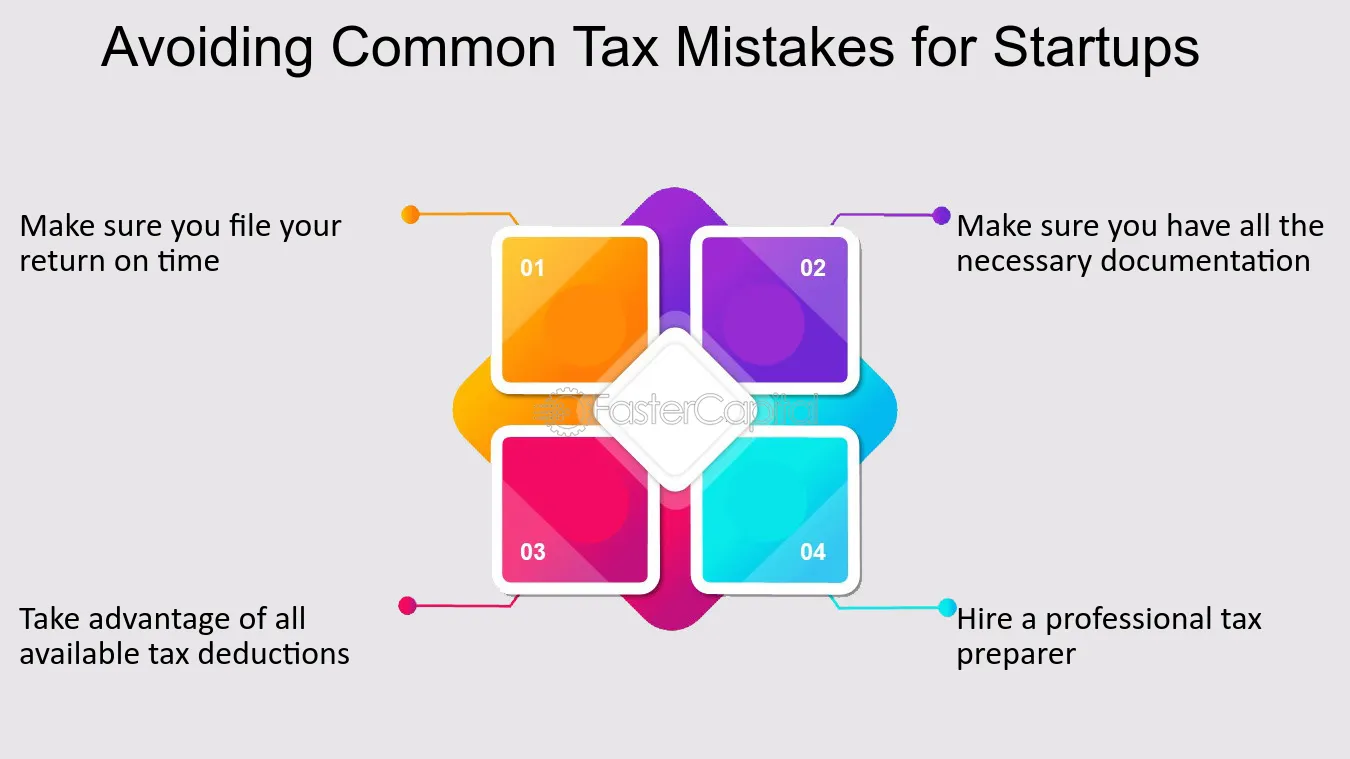
10. Filing Late or Not At All
Procrastination can be a startup owner’s worst enemy when it comes to taxes. Some entrepreneurs may avoid filing taxes out of fear, confusion, or simply being overwhelmed by their workload. However, failing to file your taxes or filing late can result in significant penalties and interest accrual.
Tip: Create a tax calendar that outlines key deadlines for filing and payments. Set reminders well in advance to ensure you’re always on track.
Conclusion: Stay Informed and Proactive
Filing taxes as a startup owner doesn’t have to be an overwhelming task. By understanding your obligations, maintaining organized records, and seeking professional guidance when needed, you can navigate the tax landscape with confidence. Avoiding common mistakes will not only help you save money but also ensure that your business remains compliant and primed for growth.
As you focus on elevating your startup, take the time to educate yourself about tax responsibilities. Remember that being proactive and informed will put you in a better position to succeed financially. With the right strategies, resources, and knowledge, you can overcome the confounding world of taxes and keep your business on the path to prosperity.


