
As an entrepreneur, the thrill of launching a startup often comes hand-in-hand with a laundry list of responsibilities that can be overwhelming. Among these responsibilities, understanding your tax obligations stands out as both a critical and stressful task. If you’re a startup owner, one of the most daunting areas is the requirement to pay quarterly taxes—a process that can confuse even the most seasoned business leaders. In this article, we’ll break down what you need to know about quarterly taxes for startups, helping you transform a potentially chaotic task into a manageable one.
What Are Quarterly Taxes?
Quarterly taxes, also known as estimated tax payments, are payments that self-employed individuals and businesses make to the IRS throughout the year. Unlike employees who have wages withheld by their employers for taxes, startup owners must estimate their tax liability and pay those amounts directly to the IRS.
The IRS expects you to make these payments if you expect to owe tax of $1,000 or more when you file your tax return. The payments are generally due in four installments per year, and they are based on your estimated income for that year.
Why Are Quarterly Taxes Important?
Neglecting to pay quarterly taxes can lead to several consequences. Not only can you incur penalties for underpayment, but you also risk facing a hefty tax bill at the end of the year. Here are some reasons why timely quarterly tax payments are essential:
-
Avoid Penalties and Interest: The IRS imposes penalties for underpayment and late payment of taxes, which can add up quickly. Making quarterly payments helps you avoid these additional charges.
-
Cash Flow Management: By breaking up your tax payments throughout the year, you reduce the financial burden at tax time, allowing for better cash flow management for your startup.
-
Accurate Financial Reporting: Consistent quarterly tax payments give you a clearer picture of your business’s financial health and can help with budgeting for the future.
How to Calculate Your Quarterly Taxes
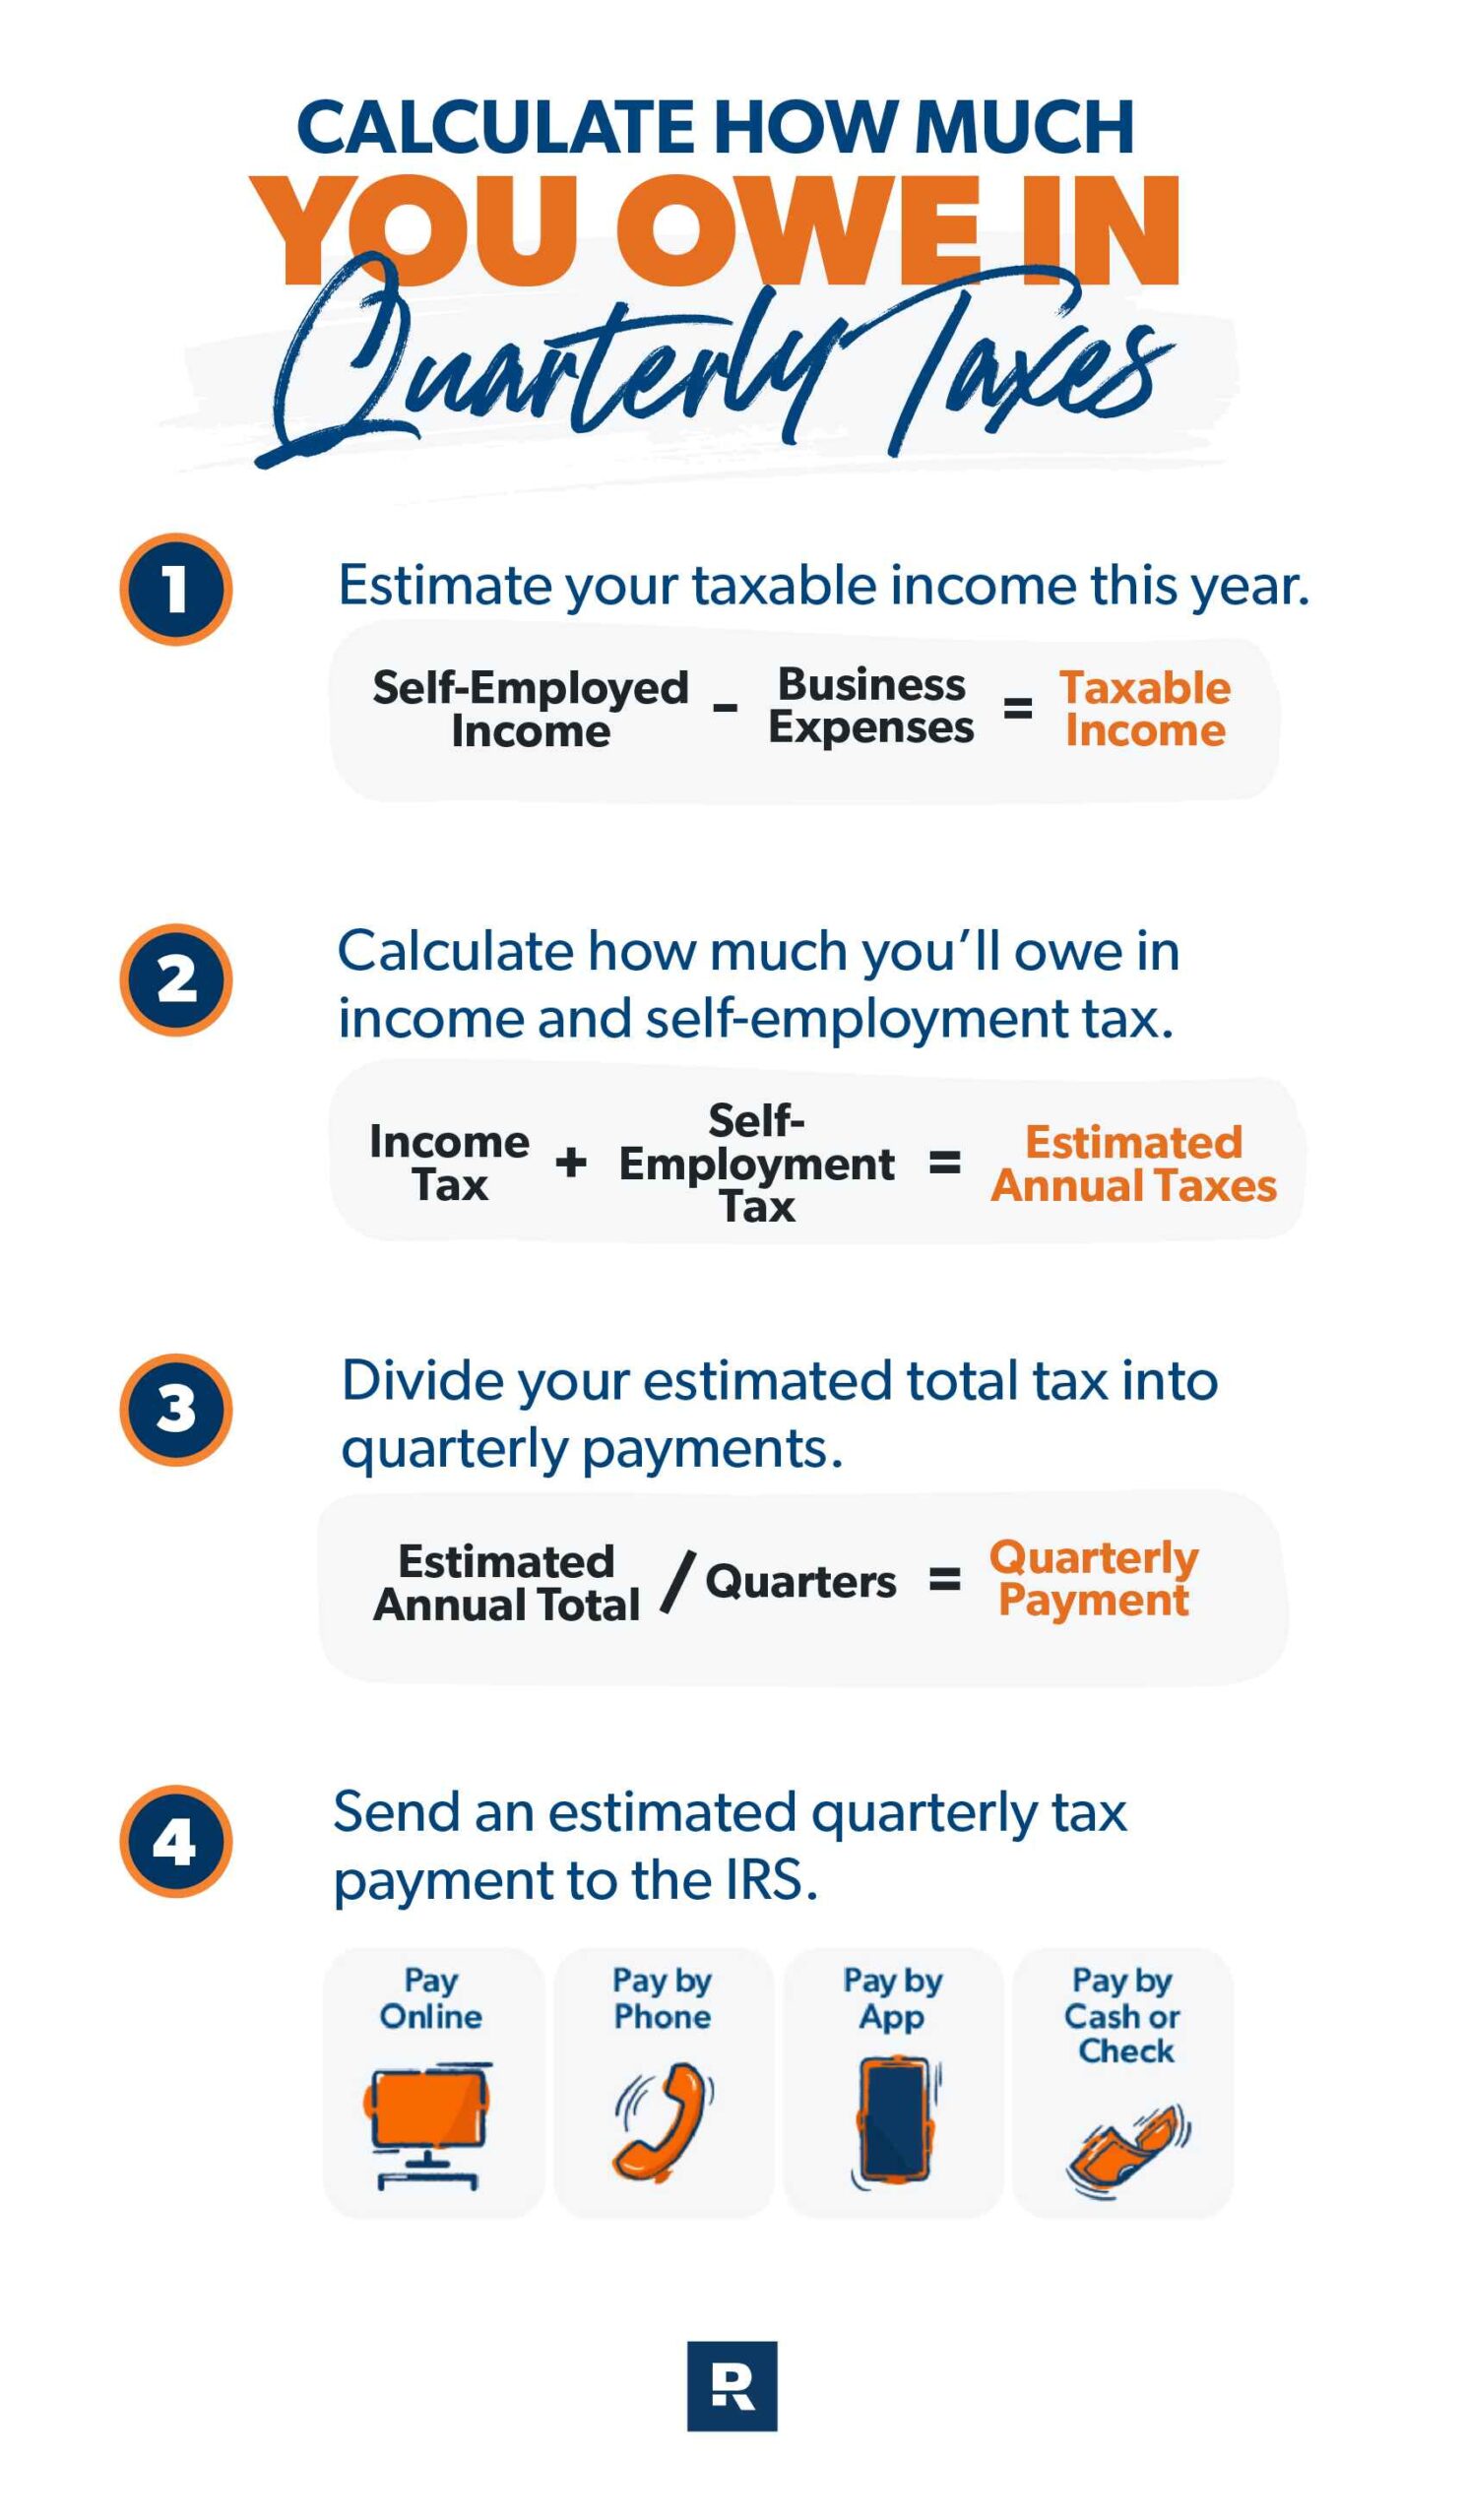
Determining how much to pay in quarterly taxes involves estimating your total taxable income for the year and then calculating the appropriate tax.
Step 1: Estimate Your Income
Begin by estimating your total income for the year. You’ll want to consider all income sources, including sales, services, investments, and any other revenue streams.
Step 2: Deduct Business Expenses
Next, deduct your business expenses from your gross income. This will give you your estimated taxable income, a crucial figure for calculating your tax payment.
Step 3: Determine Your Tax Liability
Using your estimated tax bracket, calculate how much tax you’ll owe based on your taxable income. For most startups operating as sole proprietorships, partnerships, or LLCs, the income is passed through to the owner’s personal tax return.
Step 4: Divide by Four
Once you’ve calculated your estimated tax liability, divide it by four to find out how much you should pay each quarter.
When Are Quarterly Taxes Due?
Understanding when your quarterly taxes are due is critical for staying compliant. For most businesses, the deadlines fall on the following dates:
- 1st Quarter: Due April 15
- 2nd Quarter: Due June 15
- 3rd Quarter: Due September 15
- 4th Quarter: Due January 15 of the next year
In certain years, deadlines may shift slightly due to holidays or weekends. It’s always advantageous to double-check with the IRS or a tax professional to ensure you’re on time.
Payment Methods for Quarterly Taxes
The IRS provides several options for making your quarterly tax payments:
-
IRS Direct Pay: This is the most straightforward option, enabling you to directly transfer funds from your bank account to the IRS without any fees.
-
Electronic Federal Tax Payment System (EFTPS): This free service requires prior registration but is particularly useful for businesses that make payments on a regular basis.
-
Credit or Debit Card: While you can pay your taxes using a credit or debit card, be aware that service fees apply.
-
Mail: You can also mail a check with Form 1040-ES for individuals or Form 1120-W for corporations. Note that this can take longer to process and may result in penalties if delays occur.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
Special Considerations for Startups
As a startup, there are unique factors to consider when it comes to quarterly taxes. Here are some key points to keep in mind:
1. Choosing Your Business Structure
Depending on how you set up your business—be it a sole proprietorship, partnership, S corporation, or LLC—your tax obligations and rates may vary significantly. It’s crucial to understand these differences or consult with a tax professional.
2. Startup Expenses
Startups often incur various expenses while getting off the ground. The IRS allows businesses to deduct specific startup costs, which can significantly reduce your taxable income. Keep thorough records of all expenses to maximize your deductions.
3. Changes in Revenue
Your revenue can change substantially in the early years, especially for startups. If you expect to earn significantly more or less than your initial estimate, you can adjust your quarterly payments accordingly. The IRS allows estimations to be updated throughout the year.
4. State and Local Taxes
Don’t forget about your state and local tax obligations. In addition to federal taxes, you may also be subject to state income taxes, sales taxes, and other local taxes. Understanding the requirements in your state is essential for compliance.
Tips for Managing Quarterly Taxes as a Startup
To simplify the process of managing quarterly taxes, consider the following tips:
-
Keep Detailed Financial Records: Maintain organized records of income, expenses, and receipts. This will make it easier to estimate your taxes while providing documentation if needed.
-
Engage a Tax Professional: Navigating tax regulations can be complex. Hiring a tax accountant or specialist can not only ease your burden but also provide insights into potential deductions, credits, and strategies that could save you money.
-
Use Accounting Software: Many modern accounting tools automate tax calculations and keep track of income and expenses, which can take a lot of guesswork out of quarterly payments.
-
Stay Updated on Tax Laws: Tax laws are constantly changing. Ensure you stay informed about any updates that might affect your tax obligations and overall financial strategy.
-
Plan Ahead: Make quarterly payments a part of your financial planning. Set aside a percentage of your income each month so you’re not faced with a hefty bill come payment time.
-
Review and Adjust Regularly: Your business’s financial situation can evolve, so it’s good practice to review your estimate quarterly. If your revenue increases or decreases significantly, adjust your payments accordingly.
Conclusion
Quarterly taxes may seem daunting, but knowing the essential elements can help demystify the process. For startups, understanding how to project income, manage payments, and stay compliant with tax laws is vital for financial health and sustainability.
Remember, you’re not alone in this. Relying on professional support and using the right tools can significantly alleviate the tax burden on your startup. By planning ahead, keeping accurate records, and remaining diligent about deadlines, you can focus more on building your business and less on tax complications.
By embracing these best practices, you ensure not just compliance but also a smoother financial operation, paving the way for growth and success in the exciting journey of entrepreneurship. Now that you’re equipped with the knowledge you need, it’s time to conquer those quarterly taxes and focus on what you do best—growing your startup!
If you have any specific preferences or adjustments you’d like, such as including different points or focusing on particular aspects, feel free to let me know!


