
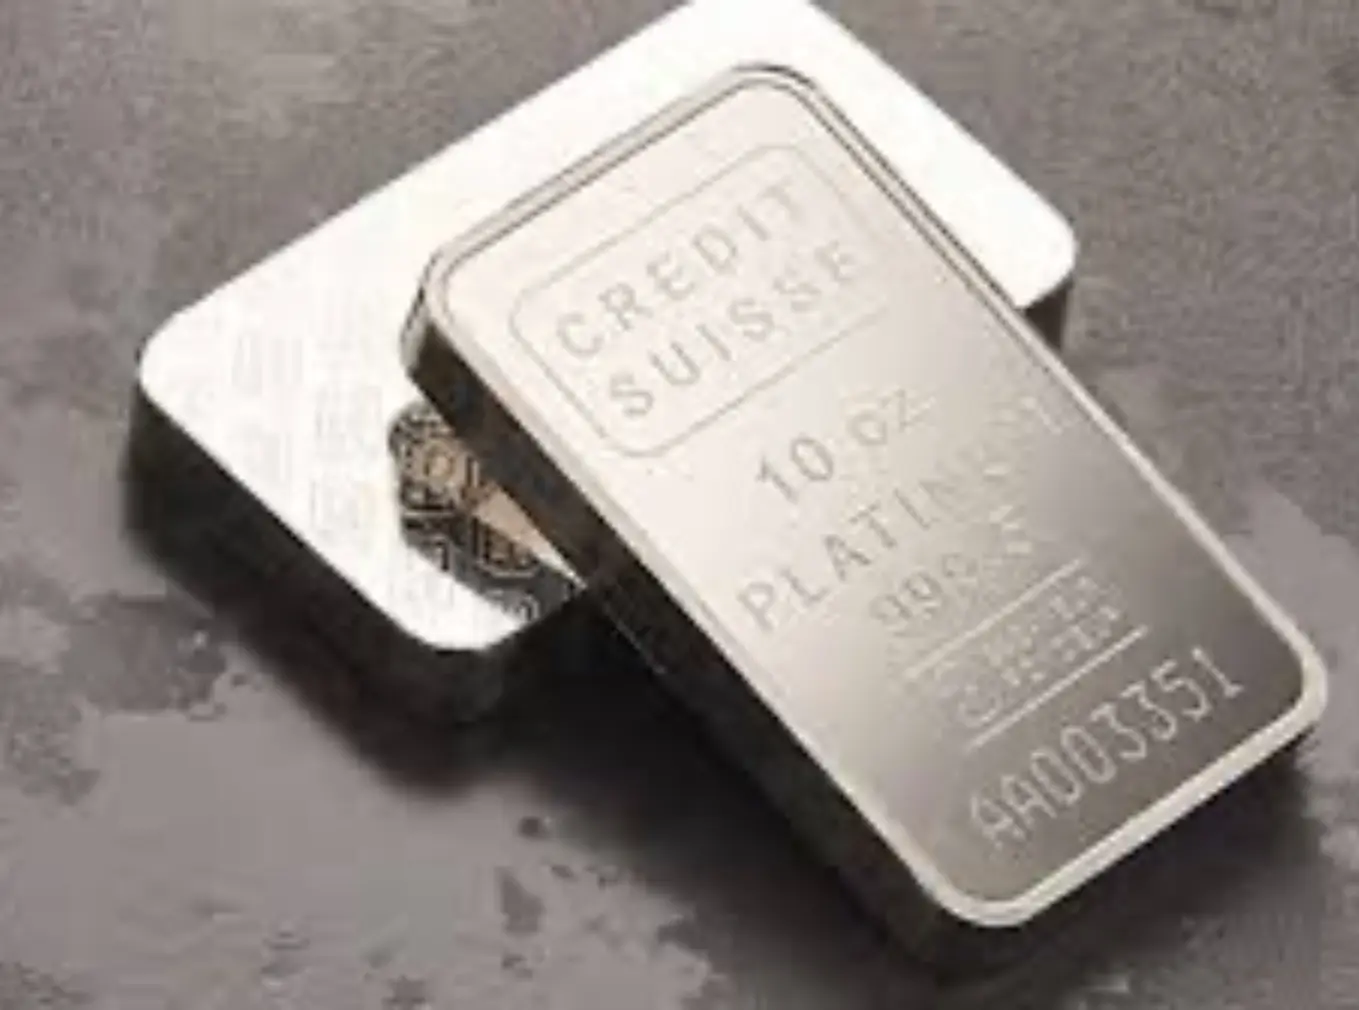
Discover how to invest in platinum with this comprehensive 2025 guide. Learn about market deficits, investment methods, and strategic opportunities in the white metal.
For years, platinum remained in gold’s shadow, confined to a seemingly endless trading range while gold soared on central bank purchases and safe-haven status. The white metal struggled to find momentum, but after a decade of stagnation, platinum is showing real signs of life with key resistance levels being seriously tested. The catalyst comes from fundamental supply-demand dynamics that present compelling opportunities for strategic investors.
Key Takeaways:
- Platinum faces its third consecutive annual deficit in 2025, with a projected 850,000-ounce shortfall driving price momentum
- Supply constraints from South African mines and limited recycling are creating structural market tightness
- Chinese jewelry demand is surging 42% in 2025 as consumers seek alternatives to expensive gold
- Investment options include physical platinum, ETFs, mining stocks, and futures contracts, each with distinct risk-return profiles
- Above-ground platinum stocks are falling to critically low levels of just three months of demand coverage
- Price forecasts suggest continued upward pressure with potential for sustained bull market conditions through 2029
The Platinum Market’s Structural Transformation
Platinum’s investment case has fundamentally changed, driven by supply-demand imbalances that appear both severe and persistent. The World Platinum Investment Council expects annual platinum deficits to average 727 koz from 2025 to 2029, representing 9% of average demand.
This represents a dramatic shift from the oversupplied conditions that suppressed platinum prices for much of the past decade. The current deficit cycle began in 2023 and has intensified, with 2024 recording a deficit of 995,000 ounces and 2025 projected at 850,000 ounces despite declining demand.
Supply-Side Constraints
South African mine supply continues declining due to operational challenges, capital underinvestment, and structural industry problems. Total platinum supply is expected to fall below 7 million ounces in 2025 which, barring COVID, will be the lowest level in the data series going back to 2013.
Mining industry restructuring following years of low prices has reduced production capacity and limited new investment. Companies spent 2024 restructuring assets and reducing capital expenditure, creating supply constraints that will persist even as prices recover.
Recycling supply challenges compound the supply shortage. Global recycled supply continues to decline, with recycling supply forecasts consistently undershooting actual performance from 2022 to 2024. Higher prices in 2025 should stimulate some recycling recovery, but supply is expected to remain well below historical peak levels.
Demand Evolution and Growth Areas
Chinese jewelry demand represents the most significant demand growth story. Chinese platinum jewelry fabrication is expected to grow 42% in 2025 to 585,000 ounces, as wholesalers promote platinum due to huge drops in gold jewelry sales.
Automotive demand stability provides a solid foundation despite electric vehicle growth. Internal combustion engine vehicles will require platinum-containing catalytic converters for longer than previously anticipated, particularly in hybrid applications that actually increase platinum usage per vehicle.
Emerging hydrogen economy applications show rapid growth from a small base. Hydrogen demand showed almost 50% year-on-year growth with substantial growth continuing into 2025, as government subsidies begin flowing and translating into real platinum demand.
Investment Methods and Strategic Approaches
Platinum investing offers multiple pathways, each suited to different risk tolerances, investment timeframes, and portfolio objectives.
Physical Platinum Investment
Direct ownership through platinum bars and coins provides the purest exposure to platinum price movements while eliminating counterparty risks. Physical platinum offers tangible asset ownership that functions independently of financial market stability.
Storage considerations include security, insurance, and liquidity factors. Professional storage services typically charge annual fees similar to gold storage (0.5-1.5%), while home storage eliminates ongoing costs but increases security risks.
Market liquidity for physical platinum can be more challenging than gold, with wider bid-ask spreads and fewer dealers. American Platinum Eagles and other recognized products offer better liquidity than generic bars or foreign coins.
Tax implications generally follow collectibles treatment for physical platinum, potentially resulting in higher capital gains rates than financial securities. However, specific treatment depends on holding periods and individual tax circumstances.
Platinum Exchange-Traded Funds (ETFs)
ETF advantages include ease of trading, professional storage management, and lower transaction costs compared to physical ownership. Major platinum ETFs track spot prices closely while offering stock market liquidity.
Cost structures typically involve annual expense ratios of 0.6-0.9%, higher than gold ETFs but lower than most actively managed funds. These fees cover platinum storage, insurance, and fund administration.
Liquidity benefits allow investors to buy and sell platinum exposure during regular trading hours without dealing with physical dealers or storage logistics. This flexibility particularly benefits tactical investors and those with smaller position sizes.
Counterparty considerations involve fund management risks and the possibility of premium/discount to net asset value during extreme market conditions. However, established ETFs typically maintain tight spreads to underlying platinum prices.
Platinum Mining Stocks
Leverage characteristics mean mining stocks often outperform platinum prices during bull markets but underperform during bear markets. Well-managed mining companies can amplify platinum price gains through operational leverage.
Company-specific risks include operational challenges, labor disputes, regulatory changes, and management quality issues that affect individual stocks regardless of platinum prices. Geographic concentration in South Africa adds political and operational risks.
Dividend potential from profitable mining operations provides income that physical platinum cannot generate. However, dividend payments depend on operational cash flows and capital allocation decisions that can vary significantly.
Major mining companies include Anglo American Platinum, Impala Platinum, Sibanye Stillwater, and others with significant platinum exposure. Each offers different risk-return profiles based on operational efficiency, asset quality, and financial management.
Futures and CFD Trading
Leverage opportunities through futures contracts and CFDs allow traders to control large platinum positions with relatively small capital requirements. This amplification works both ways, increasing both potential gains and losses.
Short-term trading applications suit active traders seeking to profit from platinum price volatility. However, these instruments require substantial market knowledge and risk management skills.
Margin requirements and daily settlement create cash flow considerations that differ from physical ownership or ETF investing. Traders must maintain adequate account balances and understand forced liquidation risks.
Professional execution typically works better than retail futures trading for most investors, as institutional access provides better execution and lower transaction costs.
Market Timing and Entry Strategies
Determining optimal entry timing requires analyzing both fundamental conditions and technical market indicators.
Current Market Conditions
Price momentum has been building through 2025, with platinum pushing past $1,450 per ounce in July before consolidating. Despite weakening demand through the first half of 2025, a structural deficit in the market still exists due to lack of supply to close the gap.
Above-ground inventory depletion creates increasingly tight market conditions. Above-ground stocks are expected to fall to barely three months of demand by the end of this year, an unsustainably low level leading to market tightness reflected in elevated lease rates.
Technical breakout potential exists as platinum tests long-term resistance levels that have contained prices for years. Successful breakouts often lead to sustained price advances as technical buying reinforces fundamental demand.
Strategic Entry Approaches
Dollar-cost averaging reduces timing risk by spreading purchases over extended periods. This approach works particularly well for physical platinum and ETF accumulation, smoothing out short-term price volatility.
Correction buying involves accumulating positions during temporary price declines within the broader uptrend. Fundamentally, current platinum price levels appear insufficient to attract enough metal into the market to ease tight market conditions.
Breakout confirmation strategies wait for clear technical signals before establishing positions. This approach may sacrifice early gains but reduces risk of false starts in volatile markets.
Allocation timing should consider portfolio rebalancing needs and risk management requirements. Most advisors recommend 2-5% platinum allocation within precious metals exposure, with higher allocations requiring careful risk assessment.
Risk Factors and Mitigation Strategies
Understanding platinum-specific risks helps investors make informed decisions and implement appropriate risk management measures.
Supply-Side Risk Factors
South African operational risks include labor disputes, power supply issues, and political instability that can disrupt mine production. These risks are partially offset by global supply diversification but remain significant given South Africa’s dominant market position.
Recycling supply volatility depends on economic incentives and collection infrastructure that can change rapidly based on price levels. Higher PGM prices in 2025 should stimulate supply growth, but platinum automotive recycling supply is expected to remain below peak levels reported in 2021.
New mine development faces long lead times and substantial capital requirements that limit supply responsiveness to price signals. This characteristic supports sustained price cycles but also creates vulnerability to demand shocks.
Demand-Side Considerations
Automotive industry transition toward electric vehicles represents the primary long-term demand risk. However, slower battery electric vehicle growth and higher-for-longer internal combustion engine vehicle levels are more widely appreciated, extending platinum’s automotive relevance.
Industrial demand variability can create short-term volatility based on manufacturing cycles and capacity expansion patterns. Glass production demand, in particular, can fluctuate significantly based on technology industry conditions.
Investment demand cyclicality affects prices during periods of risk-on or risk-off sentiment in financial markets. However, structural supply deficits provide fundamental support independent of investment flows.
Portfolio Integration Strategies
Correlation management requires understanding platinum’s relationship with other precious metals, industrial commodities, and financial assets. Platinum often shows different correlation patterns than gold during various market cycles.
Position sizing should reflect platinum’s higher volatility compared to gold and its industrial demand components. Most advisors recommend smaller initial positions with potential for expansion based on market development.
Diversification within platinum exposure might include combinations of physical holdings, ETF positions, and selected mining stock exposure to balance risk and return characteristics.
Future Outlook and Long-Term Considerations
Professional analysis suggests platinum’s supply-demand fundamentals support sustained price appreciation beyond typical commodity cycles.
Structural Demand Trends
Hydrogen economy development represents significant long-term demand growth potential. Platinum demand growth from hydrogen end markets almost offsets declining autocatalyst demand, leaving platinum markets in consecutive deficits of around 430 koz on average between 2025 to 2028.
Medical and industrial applications continue expanding as platinum’s unique properties find new uses in healthcare devices, electronics, and chemical processes. These applications typically show strong price inelasticity, providing demand stability.
Jewelry market evolution may see continued growth as platinum’s discount to gold attracts consumers seeking precious metal alternatives. Chinese market development particularly offers substantial growth potential.
Supply Outlook Challenges
Mining industry capital constraints suggest limited new supply additions even if prices rise substantially. Years of underinvestment and operational challenges require time to reverse, supporting extended supply deficits.
Recycling limitations mean secondary supply cannot fully offset declining mine production. Recycling rates depend on economic incentives and infrastructure that respond slowly to price changes.
Geopolitical concentration in South African supply creates ongoing vulnerability to political and operational disruptions that could further constrain supply availability.
Frequently Asked Questions
How much platinum should I include in my investment portfolio? Most financial advisors recommend 2-5% allocation to platinum within a diversified precious metals position representing 5-15% of total portfolio value. Higher allocations require careful risk assessment given platinum’s volatility.
Is physical platinum or platinum ETFs better for most investors? Platinum ETFs offer greater convenience, lower transaction costs, and easier liquidity for most investors. Physical platinum makes sense for larger positions, long-term holders, or those seeking maximum security from counterparty risks.
What drives platinum prices differently from gold? Platinum’s industrial demand (especially automotive) creates different price dynamics than gold’s monetary and safe-haven characteristics. Supply concentration in South Africa also affects platinum more than gold’s geographically diverse production.
When is the best time to buy platinum? Current supply deficit conditions provide fundamental support, but dollar-cost averaging reduces timing risk. Market corrections within the broader uptrend may offer better entry opportunities for tactical investors.
How do platinum mining stocks compare to physical platinum? Mining stocks offer leverage to platinum prices and potential dividend income but add company-specific operational risks. They typically outperform during platinum bull markets but underperform during bear markets or operational difficulties.
What are the main risks of platinum investing? Primary risks include supply disruption in South Africa, automotive industry transition to electric vehicles, industrial demand volatility, and higher price volatility compared to gold. Diversification and appropriate position sizing help manage these risks.
Conclusion: Platinum’s Compelling Investment Case
The question of whether to invest in platinum in 2025 appears increasingly compelling based on fundamental supply-demand dynamics that have shifted dramatically in the metal’s favor. The convergence of structural supply deficits, above-ground inventory depletion, and emerging demand growth creates conditions that historically have supported sustained precious metals appreciation.
From a supply perspective, platinum faces constraints that appear both severe and persistent. South African mine supply continues declining due to operational challenges and underinvestment, while recycling supply remains well below historical levels despite higher prices. The structural nature of these constraints suggests they will persist even as prices rise.
Demand developments show encouraging diversification beyond traditional automotive applications. Chinese jewelry demand growth, hydrogen economy development, and continued industrial applications provide multiple growth drivers that reduce dependence on any single sector.
Investment implementation should emphasize strategic positioning rather than tactical timing for most investors. The various investment methods each offer distinct advantages suited to different needs: ETFs for convenience and liquidity, physical platinum for security and direct exposure, mining stocks for leverage and income potential.
Risk management remains crucial despite favorable fundamental conditions. Platinum’s industrial demand components and supply concentration create volatility that requires careful portfolio integration. Appropriate position sizing, diversification across investment methods, and systematic accumulation approaches typically produce better outcomes than concentrated tactical positions.
Current market conditions suggest the early stages of what could be a sustained bull market based on structural rather than cyclical factors. While short-term volatility is inevitable, the combination of supply constraints and demand growth provides fundamental support for continued price appreciation.
My assessment for most investors is that platinum merits strategic allocation at current levels, implemented through cost-effective methods and sized appropriately within precious metals exposure. The white metal’s transformation from oversupplied commodity to structurally deficit market represents a significant investment opportunity for those seeking portfolio diversification and commodity exposure.
Looking forward, platinum’s supply-demand fundamentals appear likely to remain supportive through the end of the decade. While no investment carries guarantees, the combination of severe supply constraints and emerging demand growth creates conditions that favor patient, strategic investors willing to accept the volatility inherent in commodity investing.
Disclaimer: The information contained in this article is provided for educational and informational purposes only and does not constitute financial, investment, or other advice. Before making any investment decisions, readers should consult a qualified financial advisor. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com is not responsible for any losses resulting from the use of the information provided.


