
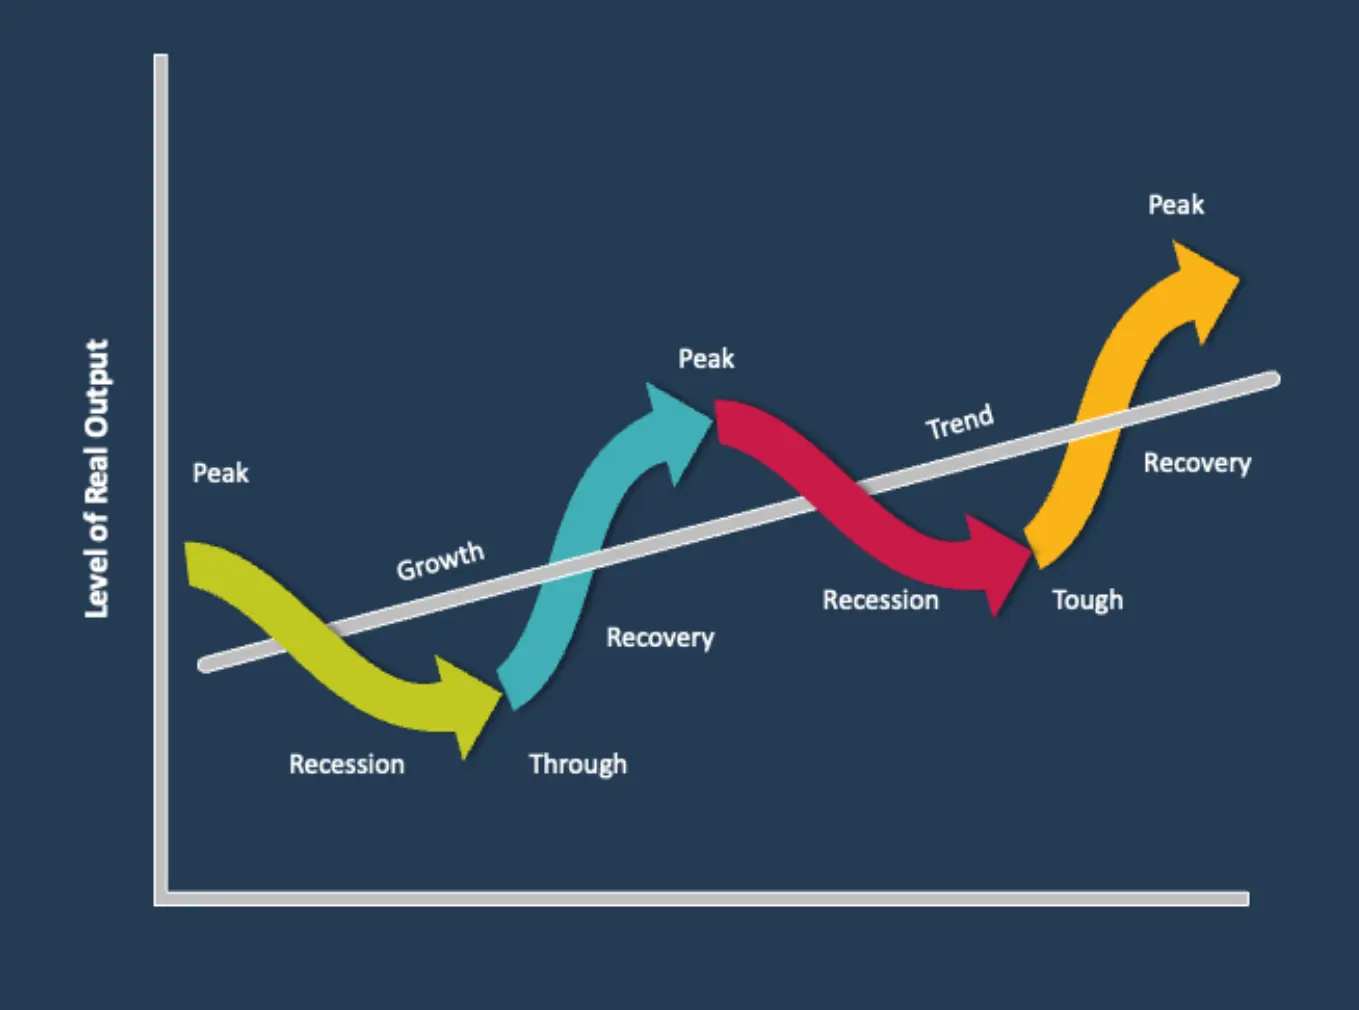
History doesn’t repeat itself exactly, but economic patterns often rhyme. The 1970s were marked by high inflation, energy shocks, rising interest rates, and volatile markets. Fast-forward to the 2020s, and many of the same forces—stagflation fears, geopolitical tension, and monetary tightening—are back in play.
For U.S. investors, understanding how to position portfolios for this “modern 1970s” scenario is essential to preserving real wealth and capturing new opportunities.
Key Takeaways
- Inflation may stabilize above the Fed’s 2% target, echoing the 1970s’ persistent price pressures.
- Energy and commodity cycles are resurging, driven by underinvestment and geopolitical tension.
- Equity returns could stay modest, while real assets and Treasuries regain importance.
- The Fed’s credibility and fiscal deficits will shape the next economic decade.
- A diversified mix of hard assets, quality stocks, and short-duration bonds offers resilience.
Parallels Between the 1970s and Today
In both decades, inflation followed a long period of monetary expansion. In the early 1970s, easy credit and oil shocks drove consumer prices up more than 10% annually. Today, after the post-COVID stimulus surge, inflation peaked above 9% in 2022, cooling to around 2.5% in 2025 but remaining sticky.
Energy shocks then came from OPEC; today, they arise from supply constraints, the Russia-Ukraine conflict, and green-transition costs. Fiscal deficits above 6% of GDP mirror 1970s government overspending.
The difference: central banks now have better tools, stronger communication, and a more flexible labor market.
What Investors Can Learn from the 1970s
- Nominal growth hides real losses. Even if wages rise, inflation erodes purchasing power.
- Commodities outperform equities during stagflation. In the 1970s, gold rose 1,400%.
- Shorter bond maturities outperform long bonds when rates are volatile.
- Diversification beats timing. The investors who maintained broad exposure preserved capital better than those who tried to call turning points.
Stocks: Expect Lower Multiples
During the 1970s, the S&P 500’s price-to-earnings ratio fell from 19x to 7x. Today, valuations remain elevated around 21x forward earnings—vulnerable if inflation expectations rise again.
Companies with pricing power—especially in energy, healthcare, and infrastructure—tend to perform better in such periods. Firms that rely on cheap credit, such as growth tech, are more exposed.
“Inflation is taxation without legislation.” — Milton Friedman
Investors can mitigate this by owning dividend-paying stocks and value-oriented ETFs, such as the Vanguard Value ETF (VTV) or Schwab U.S. Dividend Equity ETF (SCHD), which prioritize cash flow over speculation.
Bonds: Back in the Game
The 1970s were disastrous for long-term bondholders. But 2025 is different: yields above 4.5–5% provide a real buffer, especially as inflation expectations stabilize.
- Short-duration Treasuries (2–5 years) offer yield with low price risk.
- TIPS (Treasury Inflation-Protected Securities) hedge against inflation spikes.
- Series I Savings Bonds remain attractive for long-term inflation protection.
Investors should avoid excessive exposure to long bonds until the Fed’s next rate cycle is clear.
Commodities and Real Assets
Energy scarcity and supply bottlenecks resemble the early 1970s oil crises. The International Energy Agency (IEA)notes that fossil-fuel underinvestment since 2015 may create persistent price floors.
Gold and industrial metals (copper, lithium) continue to serve as inflation hedges. A 5–10% portfolio allocation to commodities or commodity ETFs can preserve purchasing power.
Real estate, though sensitive to rates, still acts as a long-term inflation shield—particularly REITs focused on logistics and infrastructure.
The Dollar and Global Balances
In the 1970s, the dollar weakened sharply after the end of the gold standard. Today, U.S. deficits and de-dollarization efforts by emerging markets pose a similar long-term challenge.
However, near-term, the dollar remains strong due to higher U.S. yields and global demand for safe assets. Long-term investors can hedge currency risk through exposure to gold, foreign equities, or global bond funds.
How to React as an Investor in 2025
1. Rebalance portfolios annually. Don’t rely on high-growth stocks alone.
2. Keep 30–40% in income-generating assets. Bonds and dividend stocks stabilize returns.
3. Hold 10% in inflation hedges. Commodities, gold, and TIPS mitigate shocks.
4. Favor cash-flow-positive companies. Avoid firms dependent on refinancing.
5. Stay liquid. Cash and short-term Treasuries provide flexibility if volatility returns.
Example: Modern 1970s Portfolio Allocation
| Asset Class | Allocation | Expected Return | Role |
|---|---|---|---|
| U.S. Equities (Value/Dividend) | 40% | 6–8% | Income and growth |
| Short-Term Treasuries | 25% | 4.5–5% | Stability |
| Commodities & Gold | 10% | 5–7% | Inflation hedge |
| Real Estate / REITs | 10% | 6–8% | Real asset exposure |
| Cash & Money Market Funds | 15% | 4–5% | Liquidity and safety |
This structure balances yield, protection, and optionality in uncertain macro conditions.
Lessons from the Past
The 1970s taught that inflation and policy mistakes can destroy savings. Today’s challenge is subtler but similar: sustained deficits and resource constraints will keep real yields modest and volatility high.
Investors who ignore these parallels risk overexposure to assets that depend on low inflation and cheap credit.
Those who diversify—across time horizons and asset types—will adapt best to this “slow burn” cycle.
FAQ
Is inflation really back for good?
Not at 2022 levels, but likely above 2% for several years due to structural supply limits and fiscal policy.
Should I buy gold now?
Yes, as part of a diversified portfolio. Gold protects purchasing power when real yields fall.
Will stocks crash like in the 1970s?
Unlikely. Corporate balance sheets are stronger, and monetary policy is more flexible, but valuations may compress.
Are bonds safe again?
Yes, especially short-term Treasuries offering 5% yields and limited duration risk.
Conclusion
The echoes of the 1970s are clear: inflationary pressure, high public debt, and shifting global power balances. Yet today’s investor has better tools—transparent markets, ETFs, and access to inflation-protected assets.
The winners in this cycle will be those who adapt, rebalance, and protect their purchasing power. The 1970s punished complacency; 2025 will reward discipline.
Related reading on TheMarketCapitalist.com
- How Inflation Impacts U.S. Treasury Returns in 2025
- Commodities vs. Stocks: Where to Invest in a Reflationary World
- Building a 2025 Portfolio for Inflation and Growth
External references:
- Federal Reserve – Economic Research & Data
- International Energy Agency – World Energy Outlook
- U.S. Bureau of Labor Statistics – CPI Data
Disclaimer:
The information contained in this article is provided for educational and informational purposes only and does not constitute financial, investment, or other advice. Before making any investment decisions, readers should consult a qualified financial advisor. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com is not responsible for any losses resulting from the use of the information provided.


