
When stock prices fall, most investors panic. But the most successful U.S. investors—from Warren Buffett to Howard Marks—agree on one principle: the best opportunities appear when fear dominates the market.
This article updates the original Money.it concept and adapts it for the U.S. market in December 2025, using the latest valuations, sentiment indicators, and macro trends. The strategy explained here is intentionally simple, data-driven, and ideal for long-term investors who want to exploit market downturns without gambling.
Falling prices aren’t a threat. They’re an opportunity—if you know what to buy and why.
Key Insights
- The strategy focuses on buying high-quality U.S. stocks when their valuations temporarily fall, not on predicting market bottoms.
- In 2025, market drawdowns of 8–15% have repeatedly offered strong entry points.
- Indicators like the Equity Risk Premium (ERP), Forward P/E, and VIX help identify attractive buying moments.
- Mega-cap tech still dominates, but opportunities increasingly emerge in financials, energy, and industrials.
- Dollar-cost averaging during corrections remains one of the most effective long-term strategies in U.S. markets.
Why U.S. Stocks Are Attractive During Pullbacks
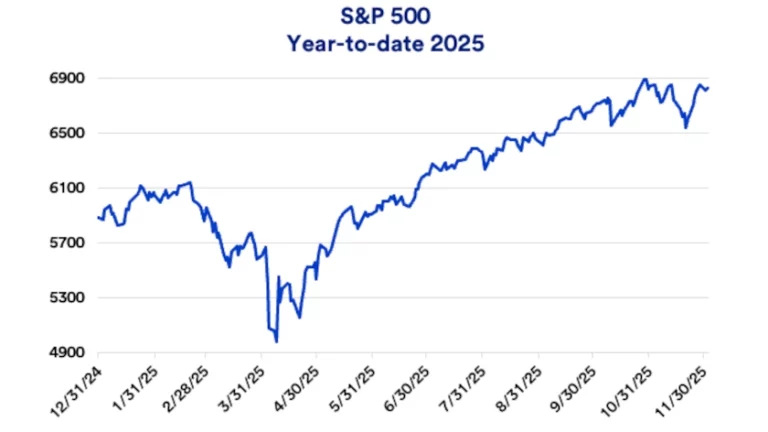
Historically, every significant U.S. market decline has led to higher long-term returns. Even after the 2022 inflation shock, the S&P 500 delivered +24% in 2023, +17% in 2024, and approximately +7% YTD in 2025 despite several rate hikes.
Why?
- Corporate earnings remain strong.
- The U.S. economy continues to outgrow major global economies.
- Buybacks support EPS growth (as covered in Buybacks Explained: Why U.S. Companies Repurchase Their Own Shares in 2025).
- Mega-cap tech maintains high profitability—even with elevated valuations.
Corrections are normal. In 2025, the S&P 500 saw three dips between 8–12%. Each quickly recovered as liquidity conditions stabilized and earnings beat expectations.
The Simple Strategy: Buy Quality When Valuations Compress
This approach uses valuation compression as the signal—not market predictions.
You buy when a strong company temporarily trades at a discount to its historical average.
What to Look For
- Forward P/E Ratio Below the 10-Year AverageIf a company normally trades at 24× earnings but drops to 18–20× during a pullback, the risk-reward improves sharply.(Explained in depth in Understanding the P/E Ratio: How U.S. Investors Use Price-to-Earnings to Value Stocks in 2025.)
- Stable or Rising Earnings ForecastsIn December 2025, S&P 500 earnings growth is projected at +8% for 2026—strong enough to justify buying dips.
- Low or Normalizing Implied VolatilityWhen the VIX rises above 22–24, panic tends to peak.Historically, buying during VIX spikes has delivered above-average 12-month returns.
- Equity Risk Premium (ERP)As discussed in ERP Explained: The U.S. Equity Risk Premium and What It Means for Valuations (2025), the current ERP sits around 4.2%, signaling moderately expensive markets.When ERP rises above 5% during corrections, U.S. stocks become compelling buys.
Why the Strategy Works
When share prices fall but fundamentals remain strong, three forces create long-term returns:
- Valuation mean reversion
- Earnings growth
- Share buybacks reducing float
Morningstar’s December 2025 U.S. Equity Outlook confirms that companies with strong balance sheets and consistent earnings tend to outperform sharply following periods of valuation compression.
When to Apply This Strategy in 2025
Based on up-to-date December 2025 data, recent pullbacks offered attractive entry opportunities when:
- SPX Forward P/E dropped from 20.4× to 18.1×
- VIX surged past 23
- 10-year Treasury yields spiked above 4.7%, pushing stocks lower
- Earnings revisions remained positive
Each scenario provided a favorable setup for long-term buyers—not market timers.
Example Application (2025 Edition)
Case Study: Microsoft (MSFT)
- Historical forward P/E: ~28×
- Pullback valuation (June 2025 dip): 23×
- Earnings still growing 11% YoY
- Strong buyback program
- Beta: 1.05 (moderate risk as explained in Understanding the Beta Coefficient)
Result: MSFT gained +14% within four months after the valuation compression.
Case Study: JPMorgan (JPM)
- Forward P/E dropped to 9.8× during geopolitical volatility
- CET1 ratios remained strong across major banks (as covered in CET1 Ratio Explained)
- Rising net interest income in late 2025
Result: JPM rebounded +17% from the lows.
How to Actually Execute This Strategy
Step 1 — Build a Watchlist of High-Quality U.S. Stocks
Industries with strong fundamentals in Dec 2025:
- Tech (AI, cloud, chips)
- Industrials (aerospace, automation)
- Energy (refiners, LNG exporters)
- Financials (major banks, insurance)
Step 2 — Track Valuations Weekly
Look at:
- Forward P/E
- Price-to-free cash flow
- Earnings revisions
- Discount to 5-year or 10-year averages
Step 3 — Buy in Tranches
Rather than going all in, buy gradually during corrections:
- 25% on first drop
- 25% on further declines
- 25% on volatility spikes
- 25% when valuation recovers
Step 4 — Hold for 12–36 Months
Historically, valuation-compression strategies outperform when held for at least one year.
Updated 2025 Market Conditions Supporting This Strategy
- Inflation: Stabilized at 2.4%
- Fed Policy Rate: ~5.0% with no cuts expected until mid-2026
- 10-year Treasury Yield: ~4.55% (December 2025)
- Corporate Earnings: Forecast +8% for 2026
- U.S. GDP Growth: ~1.9% for 2025
- Buyback Volume: $960 billion estimated for 2025
- Market Volatility: VIX 15–23 range typically marks compression opportunities
Conclusion
Profiting when stocks fall isn’t magic—it’s discipline.
When fear rises and valuations compress, high-quality U.S. stocks become long-term bargains.
As Warren Buffett famously says:
“Be fearful when others are greedy, and greedy when others are fearful.”
The December 2025 U.S. market continues to offer exactly these opportunities—if you know how to identify them.
Disclaimer:
The information in this article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com assumes no responsibility for losses resulting from use of this information.


