
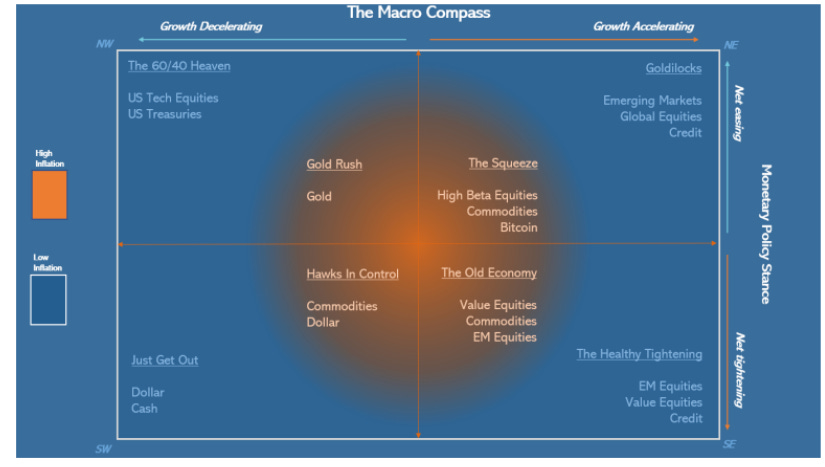
Bonds remain a cornerstone of diversified portfolios in 2026, offering income, stability, and inflation protection amid equity volatility—but getting them right requires understanding duration, credit risk, and yield curves like a seasoned navigator. Whether you’re building a ladder for retirement or hedging stocks, this compass demystifies Treasuries, corporates, municipals, and more to help U.S. investors avoid common pitfalls.
Key Takeaways
- Duration measures sensitivity: A 5-year bond drops ~4% in price if rates rise 1%.
- Investment-grade corporates yield 4.5-5.5%, balancing safety and return over Treasuries.
- Laddering spreads maturity risk while capturing reinvestment opportunities.
- Municipal bonds offer tax-free income ideal for high earners (effective yield ~6% in top brackets).
- Inflation-linked TIPS protect purchasing power in uncertain times.
- Always match bonds to horizon and risk tolerance—short-term for liquidity, long for yield.
Why Bonds Matter More Than Ever in 2026
With S&P 500 P/E ratios stretched and geopolitical tensions simmering, bonds provide ballast. The Bloomberg Aggregate Bond Index returned 5.2% in 2025, rebounding from 2022’s drubbing. Yet, yields hover at 4.2% (10-year Treasury), tempting income seekers while rate-cut hopes linger.
Bonds excel at:
- Predictable cash flows for expenses
- Diversification (low correlation to stocks)
- Capital preservation in downturns
But beware: They’re not “risk-free.” Rising rates crush prices; credit defaults lurk in junk territory.
Bond Basics: Yield, Price, and Maturity
Yield to Maturity (YTM) is your total return if held to end—interest + price change. A bond at par ($1,000) paying 5% coupon yields 5%. Buy at discount ($950), YTM exceeds coupon.
Duration (in years) approximates price drop per 1% rate rise:
- Short (<3 years): Low volatility, ~2% drop
- Intermediate (3-10): Balanced, ~5-7% drop
- Long (>10): High yield but ~12%+ drop
Callable bonds let issuers refinance early, capping upside.
Types of Bonds for U.S. Investors
U.S. Treasuries: Ultimate Safety
Direct from TreasuryDirect.gov:
- T-Bills (<1 year): ~4.8%
- Notes (2-10 years): 4.2-4.8%
- TIPS: Inflation-adjusted principal
Zero credit risk, state-tax exempt.
Corporate Bonds: Higher Yield, Modest Risk
Investment Grade (BBB+): Apple, JPMorgan—yields 4.8-5.5%.
High Yield (Junk): Riskier firms, 7-10% yields but 3-5% default odds.
ETFs like Vanguard Intermediate Corporate (VCIT) simplify access.
Municipal Bonds: Tax Magic
State/local debt, federally tax-free. A 4% muni equals 6.5% taxable for 37% bracket earners.
General Obligation vs. Revenue bonds—former safer.
Agency and MBS: Quasi-Government
Fannie Mae, Ginnie Mae—yields 0.3-0.5% over Treasuries.
Yield Curve Strategies for 2026
The curve is mildly inverted: Short rates 4.75%, long 4.2%. Bull flattener expected if Fed cuts.
Barbell: Shorts + longs for yield/liquidity.
Bullet: Concentrate at target maturity.
Ladder: Stagger 1-10 years, roll proceeds.
Example $100K ladder:
| Maturity | Amount | Yield |
|---|---|---|
| 1-Year | $10K | 4.9% |
| 3-Year | $20K | 4.7% |
| 5-Year | $30K | 4.6% |
| 7-Year | $20K | 4.4% |
| 10-Year | $20K | 4.2% |
Avg yield ~4.6%, $1K liquidity yearly.
Link: Treasury Ladder Builder.
Credit Risk and Ratings Demystified
Moody’s/S&P ratings:
- AAA/AA: Near-Treasury safety
- A/BBB: IG, 0.2-0.5% annual defaults
- BB/B: HY, 2-5% defaults
Diversify: No more than 5% per issuer.
“Credit spreads widen in recessions—buy quality, hold to maturity.”
Inflation and Interest Rate Risks
TIPS adjust principal by CPI: 1.6% real yield + inflation.
I Bonds: 4.28% through April 2026, inflation-linked.
Rising rates? Shorten duration. Falling? Extend.
Tax-Smart Bond Allocation
- Taxable account: Munis, TIPS
- IRA/401(k): Corporates, Treasuries
- Roth: High-yield junk
Minimize AMT on privates.
FINRA: Bond Basics.
Common Pitfalls New Investors Face
- Chasing yield into junk without diversification
- Ignoring duration in rising-rate scares
- Selling in panic during temporary dips
- Overlooking fees in bond funds (aim <0.2%)
- Forgetting callable risk in high-coupon bonds
Building Your Bond Portfolio Step-by-Step
- Define goals: Income? Preservation? Horizon?
- Assess risk: Conservative? 80% short IG.
- Allocate: 40-60% bonds in 60/40.
- Select vehicles: ETFs (BND), direct, ladders.
- Rebalance yearly: Trim winners, extend duration.
- Monitor: Fed meetings, inflation prints.
Sample $250K conservative bond portfolio:
| Category | Allocation | ETF/Example | Yield |
|---|---|---|---|
| Short Treasury | 30% | SHY | 4.7% |
| Intermediate Corp | 25% | VCIT | 5.0% |
| Munis | 20% | VTEB | 4.0% (tax-eq 5.8%) |
| TIPS | 15% | TIP | 4.5% |
| IG Credit | 10% | LQD | 5.3% |
Expected yield: 4.7%, duration 4.5 years.
2026 Outlook: Opportunities Ahead
Fed cuts to 3.5-4% by year-end steepen curve, favoring intermediates. Corporate spreads tight but recession-proofing via munis/TIPS wise.
We favor barbell ladders for flexibility. Action steps:
- Audit current bonds vs. curve.
- Build $50K ladder via TreasuryDirect.
- Add 20% munis if taxable.
- Stress-test with Portfolio Visualizer.
- Review with advisor quarterly.
Master this compass, and bonds become your portfolio’s steady anchor.
Disclaimer: The information contained in this article is provided for educational and informational purposes only and does not constitute financial, investment, or other advice. Before making any investment decisions, readers should consult a qualified financial advisor. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com is not responsible for any losses resulting from the use of the information provided.


