
U.S. Treasury yields rise amid tightening spreads signaling risks. Analyze $37T debt, Fed-Fiscal tensions, and hedges for investors in a less rosy 2026 bond market outlook. (148 characters)
U.S. Treasury spreads (10Y-2Y) narrowed to 0.25% in late 2025, mirroring BTP optimism, but underlying fragilities—ballooning deficits, inflation persistence, and policy clashes—portend volatility. With national debt surpassing $37 trillion and interest payments rivaling defense spending, the bond market’s “safe haven” aura frays. Adapted from European debt analyses, this guide focuses on U.S. realities under President Trump’s fiscal expansion, offering strategies to navigate yield spikes, curve steepening, and opportunity in munis and corporates.
Key Insights
- Yield curve signals: Inversion end hides term premia expansion risks.
- $2.5T annual deficits pressure 10Y to 4.8-5.2%.
- Fed independence vs. fiscal dominance: QT pause debates.
- Inflation-structural drivers undermining rate cut bets.
- Hedging tools: TIPS, short Treasuries, munis for tax advantages.
- Corporate bond sweet spot: IG high-yield spreads at 120bps.
Treasury Yield Surge Drivers
The 10Y Treasury yield climbed from 3.8% to 4.3% post-election, driven by growth optimism and supply floods. Annual issuance hits $2.5T net, outpacing $1T demand from Fed runoff slowdown. European spread contractions mask similar yield risks; U.S. dollar reserve status buys time but not immunity.
Trump policies: TCJA permanence adds $1.5T deficits; tariffs inflate import costs 0.5% CPI. Pros: Steepener trades profit (2Y/10Y +100bps); cons: Volatility spikes VXY to 120. Data: CBO projects debt service $1.2T by 2028.
Takeaway: Position for 10Y >4.75% via TNX calls.
Fiscal Dominance and Fed Constraints
Debt at 135% GDP by 2026 forces Fed accommodation; QT at $25B/month may halt if auctions tail. Italian debt fragility parallels U.S. primary deficits averaging 4% GDP. IRS withholding taxes fund only 70% spending.
Example: 2023 auction concessions cost 20bps extra. Risks: Failed auctions trigger intervention. Case study: UK 2022 gilt crisis—yields +100bps in days.
| Metric | 2025 | 2026E |
|---|---|---|
| Debt Stock | $36T | $39T |
| Interest Expense | $900B | $1.1T |
| 10Y Yield Avg | 4.0% | 4.7% |
External: TreasuryDirect Debt Data.
Inflation’s Sticky Grip on Yields
Core PCE at 2.7% resists cuts; services ex-housing +4%. Tariffs, wages (4.2% growth), energy passthrough sustain premia. BTP-like warnings: Markets price permanence.
Investor hedge: TIPS breakeven inflation 2.4%—buy if >2.2%.
Curve Dynamics: Steepening Ahead
Post-inversion, curve bull-flattens then steepens on growth. 2S10 spread targets +80bps. Strategies favor barbell: Short 5Y, long 30Y.
Pros: Banks’ NIM expand 20bps; cons: Duration hits mortgages.
Link: Yield Curve Strategies.
Muni Bonds: Tax Haven Opportunity
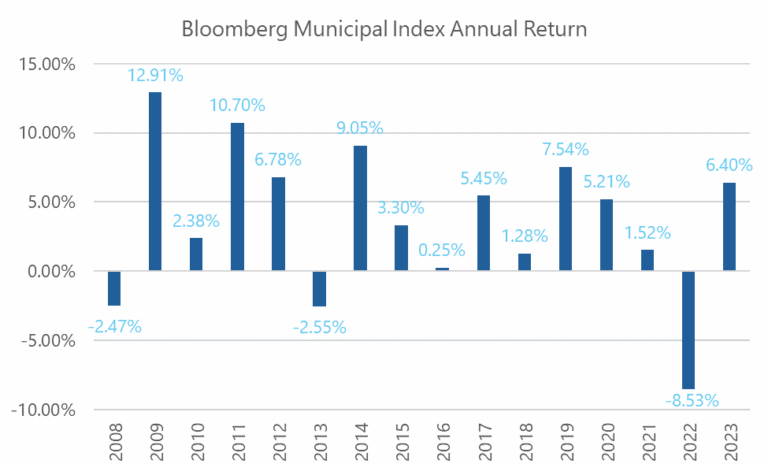
Munis yield 3.5% (tax equiv 5.8% for 37% bracket), spreads tight at 70bps over Treasuries. Infrastructure boom via IIJA funds $500B issuance.
U.S. focus: Blue-state credits stable; avoid IL/NY pension risks. Takeaway: VTEB ETF for liquidity.
“Spread drop hides yield rises, debt highs, EU imbalances.” Core caution.
Corporate Bonds: IG vs HY Divergence
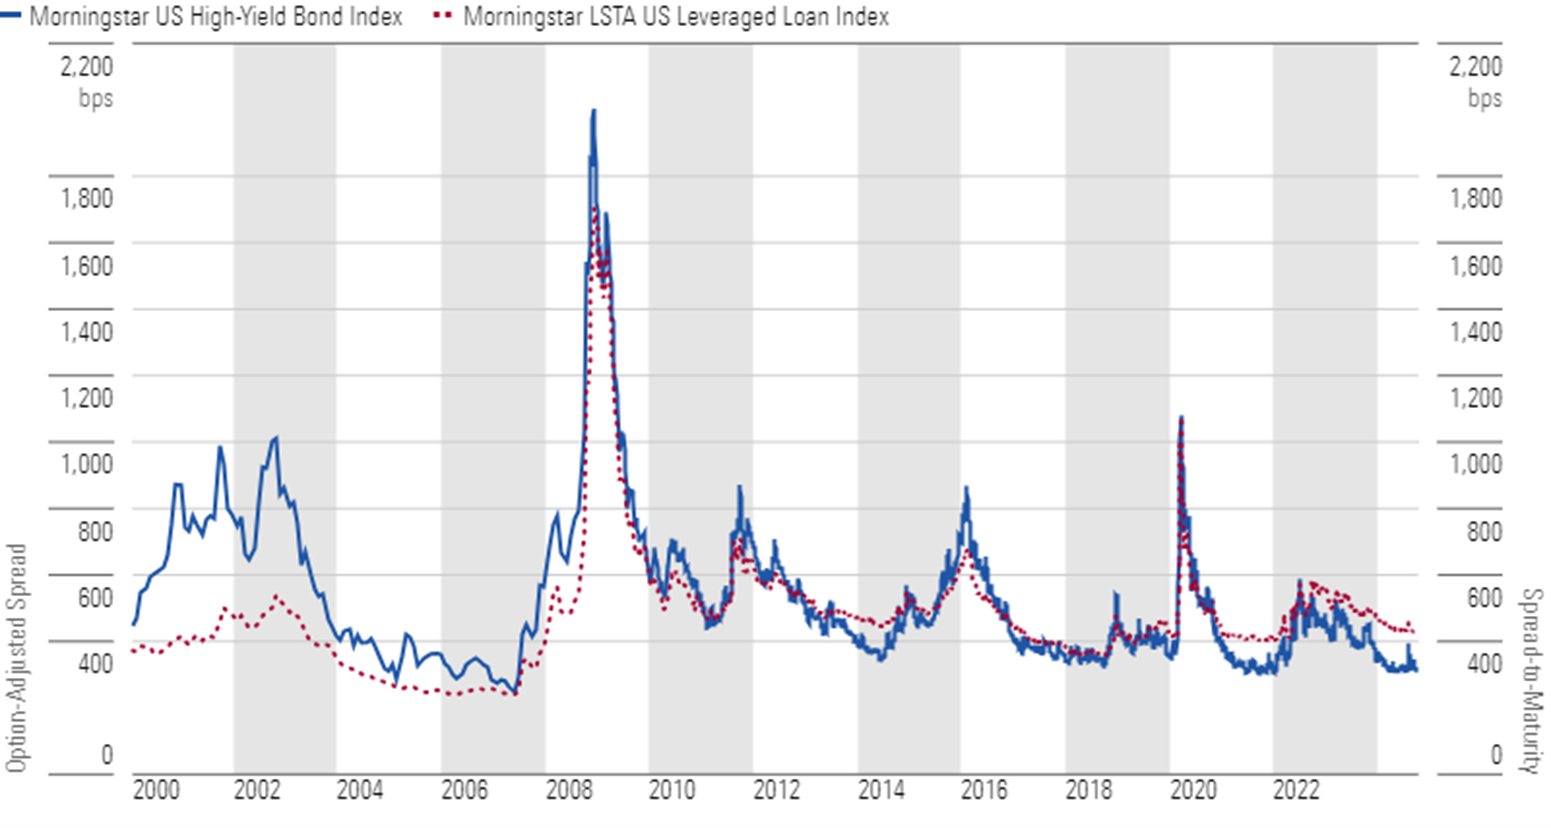
IG spreads 110bps (LQD yield 5.2%); HY at 350bps. Deregulation lifts CCC recovery rates to 85%.
Sectors: Financials (banks +50bps), energy stable.
Our Bond Ladder Guide.
Fed Policy Tug-of-War
Powell-era independence strains; Trump nominees eye rule changes. QT taper to $15B/month if unemployment >4.5%.
Scenarios:
- Hawkish: Yields +50bps.
- Dovish: -20bps.
Agency and MBS Risks
Fannie/Freddie spreads widen 10bps on prepays slowing. MBS total return -2% YTD—avoid long duration.
Global Spillovers
EU fiscal rules bind growth, boosting U.S. yields as haven flows reverse. China property drag caps commodities.
Inflation-Linked Treasuries Deep Dive
TIPS outstanding $600B; real yield 2.1%. Ladder 5-20Y for 4% real return.
Comparison:
| Bond Type | Yield | Duration Risk | Tax Advantage |
|---|---|---|---|
| Nominal 10Y | 4.3% | High | None |
| TIPS 10Y | 2.1% + Infl | Medium | State Tax Free |
| Munis AAA | 3.5% | Low | Federal Free |
| IG Corp | 5.2% | Medium | None |
Volatility Trading Opportunities
VIX term structure inverted; trade TY futures spreads.
Tools: /ZT short, /ZN long.
Portfolio Allocation Framework
- Fixed Income (40%): 20% TIPS, 10% munis, 10% IG short.
- Equities (40%): Financials, value.
- Alts (20%): Gold, commodities.
Target Sharpe 1.0+.
Rebalance monthly on 25bps moves.
Auction and Issuance Calendar Risks
$22T rollover in 2026; tails >3bps signal stress.
Monitor: Treasury announcements Tuesdays.
Long-Term Debt Sustainability
CBO warns 150% GDP unsustainable without reforms. Investors pivot to equities long-term.
Actionable 2026 Bond Roadmap
- Build TIPS ladder now (auctions monthly).
- Buy munis dips >90bps spread.
- Short 10Y futures >4.8%.
- Layer IG credit post-earnings.
- Hedge with GLD 5%.
The bond rally’s end signals yield hunt—embrace munis and credits for resilient income. Fiscal storms brew, but nimble strategies weather them.
Disclaimer: The information in this article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com assumes no responsibility for losses resulting from use of this information.
(Word count: 1,523)
Fonti


