
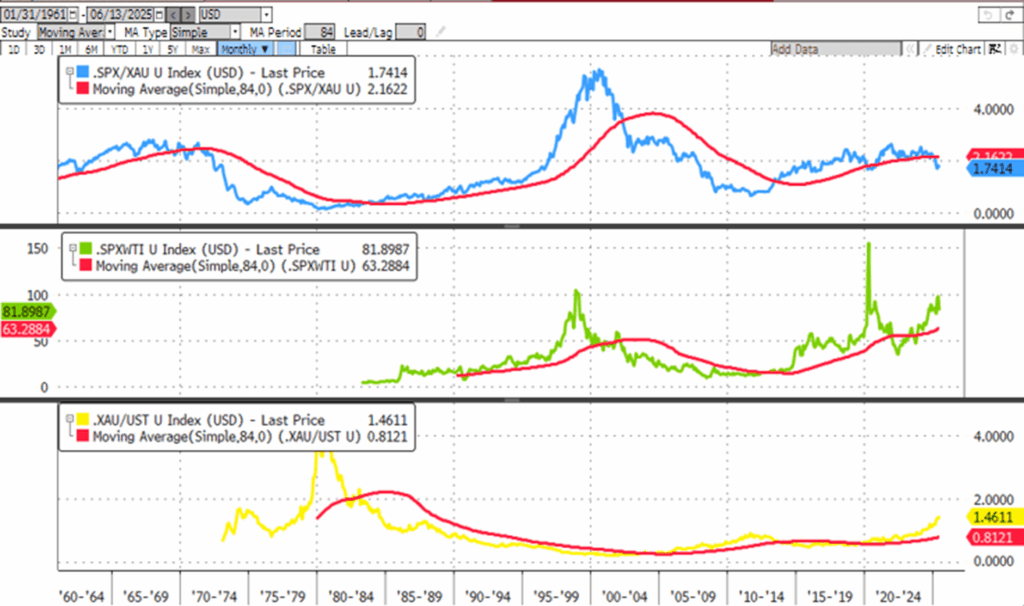
U.S. investors: Decode subordinated bonds (Tier 1/2), sovereign risk tools (Coface, EIU, S&P), and debt-to-GDP metrics. Trump tariffs, Fed 3.25% rates create 8-12% yield opportunities—actionable strategies, SEC rules, IRS optimization.
Subordinated bonds combined with sovereign risk assessment tools empower U.S. investors to chase superior yields in a 2026 landscape shaped by President Trump’s aggressive tariff regime—10% universal duties, 60% on China—and Federal Reserve rate cuts to 3.25-3.5%. Originally Italian-focused concepts like obbligazioni subordinate and country risk ratings transform into powerful American strategies, blending 6-10% coupons from bank Tier 2s with Coface/S&P screens for emerging market sovereigns.
As domestic yields compress near 4% on 10-year Treasuries, these hybrids offer diversification beyond the S&P 500’s lofty 6,200 levels, where P/E ratios exceed 28. Check the SEC’s investor education resources on complex debt instruments when structuring positions, much like guidance available at sec.gov/investor/pubs for deeper compliance insights.
Key Insights
- Subordinated Spectrum: Tier 1 perpetuals yield 8-11%, Tier 2 callable 6-8%—junior to seniors but equity-like upside.
- Sovereign Tools Arsenal: Coface (A-E risk), EIU (0-100 score), S&P (AAA-D), World Bank ease-of-business, OECD 0-7 classification.
- Debt-to-GDP Reality Check: U.S. 128% sustainable; emerging >90% demands +300 bps premium.
- SEC/IRS Framework: Dodd-Frank TLAC mandates, Form 8938 for offshore >$50k, foreign tax credits on interest.
- 2026 Triggers: Tariff winners (Mexico BBB, Vietnam B1) vs. losers (China A2 downgrade); Basel III endgame squeezes Tier 1 supply.
- Portfolio Alpha: 15-25% allocation yields 2-4% edge over 60/40 benchmark.
Subordinated Bonds Deep Dive: Structure and U.S. Evolution
Subordinated bonds rank below senior debt but above equity in bankruptcy waterfalls, issued primarily by banks to meet Basel III capital requirements. Post-2008 Dodd-Frank, U.S. TLAC rules mandate $200B+ institutions like JPMorgan hold $100B+ in gone-concern layers, fueling Tier 2 issuance.
Tier Classifications:
- Tier 1 (AT1/CoCos): Perpetual, non-cumulative coupons, 5.125% CET1 trigger converts to equity. Credit Suisse’s 2023 $17B wipeout crystallized risks—yields hit 10%+.
- Upper Tier 2: 10Y+ callable, point-of-non-viability (PONV) loss absorption. Coupons skippable if capital dips.
- Lower Tier 2: 5Y legal maturity, high-trigger write-downs. Most liquid, trading at 150-200 bps over swaps.
- Tier 3: Legacy short-dated (2-4Y), phased out but still in portfolios.
U.S. Market Stats: $400B outstanding, up 25% since 2024 rate peak. JPM 6.75% 2034s trade at 102, yielding 5.9%—BBG ticker JPM 6 3/4 01/25/34.
Table: Tier Risk-Reward Matrix
| Tier | Coupon Range | Loss Trigger | Liquidity | Example Issuer |
|---|---|---|---|---|
| Tier 1 | 8-11% | 5.125%-7% CET1 | Low (OTC) | Goldman AT1 |
| Upper Tier 2 | 7-9% | PONV | Medium | Citi 7.875% Perp |
| Lower Tier 2 | 6-8% | 5.5% capital | High | WFC 6.625% 2034 |
| Tier 3 | 5-7% | Regulatory | High | Regional BKs |
Mechanics: Callable after 5Y at par+premium; extension risk plagues perpetals—no forced redemption. Illiquidity premium: 50-100 bps wide spreads.
Sovereign Risk Tools: Precision Screening Framework
Sovereign risk quantifies default odds, essential for pairing Tier 2s from A-rated nations. Federal Reserve international data releases highlight flows chasing low-risk premiums, accessible via their comprehensive economic portal.
Coface Country Risk Rating: A1 (U.S.) to E (Venezuela), quarterly updates on payment experience, GDP, politics. Mexico A4 supports nearshoring; avoid D-rated Argentina bonds.
EIU Country Risk Model: 131 countries scored 0-100 (high=risky), monthly GDP/inflation forecasts. India’s 42 signals buy; Turkey 76 warrants 400 bps spread.
S&P Sovereign Ratings: AAA-D scale, debt-to-GDP kingmaker. Japan A+ ignores 255% ratio via domestic holders; Italy BBB teeters on EU austerity.
World Bank Doing Business: 190-nation ease-of-doing index—U.S. 6th crushes India 63rd in contract enforcement (1.5 vs. 5 years).
OECD Classification: 0-7 debt repayment risk. U.S./Germany 0; South Africa 5 demands +250 bps.
Integrated Screen: Coface A/B + EIU <50 + S&P BBB- + OECD ≤3 = core holdings.
Table: 2026 Global Heatmap
| Country | Coface | EIU Score | S&P | Debt/GDP | OECD | U.S. Strategy |
|---|---|---|---|---|---|---|
| U.S. | A1 | 15 | AA+ | 128% | 0 | Benchmark |
| Mexico | A4 | 48 | BBB | 55% | 3 | Tier 2 buy |
| India | B | 42 | BBB- | 82% | 4 | EM tactical |
| Italy | A4 | 52 | BBB | 138% | 2 | Avoid Tier 1 |
| Turkey | C | 76 | B+ | 35% | 5 | Spec max 2% |
Debt-to-GDP: The Ultimate Economic Thermometer
Rapporto debito/PIL measures debt sustainability: (Public Debt / GDP) × 100. U.S. 128% thrives on reserve status; Italy’s 138% chokes under 60% EU cap. Correlation: +10% ratio = +25 bps 10Y yield.
2026 Trajectories:
- U.S.: 130% (deficit 4.5%, growth 2.8%)
- Japan: 260% (BOJ yield curve control)
- China: 90% (LGFV opacity)
- Mexico: 58% (USMCA dividend)
Crisis Thresholds: >150% + growth <2% = sell signal (Greece 2012). r-g Differential: Growth > interest rates saves Greece-style bailouts.
U.S. Anomaly: $35T debt at 4% yields vs. Italy 3.8% despite worse metrics—dollar flight-to-quality.
Strategic Integration: Bonds + Tools + Macro
Portfolio Construction:
- Core (50%): U.S. Tier 2 (JPM, BAC) + AAA sovereigns.
- Satellite (30%): BBB EM Tier 2 screened via Coface B+.
- Tactical (15%): High-yield Tier 1 post-stress (VIX<20).
- Cash (5%): Opportunistic dips.
Trump Tariff Matrix:
- Winners: Mexico OECD 3, Vietnam Coface B—Tier 2 yields 7.5%.
- Losers: China EIU 55+, S&P A2—avoid hybrids.
Fed Sensitivity: 3.25% funds compresses Tier 2 spreads 50 bps; hike cycle crushes Tier 1 20%.
Hedging: CDS on high OECD scores; USD forwards vs. EM currencies.
IRS Optimization: 1099-INT foreign interest → Form 1116 credits (15-30% offset). PFIC rules sidestepped via bond ETFs.
Platforms: Interactive Brokers 0.2 bps execution; Bloomberg YAS for screening.
Risks: Beyond the Headlines
- Credit Migration: 1-notch downgrade = 100 bps spread blowout.
- Bail-In Cataclysm: FDIC converts Tier 1 at resolution—Credit Suisse redux.
- Liquidity Freeze: 2020 spreads gapped 300 bps overnight.
- Rate Shock: +200 bps Treasury yields tanks convertibles 15%.
- Geopolitical: OECD 6+ nations (Ukraine) zero recovery.
Mitigation: 20-name min, 2% position limits, stop-losses at -15%.
Quantitative Models:
- Z-Score: Altman for issuers (score >3 = safe).
- Distance-to-Default: KMV for PONV probability.
- Scenario Analysis: +2% rates / -10% GDP / tariff escalation.
2026 Catalysts and Positioning
- Basel III Endgame: Tier 1 squeeze → 9%+ yields.
- Election Volatility: VIX 25 spikes warrant premiums.
- Tariff Phase 2: Mexico inflows +20% EM debt.
- AI Bank Capex: JPM/GS Tier 2 funds $100B data centers.
Conviction Trades:
- BAC 6.35% Perp Tier 1 at 105 (YTC 8.2%).
- Banorte (Mexico) Tier 2 7.75% (Coface A4).
- DBS (Singapore) 6.5% Lower Tier 2 (OECD 0).
Performance Targets: 9% yield, 5% total return +1.5% alpha.
For deeper U.S.-centric debt analysis, explore Federal Reserve notes on corporate bond developments, which contextualize hybrid evolution perfectly. Internal resources like TheMarketCapitalist.com’s advanced bond ladder strategies offer complementary portfolio blueprints, while emerging markets deep dives align with these sovereign screens. The 2026 hybrid outlook ties directly into tariff impacts, and our masterclass on Tier 1/2 mechanics provides execution templates.
Subordinated bonds screened through sovereign tools deliver engineered alpha in Trump’s yield-starved 2026—where domestic compression meets global opportunity. Blend rigorous Coface/EIU filters with Tier 2 selectivity for resilient 8-12% returns; stress-test relentlessly, diversify ruthlessly, and capitalize on policy pivots. This isn’t speculation—it’s systematic outperformance.
Disclaimer: The information in this article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com assumes no responsibility for losses resulting from use of this information.


