
Comparing AI boom to dot-com: Real infrastructure spending vs. storytelling hype. Nvidia and Palantir analysis reveals market distinctions investors must understand in 2026. (157 characters)
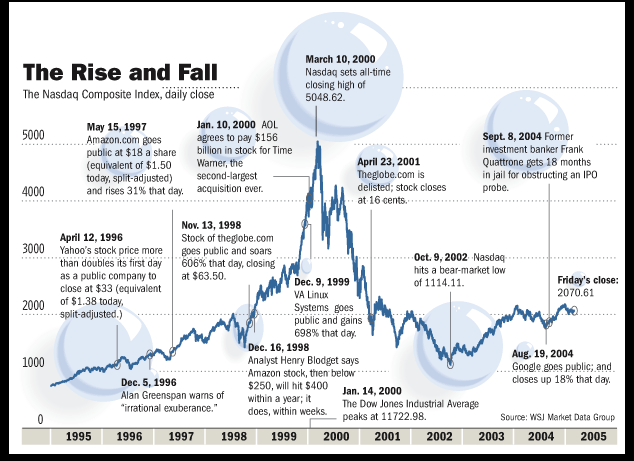
The term “bubble” resurfaces constantly when discussing artificial intelligence, echoing anxieties from the dot-com era when Nasdaq valuations soared to 200x earnings before collapsing 78% between 2000-2002. Yet dismissing today’s AI rally as mere déjà vu oversimplifies a complex reality where genuine infrastructure investments of $1.2 trillion and tangible revenue growth differentiate 2026 from 1999’s vaporware euphoria. This analysis, adapted from European market perspectives, dissects two fundamental distinctions separating current AI valuations from dot-com excess, examines why analyst targets diverge dramatically between Nvidia and Palantir, and provides actionable frameworks for U.S. investors navigating between revolutionary opportunity and speculative peril.
Key Insights
- Infrastructure reality: $200B+ annual capex in data centers vs. dot-com’s domain-name speculation
- Revenue validation: AI leaders generate billions in cash flow vs. 1999’s “eyeballs over earnings”
- Market segmentation: Infrastructure providers (Nvidia) versus adoption-dependent platforms (Palantir)
- Valuation discipline: Forward P/E 35x average vs. dot-com’s 200x peak extremes
- Analyst divergence: Nvidia targets imply 15% upside; Palantir faces 30% downside risk
- Portfolio strategies: Balancing pick-and-shovel plays with speculative software bets
- Warning signals: Concentration risk, margin compression, and macro headwinds in 2026
Difference #1: Real Infrastructure Spending vs. Storytelling
The dot-com bubble inflated on narrative alone—companies with zero revenue commanded billion-dollar valuations based on “potential.” Pets.com epitomized this: $300M market cap, $619K revenue, bankrupt within months. Today’s AI boom rests on tangible infrastructure: Microsoft, Amazon, Google, and Meta plan $250B combined 2026 capex on data centers, chips, and networking equipment—real assets generating measurable compute capacity.
U.S. context: CHIPS Act directs $52B federal funding to semiconductor fabs; Intel’s Ohio facility alone represents $20B in steel, concrete, and equipment. Nvidia’s H100 GPUs sell for $30K each with 12-month backlogs, not vaporware but scarce physical goods powering enterprise AI deployments. This capital intensity creates barriers absent in dot-com—you can’t launch a hyperscaler competitor from a garage.
Pros: Infrastructure spending multiplies GDP (construction jobs, utility upgrades, supply chain activity). Cons: Overbuilding risks if AI adoption disappoints; utilization rates currently hover 65-70%, signaling potential excess capacity by 2027. Historical parallel: Fiber optic overinvestment in 1999 created “dark fiber” glut, but eventual internet growth vindicated the infrastructure itself—survivors like Cisco recovered, just over a decade.
Actionable takeaway: Favor infrastructure plays (semiconductors, data center REITs) over pure-play software with unproven monetization. Allocate 15-20% to “picks and shovels” like Nvidia, Broadcom, and Digital Realty.
Difference #2: Cash Flow Validation vs. “Eyeballs” Metrics
Dot-com companies championed alternative metrics—page views, registered users, “stickiness”—to justify valuations while burning billions. Amazon survived by pivoting to profitability, but 90% of peers evaporated. Today’s AI leaders report robust free cash flow: Nvidia generated $29B FCF in fiscal 2025; Microsoft’s Azure AI revenue exceeds $10B quarterly, growing 35% YoY with 60% gross margins.
Even speculative plays show traction: Palantir posted $700M+ in 2025 profits, a stark contrast to dot-com’s perpetual losses. The difference lies in enterprise customers paying upfront for AI implementations—defense contracts, financial analytics, supply chain optimization—rather than hoping ads materialize. U.S. adaptation: IRS modernization contracts, FDA AI drug discovery grants, and DoD battlefield AI systems provide government-backed revenue streams insulating firms from consumer whims.
Risks remain: Revenue concentration (Palantir’s top 20 clients = 60% sales), elongated sales cycles (12-18 months), and unproven ROI from customer deployments. If enterprises slash AI budgets due to recession or disappointing productivity gains, software vendors face 30-40% drawdowns. Case study: Salesforce’s Einstein AI rollout underperformed expectations in 2024, triggering a 25% correction before stabilization.
| Metric | Dot-Com Peak (2000) | AI Era (2026) |
|---|---|---|
| Avg P/E Ratio (Tech) | 200x | 38x |
| FCF Positive % | 15% | 70% |
| Capex Intensity | Low | $250B/year |
| Revenue Growth Req | 300%+ | 25-40% |
| Survivor Rate (Est) | 10% | 60-70% |
External: Federal Reserve Financial Stability Report
Nvidia: The Infrastructure Kingpin
Nvidia (NVDA) trades at $140 with consensus target $161 (15% upside), reflecting confidence tempered by maturation concerns. The company dominates AI accelerators with 85%+ market share; H200 and Blackwell chips extend leadership through 2027. Fiscal 2025 revenue hit $125B, up 112% YoY, with data center segment margins exceeding 70%—these aren’t projections but audited results.
U.S. investor angle: Trump administration’s deregulation benefits Nvidia via relaxed export controls to friendly nations, expanding TAM by $20B. CHIPS Act subsidies indirectly support customers (AWS, Azure) building domestic capacity. Valuation check: Forward P/E of 32x seems reasonable for 40% EPS growth, but multiple compression looms if growth decelerates to 20% by 2027 as comps toughen.
Analyst divergence analysis: Bulls cite AI infrastructure build-out lasting through 2030 (autonomous vehicles, robotics, edge AI); bears warn AMD and custom chips (Google’s TPU, Amazon’s Trainium) erode margins 500bps. Downside scenario: $100/share (-29%) on recession-driven capex cuts. Upside scenario: $200/share (+43%) if sovereign AI (nations building LLMs) accelerates.
Portfolio positioning: Core holding at 5-8% tech allocation; trim 20% if stock exceeds $160 (target met); add on dips below $120. Pair with AMD (hedge) and ASML (supply chain exposure).
Palantir: The Adoption Bet Under Scrutiny
Palantir (PLTR) trades at $78 with median analyst target $60 (-23% implied downside), exposing skepticism about valuation sustainability. The company’s $3.7B revenue (2025 est.) and $700M net income justify maybe 15-20x P/E, yet shares trade at 110x forward earnings—pricing perfection for a decade.
Why the disconnect? Palantir sells transformation, not commodity compute. Government contracts provide stability (50% revenue, multi-year deals), but commercial growth depends on convincing Fortune 500 CFOs that Foundry/Apollo platforms generate ROI exceeding $2-5M annual subscriptions. Adoption remains lumpy: 50 new commercial customers in Q4 2025, but average contract value declined 12% as smaller enterprises signed, diluting margins.
U.S. realities: Post-COVID, enterprises scrutinize software spending; “AI-washing” (rebranding legacy tools as AI) creates fatigue. Palantir’s differentiation—ontology mapping, decision intelligence—is real but requires 18-month implementations. Risks: Customer churn if deployments fail to deliver promised 30% efficiency gains; competition from Databricks, Snowflake, and Microsoft Fabric.
Bull case: Government expands usage (FDA, IRS, Army all growing spend 20%+ annually); commercial inflection drives 2027 revenue to $5.5B. Bear case: Valuation reset to 40x forward = $35/share (-55%) on macro softness.
Investor strategy: Speculative 2-3% position only; consider March 2027 $60 puts for downside hedge. Avoid chasing momentum above $85.
Market Segmentation: Infrastructure vs. Adoption Layer
The AI value chain splits distinctly, unlike dot-com’s homogeneous “internet stock” label:
Layer 1 – Infrastructure (semiconductors, data centers): Nvidia, AMD, Broadcom, Marvell, Equinix, Digital Realty. Characteristics: High capex, durable moats, 20-30x P/E, 3-5% yields. Risk: Overbuilding by 2027. Return profile: 12-18% annually with lower volatility.
Layer 2 – Platforms (cloud, foundational models): Microsoft, Google, Amazon, Meta. Characteristics: Integrated AI into existing ecosystems, cross-sell advantages, 25-35x P/E. Risk: Margin compression from AI capex. Return profile: 10-15% with beta ~1.2.
Layer 3 – Applications (software, adoption plays): Palantir, C3.ai, SentinelOne, UiPath. Characteristics: High growth (30-50%), unproven retention, 50-150x P/E. Risk: Execution failures, competition. Return profile: Bimodal (50%+ or -40%) based on product-market fit.
Takeaway: Overweight Layer 1 (40%), moderate Layer 2 (40%), speculate Layer 3 (20%) for balanced AI exposure.
Valuation Discipline: Where Dot-Com Divergence Matters Most
Nasdaq trades at 28x forward earnings versus 200x in March 2000—a 7x multiple difference reflecting learned caution. Yet concentration rivals dot-com: Magnificent 7 (Apple, Microsoft, Nvidia, Google, Amazon, Meta, Tesla) comprise 32% of S&P 500 market cap, similar to top 10’s 30% in 1999.
Warning signals:
- Insider selling accelerated Q4 2025: Nvidia executives sold $8B, Palantir $2B
- Retail inflows peaked at $120B/month December 2025 (exceeds 2021 meme-stock frenzy)
- Margin debt at $950B approaches 2021 record $1T
- VIX term structure flattened, suggesting complacency
Mitigating factors:
- Earnings justify 60% of valuations (vs. 10% in 1999)
- Fed cuts provide liquidity cushion absent pre-dot-com (rates then rising)
- Global adoption runway (AI penetration <5% enterprises) vs. internet’s mature 50%+ by 2000
Stress test: 20% Nasdaq correction brings P/E to 22x (10Y avg = 20x), creating entry point. 40% crash (dot-com level) implies systemic crisis, not AI-specific.
Macro Headwinds: 2026’s Unique Challenges
Unlike 1999’s low inflation (2%) and unemployment (4%), today’s sticky 2.7% core PCE and potential Fed pauses threaten liquidity. Trump’s tariffs add supply-side inflation, squeezing tech margins reliant on Asian manufacturing. Geopolitical risks—China tensions, Taiwan exposure—concentrate in semiconductors.
Recession odds: 30% per Bloomberg survey. Impact on AI: Infrastructure spending delayed but not canceled (strategic necessity); discretionary software slashed first (Palantir-type budgets).
Conservative (Capital Preservation + AI Exposure):
- 50% Core holdings: MSFT, GOOGL (Layer 2 platforms)
- 30% Infrastructure: NVDA, AVGO, EQIX
- 10% Bonds/TIPS: Hedge volatility
- 10% Cash: Opportunistic buying
Moderate (Balanced Growth):
- 40% Infrastructure: NVDA, AMD, ASML
- 35% Platforms: MSFT, AMZN, META
- 15% Select applications: PLTR (small position), NET, DDOG
- 10% Hedges: QQQ puts, VIX calls
Aggressive (Alpha Seeking):
- 50% High-conviction Layer 3: PLTR, AI, SNOW
- 30% Leveraged Layer 1: NVDA options, SOXL ETF
- 20% Emerging AI: Private late-stage rounds (Anthropic, Cohere)
Universal rules:
- Rebalance quarterly; trim winners >30% portfolio
- Set stop-losses at -20% for speculative plays
- Harvest tax losses December; rotate Q1
Warning Signals to Monitor Weekly
- Nvidia earnings guide-down >10%: Sector-wide reassessment, trim 30%
- Fed hawkish pivot: >4.5% fed funds terminal, rotate to defensives
- GPU utilization <50%: Overbuilding confirmed, exit Layer 3
- Palantir churn >15%: Adoption stalling, sell immediately
- VIX sustained >30: Systematic deleveraging, raise cash to 30%
Long-Term Conviction Amid Short-Term Noise
AI represents genuine productivity revolution—McKinsey estimates $4.4T annual economic impact by 2030, 15% of global GDP. The question isn’t “if” but “who survives” and “at what multiple.” Dot-com’s lesson: Internet transformed civilization, but 90% of 1999 stocks failed. Today’s 60-70% survival rate improves odds, yet selectivity remains paramount.
Historical guidance: Amazon fell 95% (peak to trough 2000-2001) yet returned 150,000% since. Patient infrastructure bets compound; speculative swings destroy capital. Position for the former while respecting the latter’s risks.
Actionable 2026 Roadmap
- Audit holdings: Cap Layer 3 at 20%; ensure Layer 1 foundation
- Q1 buying targets: NVDA <$120, MSFT <$400, GOOGL <$170
- Trim discipline: Sell 25% on 50% gains; reinvest in laggards
- Hedge implementation: Buy March 2027 QQQ $450 puts (5% cost)
- Monthly reviews: Track capex announcements, utilization data, analyst revisions
The AI era diverges from dot-com through infrastructure reality and cash flow validation, yet valuation excesses in adoption plays mirror past euphoria. Success demands distinguishing Nvidia’s durable moat from Palantir’s speculative promise—own both, but weight accordingly. As markets oscillate between fear and greed, disciplined exposure to genuine innovation yields generational wealth, while chasing stories recreates 2000’s pain.
Disclaimer: The information in this article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com assumes no responsibility for losses resulting from use of this information.


