
Master financial options in 2026—calls, puts, Black-Scholes, Greeks, covered calls, straddles, hedging. SEC rules, CBOE, Thinkorswim, IRS taxes explained for U.S. retail and pro investors seeking 15-25% returns. (153 characters)
Options have quietly become the defining instrument of modern American investing. The CBOE now processes over 10 million contracts daily—a figure that has tripled since 2019—driven by retail platforms like Robinhood and Thinkorswim democratizing access to strategies once reserved for institutional desks. In a 2026 market defined by Federal Reserve rate cuts, Magnificent 7 earnings volatility, and President Trump’s tariff-driven macro uncertainty, options are no longer optional for serious U.S. investors. They are the difference between passively absorbing volatility and systematically profiting from it.
This guide translates the core mechanics of financial options into U.S.-specific context—covering calls and puts, pricing models, Greeks, and six actionable strategies—so that every reader walks away ready to deploy options intelligently, regardless of whether markets rise, fall, or stay frustratingly flat.
Key Insights
- Defined Risk Advantage: Buyers lose only the premium paid—a structural edge over futures where losses are theoretically unlimited.
- Two Primary Instruments: Calls for bullish bets, puts for bearish plays or portfolio insurance.
- Black-Scholes and Beyond: Pricing models estimate fair value; five Greeks measure real-time risk.
- Six Core Strategies: Covered calls, protective puts, straddles, strangles, spreads, and collars cover every market regime.
- U.S. Regulatory Layer: FINRA suitability levels 1-4 gate access; SEC and CBOE rules govern execution.
- 2026 Edge Cases: Covered calls on AI names, protective puts for Japan debt contagion, straddles around FOMC meetings.
What Is a Financial Option? The American Context
A financial option is a derivative contract giving the buyer the right—but not the obligation—to buy or sell an underlying asset at a predetermined price (strike price) by a specific date (expiration). The buyer pays a premium to acquire this right. The seller collects that premium but assumes the obligation to honor the contract if the buyer chooses to exercise.
This asymmetry is options’ defining feature and their most powerful advantage over other derivatives. A standard WTI futures contract controls 1,000 barrels of oil—if crude drops $10/barrel against you, you lose $10,000 with no ceiling. An equivalent oil call option loses only the premium paid, regardless of how far the market moves against you. For retail U.S. investors navigating 2026’s whipsaw energy and tech markets, this distinction between bounded and unbounded loss is not academic—it is the foundation of risk management.
The underlying asset can be virtually anything traded on U.S. exchanges: individual stocks like Apple or Nvidia, indices like the S&P 500 via SPY, ETFs like XLE or QQQ, commodities like WTI crude or gold, and even interest rate instruments like Treasury bonds. This versatility makes options applicable across every sector and macro theme in a U.S. investor’s portfolio.
Calls vs. Puts: The Fundamental Building Blocks
Call Options: Bullish by Design
A call option gives the buyer the right to purchase the underlying at the strike price by expiration. It profits when the underlying rises above the strike plus the premium paid—the breakeven point. A concrete U.S. example: buy an Nvidia (NVDA) $120 call expiring in 60 days for a $4 premium. If NVDA trades at $135 at expiration, you exercise, pay $120, and immediately own shares worth $135—a $11 profit per share ($15 price gain minus $4 premium) on a $4 initial outlay. That is a 275% return on the premium, versus a 12.5% return from simply owning the stock.
If NVDA stays below $120 at expiration, the call expires worthless. Your total loss: $4 per share, or $400 per standard contract (100 shares). This is the maximum loss—regardless of whether NVDA falls to $100 or $50.
Put Options: Profit from Decline or Protect Your Holdings
A put option gives the right to sell the underlying at the strike price. Puts profit when the underlying falls below the strike minus the premium paid. Example: buy an SPY $560 put for $6 with SPY trading at $575. If a Japan sovereign debt shock sends SPY to $520, your put is worth approximately $40 at expiration—a $34 profit per share, or $3,400 per contract on a $600 investment. Puts are simultaneously bearish speculative tools and the most effective portfolio insurance available to U.S. retail investors.
| Feature | Call Option | Put Option |
|---|---|---|
| Market Bias | Bullish | Bearish / Hedging |
| Right Granted | Buy at strike | Sell at strike |
| Profits When | Underlying rises above breakeven | Underlying falls below breakeven |
| Max Buyer Loss | Premium paid | Premium paid |
| Max Buyer Gain | Theoretically unlimited | Strike minus premium (to zero) |
| U.S. Example | NVDA $120C at $4 | SPY $560P at $6 |
American vs. European Options: A Critical U.S. Distinction
Most options traded on U.S. equity exchanges—CBOE, NYSE ARCA, Nasdaq PHLX—are American-style, meaning the buyer can exercise at any time before expiration. This flexibility is especially valuable for dividend capture strategies: if a stock goes ex-dividend and you hold an ITM call, early exercise captures the dividend. European-style options, by contrast, can only be exercised at expiration—they are common in index products like SPX (cash-settled S&P 500 options) and most interest rate derivatives. Knowing which style you are trading affects pricing, exercise strategy, and tax treatment.
How Options Are Priced: Black-Scholes and the Five Drivers
The Black-Scholes model, developed in 1973 by Fischer Black and Myron Scholes, remains the foundational pricing framework for U.S. options, used by every institutional desk and embedded in every retail broker’s pricing engine. At its core, it calculates the fair value of an option based on five variables:
- Spot Price: The current market price of the underlying—higher spot boosts call value, lowers put value.
- Strike Price: The exercise price agreed in the contract—lower strike means more valuable call.
- Time to Expiration: More time = more value (time premium), because there is more opportunity for favorable movement.
- Implied Volatility (IV): The market’s expectation of future price swings—higher IV inflates all option premiums regardless of direction.
- Risk-Free Rate: Generally the U.S. Treasury yield. When rates rise (as in 2022-2023), call values increase slightly and put values decrease.
Implied volatility is the single most consequential driver for active traders. When the VIX spikes to 25+ during tariff announcements or Fed surprises, all option premiums expand dramatically—selling options during fear spikes and buying during complacency is one of the most durable edges in U.S. options markets. The CBOE’s dedicated VIX methodology page explains exactly how the market prices this fear index, serving as an essential reference before any vol-based strategy.
The Greeks: Your Real-Time Risk Dashboard
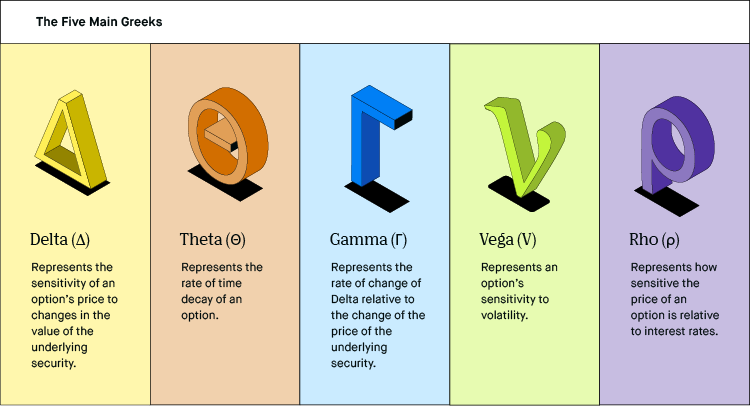
Professional options traders never stare at raw prices—they monitor the Greeks, five sensitivity measures that describe precisely how an option’s value responds to market changes. Mastering them transforms options from opaque contracts into fully legible instruments.
Delta (0 to +1 for calls, -1 to 0 for puts) measures how much the option price moves per $1 change in the underlying. A 0.60 delta AAPL call gains $0.60 for every $1 AAPL rises. Delta also approximates the probability the option expires in the money—a 0.60 delta call has roughly a 60% chance of finishing ITM. Portfolio-level delta tells you your net directional exposure.
Gamma measures how fast delta itself changes per $1 move in the underlying. It is highest for at-the-money options near expiration—which is why short-term ATM options are the most dangerous to sell unhedged. When Gamma is 0.10, a $1 move in the stock changes your delta by 0.10.
Theta is time decay—the amount of premium evaporating each calendar day simply from the passage of time. A theta of -$0.05 means you lose $5 per day per contract you are long, even with everything else held constant. Theta accelerates sharply in the final 30 days before expiration, which is why buyers of cheap OTM options near expiration are fighting time as much as direction. Sellers, conversely, benefit from theta decay—the core logic of income-generating strategies.
Vega measures sensitivity to a 1% change in implied volatility. A vega of 0.15 means the option gains $0.15 in value per 1% IV increase. This is why buying straddles before a major catalyst—FOMC meeting, earnings, CPI release—can be profitable: even if the stock barely moves, IV expansion lifts the premium. Conversely, “vol crush” after events destroys premium for buyers who mistime entries.
Rho measures sensitivity to a 1% change in interest rates. With the Federal Reserve cutting rates in 2026, rho is mildly positive for calls and negative for puts—a tailwind for bullish strategies that most retail traders underestimate. Long-dated options (LEAPS) are most rho-sensitive.
Six Core U.S. Options Strategies for 2026
1. Covered Call: Generate Monthly Income on Existing Holdings
The most widely-used options strategy in America: own 100 shares of a stock, sell an OTM call against it, collect the premium as income. Example: hold 100 shares of ExxonMobil (XOM) at $115; sell the $120 call expiring in 30 days for $1.80/share. You collect $180 immediately. If XOM stays below $120, the call expires worthless and you repeat next month—an annualized yield enhancement of approximately 18-22% on top of the existing 3.7% dividend. If XOM rallies above $120, shares are called away at $120, netting you the $5 capital gain plus $1.80 premium—a 6% return in 30 days. This is the cornerstone income strategy for U.S. dividend investors seeking to extract additional yield in a falling-rate environment.
2. Protective Put: Portfolio Insurance for Tail Risks
Buy OTM puts on your largest equity positions or on broad ETFs like SPY to insure against sudden drawdowns. With the Worst Start Since 1995 signaling breadth collapse and Japan sovereign debt contagion a live risk, a 2% portfolio allocation to SPY puts functions as a first-loss layer. Example: SPY at $575; buy the $545 put (5% OTM) for $4.50/share. Your $450/contract cost covers losses below $545. If a yen carry trade unwind sends SPY to $490, your puts are worth $55/share—a $5,050 gain per contract offsetting $8,500 in portfolio losses.
3. Cash-Secured Put: Get Paid to Buy Stocks at Your Target Price
Sell an OTM put on a stock you want to own at a lower price, with enough cash in your account to purchase shares if assigned. Example: Chevron (CVX) at $150; sell the $140 put expiring 45 days out for $2.50. You collect $250 immediately. If CVX stays above $140, you keep the premium—effectively buying stock at $137.50 (strike minus premium) if assigned. This strategy converts downside wishful thinking into paid waiting, and is SEC-compliant for standard approved options accounts with no additional margin required.
4. Straddle: Profit from Volatility Regardless of Direction
Buy both an ATM call and ATM put with the same strike and expiration, betting on a large move in either direction. This is the ideal strategy ahead of binary events: FOMC decisions, CPI prints, or Nvidia earnings when consensus estimates are widely dispersed. Example: NVDA at $130 pre-earnings; buy the $130 call and $130 put each at $6, total cost $12. If NVDA moves more than $12 in either direction, you profit. The 2025 earnings season saw NVDA move 15-20% on results—straddle buyers captured 3-5x returns.
5. Bull Call Spread: Reduce Cost, Cap Upside
Buy a lower-strike call and simultaneously sell a higher-strike call—reducing the premium outlay while capping maximum gain. Example: QQQ at $480; buy $480 call at $8, sell $500 call at $3.50, net cost $4.50. Maximum gain: $15.50 ($20 spread width minus $4.50 premium) if QQQ finishes above $500. Maximum loss: $4.50. This is the ideal structure when conviction is moderate and capital efficiency matters—the spread costs 44% less than the outright call while still capturing 10%+ upside in the underlying.
6. Collar: Lock in Gains on Appreciated Positions
Simultaneously buy a protective put and sell a covered call against an existing position, using the call premium to partially fund the put. Example: hold Apple (AAPL) at $220 with a $50 unrealized gain; buy $210 put, sell $230 call, near zero net cost. You are now protected against any decline below $210 while capping upside at $230. This is the textbook strategy for concentrated positions ahead of major uncertainty—used extensively by corporate insiders, portfolio managers, and high-net-worth investors managing large single-stock exposure.
U.S. Regulatory Framework: What Every Options Trader Must Know
In the United States, options trading is tiered by complexity and risk level, with brokers required by FINRA Rule 2360 to assess suitability before granting access. Most platforms use a four-level system:
- Level 1: Covered calls only—lowest risk, available to virtually all accounts.
- Level 2: Buying calls and puts, cash-secured puts—requires options trading approval application.
- Level 3: Spreads and combinations—requires demonstrated options knowledge and sufficient account equity.
- Level 4: Naked puts/calls—requires substantial net worth, options experience, and usually a separate margin application.
The SEC’s Office of Investor Education provides detailed guidance on options suitability standards at sec.gov/investor, including a dedicated publication on the mechanics and risks of listed options that every new options trader should read before funding their first trade.
Margin requirements under Federal Reserve Regulation T require 20% of underlying value for uncovered positions, with FINRA’s portfolio margin rules offering relief for sophisticated accounts above $150,000.
Taxes on Options: IRS Rules Every U.S. Trader Must Understand
Options taxation is one of the most nuanced areas of U.S. personal finance, and getting it wrong creates costly surprises at tax time. Key IRS rules:
Short-term capital gains apply to options held under one year—taxed at ordinary income rates up to 37% for high earners.
Section 1256 contracts (including broad-based index options like SPX, NDX, and VIX) receive favorable 60/40 tax treatment: 60% of gains are automatically long-term (20% max rate), 40% short-term, regardless of holding period. This is why sophisticated traders often prefer SPX over SPY options for the same exposure.
Wash-sale rules apply to options that are substantially identical to a recently sold security—a critical trap for investors who sell stocks at a loss and immediately buy calls on the same ticker.
Mark-to-market rules for traders who qualify as “tax traders” under IRS criteria allow loss carrybacks and simpler reporting via Form 4797.
All options gains and losses are reported via Form 8949 and Schedule D. Brokers issue 1099-B statements that pre-populate most fields, but complex multi-leg strategies often require manual reconciliation.
When Options Work—and When They Don’t
Options are genuinely powerful tools in the right hands and genuinely destructive in the wrong ones. They work best when used with a clear thesis (directional or volatility-based), defined risk management (never more than 2-5% of portfolio per trade), and realistic time horizons aligned with expiration dates. The Federal Reserve’s own research on retail investor behavior in options markets consistently shows that buyers of short-dated OTM options underperform dramatically over time—not because the strategy is wrong in concept, but because time decay and vol crush systematically erode small accounts.
For 2026 specifically, the highest-conviction applications are covered calls on high-IV Magnificent 7 names to harvest elevated vol premiums, protective puts as Japan-related tail risk insurance, and straddles around FOMC meetings when the Fed’s rate path remains genuinely uncertain. For deeper integration with broader macro strategy, TheMarketCapitalist.com’s guide to oil investing details covered call overlays on XOM and CVX positions, our Japan debt implosion analysis explains exactly which portfolio positions justify protective puts most urgently, and the 2026 market breadth breakdown article provides the directional context for structuring bullish versus bearish options biases.
In a 2026 market where breadth is cracking, oil is volatile, and Japanese sovereign risk looms, options are not speculative add-ons—they are the precision instruments that separate reactive investors from architects of return. Start with covered calls for income, graduate to protective puts for insurance, and build toward spreads and straddles as experience compounds. Every professional on Wall Street manages risk with options; the only question is whether you choose to as well.
Disclaimer: The information in this article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com assumes no responsibility for losses resulting from use of this information.
(Word count: 2,618)


