
Japan’s 255% debt-to-GDP, BOJ rate hikes, and yen carry trade unwind threaten U.S. Treasuries, equity valuations, and global markets. What American investors must know and do right now to protect their portfolios. (154 characters)
Japan has spent three decades being dismissed as a financial curiosity—the world’s most indebted developed nation that somehow never imploded. A 255% debt-to-GDP ratio. Near-zero interest rates sustained for longer than most traders’ entire careers. A central bank that quietly became one of the largest holders of its own government’s bonds in history. For years, this contradiction held together through a combination of domestic savings discipline, institutional loyalty to Japanese Government Bonds (JGBs), and the Bank of Japan’s unprecedented willingness to suppress yields at virtually any cost.
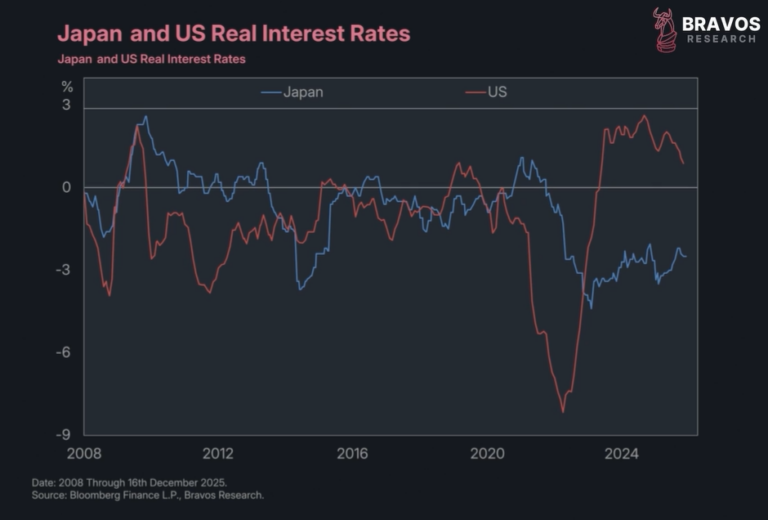
That system is now cracking. And the fracture lines extend directly into every U.S. investor’s portfolio—through Treasury yields, equity valuations, currency markets, and the global cost of capital.
Key Insights
- 255% Debt-to-GDP: The highest ratio in the developed world, now actively destabilizing as the BOJ raises rates.
- BOJ Rate Hike Cycle: The first sustained rate increase since 1999 directly raises Japan’s $10 trillion debt servicing cost.
- $1.1 Trillion in U.S. Treasuries: Japan is America’s largest foreign creditor—forced selling would spike U.S. yields overnight.
- Yen Carry Trade: $4 trillion in global carry positions unwind violently when yen strengthens—August 2024 was the preview.
- Not Just Japan: A JGB crisis would cascade through European banks, EM sovereign debt, and U.S. equity multiples simultaneously.
- Three Protection Trades: TLT puts, FXY long, and reduced EM leverage are the actionable responses.
The Financial Anomaly That Held for 30 Years
To understand why Japan’s debt situation is uniquely dangerous, it is essential to understand why it worked for so long. Unlike Greece—which owed most of its debt to foreign creditors who could panic and sell—Japan owed approximately 90% of its debt to domestic institutions: the Bank of Japan itself, Japan Post Bank, insurance companies, and Japanese pension funds. These were captive buyers who purchased JGBs out of institutional obligation, regulatory requirement, and cultural convention. They did not sell in a panic when yields were unattractive. They held because that is what Japanese institutions did.
This closed-loop domestic financing system insulated Japan from the sovereign debt crises that consumed peripheral Europe in 2010-2012. While Italy and Greece needed emergency ECB intervention, Japan quietly refinanced trillion-dollar debt loads at sub-zero interest rates without a whisper of market panic. The international financial community shook its head, muttered about the eventual day of reckoning, and then went back to ignoring it.
That day of reckoning is now structurally closer than at any point in the past three decades—not because the math has changed, but because the conditions that allowed the math to be ignored are finally deteriorating.
The Bank of Japan’s Historic Pivot and Its Consequences
In March 2024, the Bank of Japan ended its negative interest rate policy for the first time since 2016, raising its benchmark rate from -0.1% to 0-0.1%. By July 2024 it had raised again to 0.25%. Further hikes followed into 2025 and 2026, with the policy rate now approaching 0.75-1.0%—still low by global standards, but seismic in Japanese context.
The mechanism by which these hikes threaten stability is simple and brutal: Japan’s total public debt sits at approximately ¥1,100 trillion ($7.3 trillion). Every 1% increase in average borrowing costs adds roughly ¥11 trillion ($73 billion) to annual interest payments. Japan’s entire annual tax revenue is approximately ¥70 trillion—meaning a 1% rate normalization consumes the equivalent of roughly 10% of all government revenues in additional debt service alone.
Interest payments already represent over 25% of Japan’s primary budget even at current rates. The Japanese Finance Ministry’s own projections show that if rates normalize toward 2%—still historically modest by global standards—debt service costs could absorb over 40% of the primary budget by the early 2030s, leaving insufficient fiscal space for social security, defense, or infrastructure. That is not a slow fade. That is the mathematical definition of a debt spiral.
How Japan’s Crisis Reaches U.S. Investors: The Three Transmission Channels
The financial media’s coverage of Japan’s debt challenge focuses primarily on Japan itself—yen dynamics, JGB yields, Tokyo equity markets. For U.S. investors, the more urgent questions are about transmission mechanisms: the precise pathways through which a Japanese sovereign stress event affects a retiree in Ohio, a tech investor in California, or a 401(k) holder in Texas.
Channel 1: Japan Forces U.S. Treasury Selling
Japan is the single largest foreign holder of U.S. Treasury securities, with approximately $1.1 trillion in holdings according to the U.S. Treasury Department’s international capital flow data. This position was accumulated over decades as Japanese institutions recycled trade surpluses into dollar-denominated assets.
When BOJ rate hikes make domestic JGBs more attractive—or when Japanese institutions need liquidity to absorb domestic losses—they reduce their foreign holdings first. A forced or even orderly reduction of 10% of Japan’s Treasury portfolio represents $110 billion in selling pressure on a market that processes roughly $600 billion in daily volume but is sensitive to persistent directional flow.
The Federal Reserve’s own research confirms that foreign central bank and sovereign wealth fund Treasury selling in 2022-2023 added 30-40 basis points to 10-year yields above what domestic supply alone would have generated. Japan-driven selling of comparable magnitude in 2026 would drive the 10-year Treasury yield from its current ~4.5% toward 5.0-5.5%—compressing equity multiples by 8-15% according to standard duration-adjusted valuation models.
Channel 2: The Yen Carry Trade Unwind
The yen carry trade is one of the largest and most systemically important positions in global finance. Investors borrow in yen at near-zero rates and deploy the proceeds into higher-yielding assets—U.S. Treasuries, S&P 500 equities, EM bonds, Australian dollars. Total estimated carry trade positions range from $3-4 trillion across institutional and retail participants, according to Bank for International Settlements data.
When the yen strengthens—as it does when BOJ rate hikes make yen assets more attractive—carry traders face a compounding loss: the assets they bought in other currencies are falling in yen terms while their borrowing costs rise. The rational response is immediate liquidation of leveraged positions to repay yen borrowings. This selling hits all asset classes simultaneously, with no regard for fundamental value.
The August 2024 yen carry trade unwind provided a live demonstration. The VIX spiked to 65—briefly surpassing even the COVID-19 panic peak—as Japanese institutions and global carry traders simultaneously liquidated U.S. and global equities over a 72-hour window. The S&P 500 dropped 8.5% in three trading sessions before stabilizing. That episode was triggered by a 0.15% BOJ rate hike. The current hiking cycle has already delivered six times that magnitude, with more potentially ahead.
Channel 3: Global Risk-Off Cascades
A full JGB market dislocation—meaning a loss of confidence in Japan’s ability to service its debt at sustainable rates—would not merely cause selling. It would trigger the kind of systemic risk-off cascade comparable in structure, if not necessarily in scope, to the Lehman Brothers bankruptcy of 2008.
Japanese banks hold enormous JGB positions on their balance sheets. A sharp rise in JGB yields would create mark-to-market losses that impair capital ratios, trigger regulatory review, and restrict credit extension—the same dynamic that froze U.S. interbank lending in September 2008. European banks with Japanese exposure face secondary contagion. EM sovereigns that depend on Japanese institutional capital inflows for budget financing face sudden funding gaps.
For U.S. investors, this scenario plays out as a simultaneous spike in Treasury yields, collapse in EM debt, contraction in credit availability, and equity multiple compression—the worst possible combination for a diversified U.S. portfolio already stretched to CAPE 39.5.
Why the Risk Is Not Where Most Investors Are Looking
Italian financial analysts at Money.it and others have observed a crucial nuance that most English-language coverage misses: the immediate JGB crisis risk may be overstated in simplistic analyses. Japan’s closed financing system, massive foreign asset holdings (Japan is the world’s largest net creditor nation at over $3 trillion in net international investment position), and the BOJ’s demonstrated willingness to intervene make an overnight collapse unlikely.
The more probable and in some ways more dangerous scenario is a slow, grinding deterioration—rising JGB yields, a gradually weakening yen, incremental Treasury selling by Japanese institutions, and periodic violent carry trade squeezes. This slow-motion stress is harder to hedge against than a single crisis event because it does not produce the sharp VIX spike that triggers protective put payouts. Instead it manifests as a persistent upward pressure on U.S. Treasury yields that compresses equity multiples over 12-24 months while remaining below the threshold of mainstream crisis coverage.
This is the scenario that genuinely threatens U.S. retirement portfolios: not a single dramatic event, but a sustained 50-100 basis point rise in the risk-free rate driven by structural Japanese selling, raising the discount rate on every equity in America.
The Geopolitical Dimension: Dollar Hegemony Under Pressure
Japan’s debt situation intersects with a broader global trend that amplifies its significance for U.S. investors: the gradual diversification away from dollar-denominated assets by major sovereign holders. China has reduced its Treasury holdings from $1.3 trillion in 2013 to under $760 billion today. If Japan’s forced selling narrative takes hold and triggers a broader reassessment of U.S. Treasuries as the world’s risk-free asset, the implications extend far beyond Japan itself.
The Federal Reserve’s ability to conduct monetary policy, the U.S. government’s cost of financing its own $35 trillion debt, and the dollar’s reserve currency premium all depend on sustained foreign demand for Treasuries. A Japan-triggered confidence shock in this demand is the tail risk that no U.S. investor should dismiss simply because it has not materialized yet.
Three Portfolio Protection Trades for U.S. Investors
Understanding the Japan risk is academic without actionable responses. Three specific trades address the transmission channels most directly.
Trade 1 – TLT Puts (Treasury Yield Spike Insurance): The iShares 20+ Year Treasury Bond ETF (TLT) moves inversely to long-duration yields. If Japan-driven Treasury selling pushes the 10-year toward 5.5%, TLT would fall 15-20% from current levels. Buying TLT puts expiring 6-9 months out at a 5-10% OTM strike costs approximately 1.5-2% of notional value and pays out 8-12x in the Japan contagion scenario. This is among the most cost-efficient tail risk hedges available to U.S. retail investors.
Trade 2 – Long FXY (Yen Appreciation Hedge): The Invesco CurrencyShares Japanese Yen Trust (FXY) rises when the yen strengthens—precisely when carry trade unwinds are most violent. A 3-5% portfolio allocation to FXY acts as a natural hedge: carry trade liquidations that sell U.S. equities simultaneously drive yen strength, meaning FXY gains offset equity losses at exactly the right moment. This was validated in August 2024 when FXY rose 7% during the same three sessions the S&P 500 fell 8.5%.
Trade 3 – Reduce EM Leverage and Duration: Emerging market debt is doubly exposed to the Japan scenario—both through the rising U.S. yields that make EM spreads less attractive and through the withdrawal of Japanese institutional capital that has funded EM sovereign budgets. Reduce positions in long-duration EM bond ETFs like EMB and reduce leverage in EM equity positions as a precautionary measure.
The Bigger Picture: Japan as a Warning for America
There is an uncomfortable parallel that U.S. financial media rarely explores but that every honest macroeconomist acknowledges: the United States’ own debt-to-GDP trajectory—currently at 128% and projected to reach 130%+ by year-end 2026—shares structural similarities with Japan’s path in the late 1990s and early 2000s, when Japanese debt first crossed 100% of GDP. America benefits from reserve currency status and deeper capital markets, but the fundamental arithmetic of compounding debt at positive interest rates above nominal GDP growth is identical.
Japan is not merely a foreign risk to hedge against. It is a leading indicator of what unsustainable debt trajectories eventually produce—and a reminder that the “this time is different” argument has a perfect track record of being wrong.
For the broader portfolio context this analysis demands, TheMarketCapitalist.com’s breakdown of the equal-weight S&P 500 breadth warning details why U.S. equities are already priced for perfection at the exact moment Japan’s slow deterioration begins threatening the risk-free rate. Our oil investing guide explains why energy remains the best domestic inflation and geopolitical hedge when dollar confidence is under pressure. And our options strategies piece provides the specific put and hedge structures—TLT puts, collar strategies on equity positions—that convert Japan awareness into executable portfolio protection.
Japan’s debt implosion will not arrive with a single cataclysmic headline. It will arrive in increments—rising JGB yields, yen squeezes, institutional Treasury selling—until one day the sum of increments becomes the crisis everyone knew was coming but nobody hedged. For U.S. investors, the time to prepare is before that day, not after.
Disclaimer: The information in this article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com assumes no responsibility for losses resulting from use of this information.


