
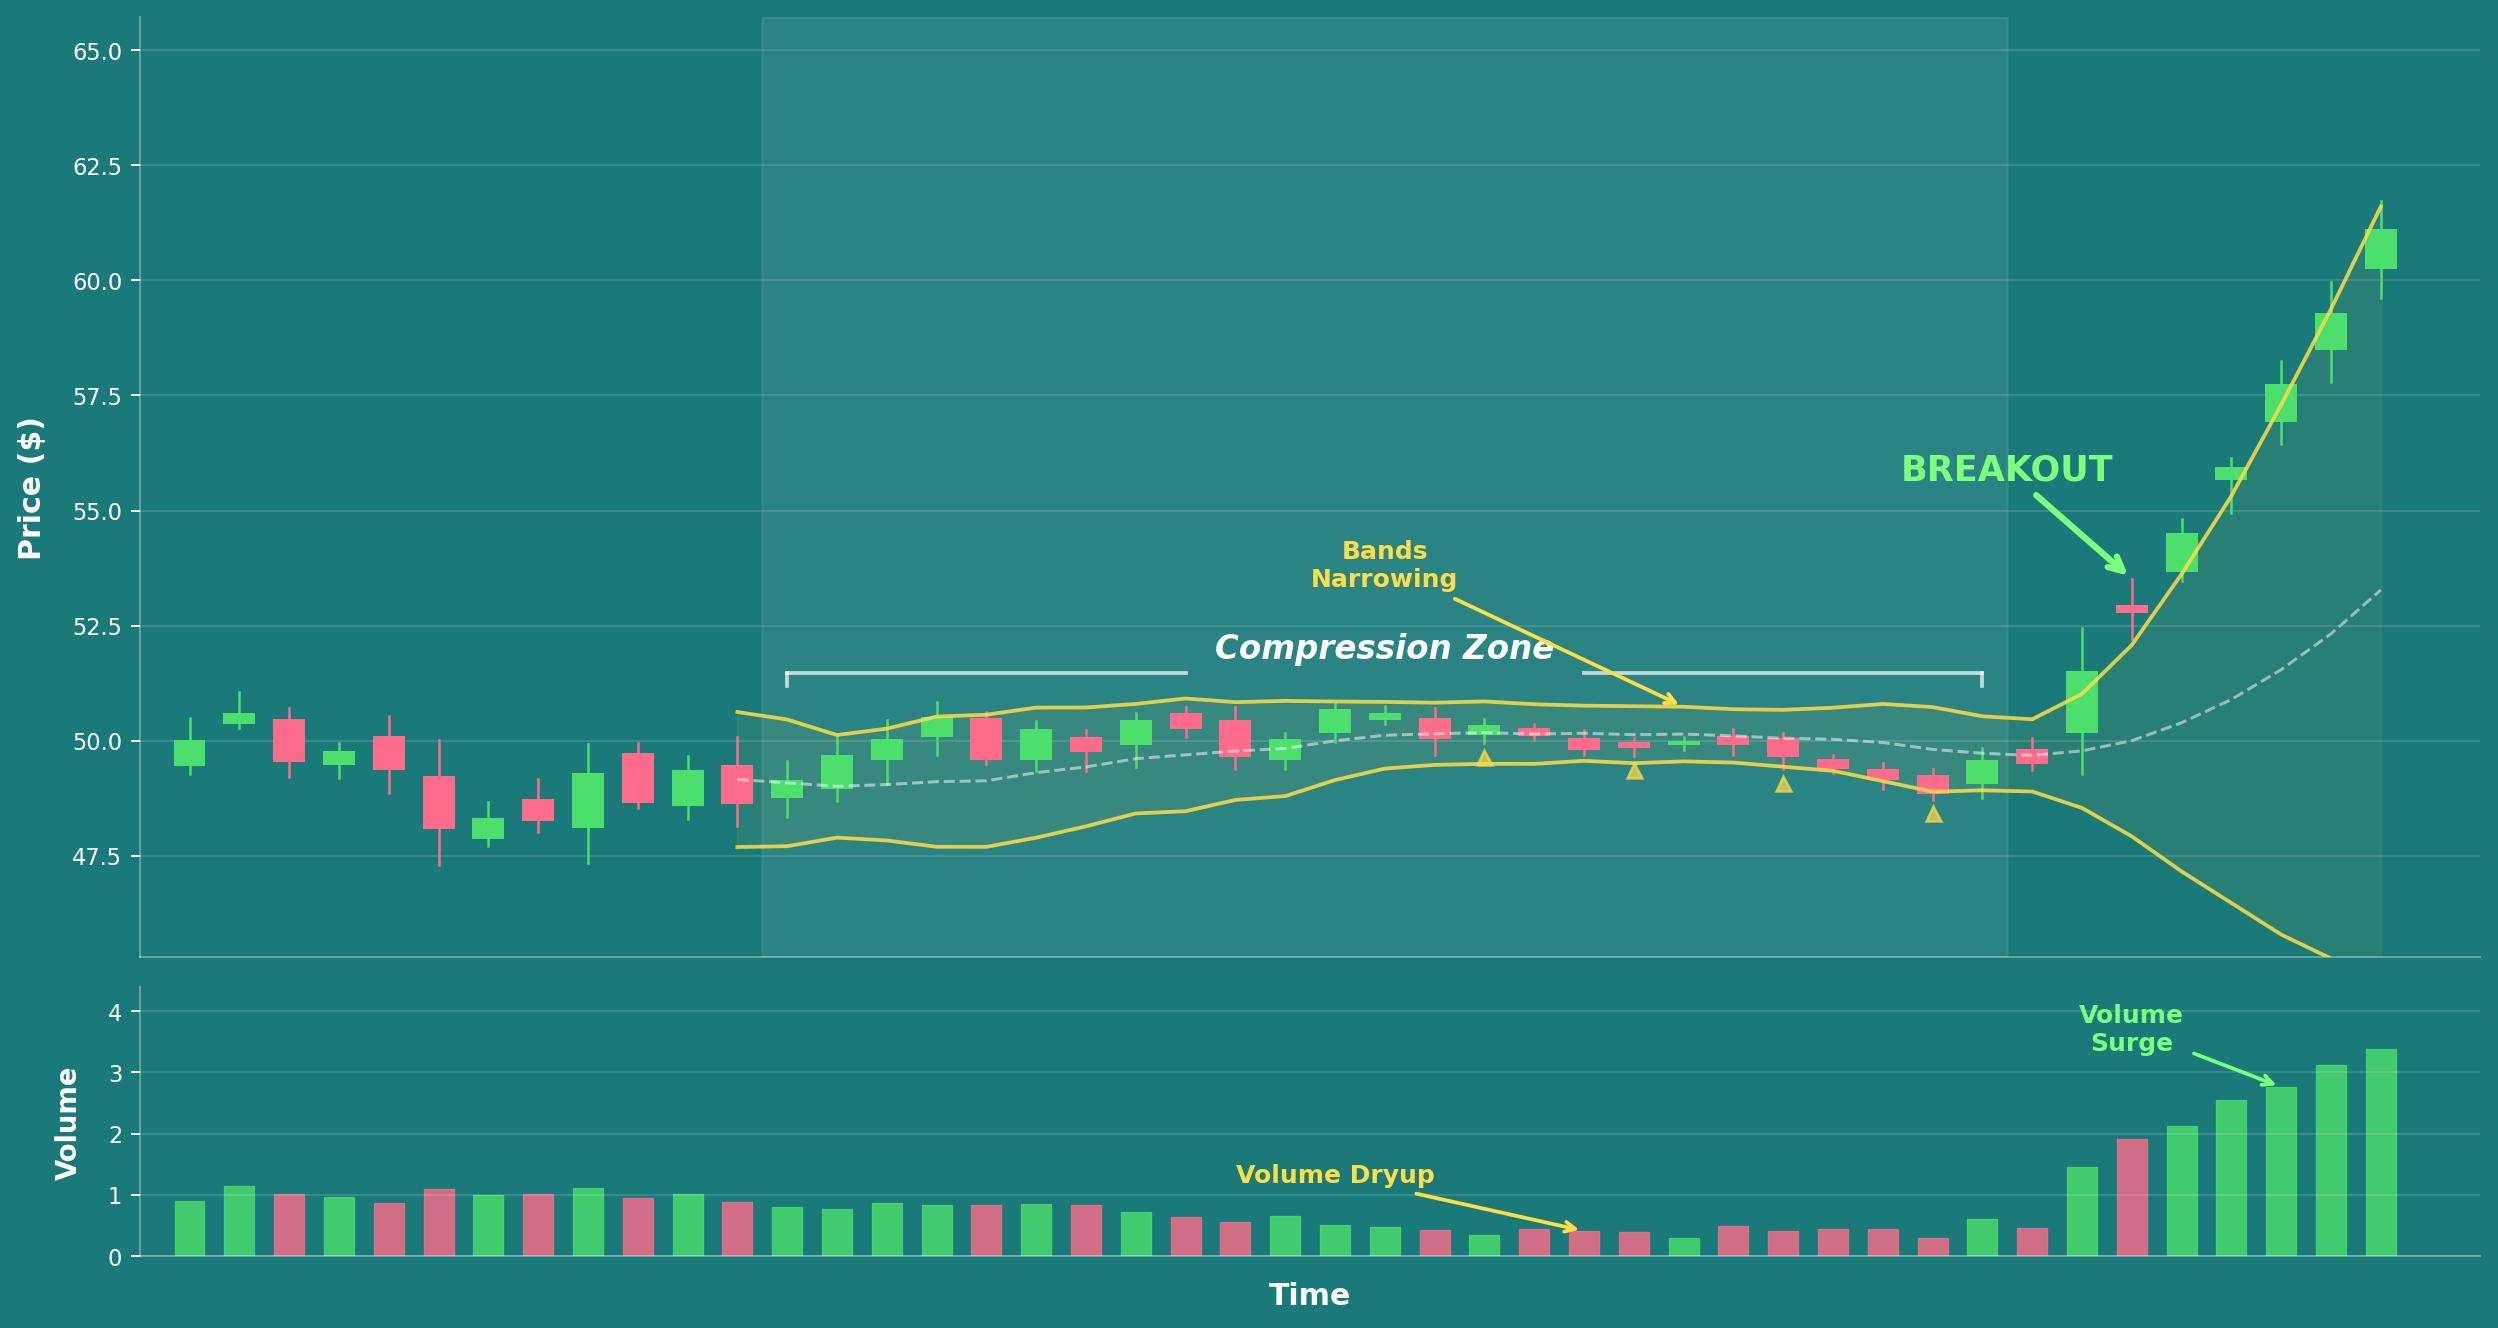
Markets often look calm right before they get hit by something they are not pricing correctly. In 2026, one of the biggest hidden risks for U.S. investors is the combination of compressed volatility, rising geopolitical tension, and the possibility of an energy shock centered on the Strait of Hormuz.
The danger is not just that oil could spike. It is that a spike in oil can quickly move into inflation, Treasury yields, Fed policy expectations, mortgage rates, and equity valuations. That is why a seemingly distant geopolitical issue can become a direct portfolio risk for American investors.
Key insights
- Low volatility can hide real fragility.
- The Strait of Hormuz remains a critical global energy chokepoint.
- An oil shock would likely revive inflation pressure.
- The Fed would have less room to support growth.
- Growth stocks and long-duration assets are most exposed.
Why calm markets can be dangerous
Investors often mistake low day-to-day price movement for safety. When volatility is compressed, it becomes easy to assume that the market has already absorbed the risk and that nothing major is likely to happen. But in many cases, low volatility means the market is simply complacent.
That complacency is especially dangerous when the risk involves energy. Oil is one of the few inputs that can still shock the entire financial system quickly. If prices jump because of supply disruption or conflict, the impact does not stay confined to crude producers. It spreads into shipping, transportation, manufacturing, consumer spending, and interest-rate expectations.
The result is a delayed but powerful repricing across multiple asset classes. What looked like a stable market can suddenly become one where investors are forced to rethink almost every assumption they had about inflation and growth.
The Hormuz problem
The Strait of Hormuz is one of the most important energy routes in the world. A major share of global oil flows through that narrow passage, which makes it a strategic pressure point whenever tensions rise in the Middle East. If shipping is disrupted or if markets even believe disruption is possible, the price of oil can react immediately.
That matters because oil is not just a commodity. It is a macroeconomic input. When oil rises sharply, inflation expectations often follow. Once inflation expectations move higher, the Federal Reserve gets less flexibility to cut rates or support growth. That can change the entire tone of the market.
For U.S. investors, the real issue is not only the geopolitical event itself. It is what that event does to policy expectations, financing conditions, and risk appetite. In other words, the Strait of Hormuz is not just a regional flashpoint. It is a transmission mechanism into U.S. markets.
Why this matters for inflation
The first place Americans usually feel an energy shock is at the gas pump. But the broader effect is much bigger. Higher fuel costs raise transportation expenses, squeeze business margins, and ripple through household budgets. Even if the initial move in oil is temporary, it can still change inflation psychology.
That change matters because the Fed reacts not only to current inflation but also to the risk of inflation becoming sticky again. If policymakers believe energy prices could reignite inflation, they are less likely to ease policy aggressively. That is a problem for markets that are currently priced for a more favorable rate environment.
The most vulnerable assets in that scenario are usually the ones that depend on lower discount rates. Long-duration growth stocks, high-multiple tech names, and longer-term bonds can all suffer when inflation expectations rise. What looked like a benign macro setup can quickly become a valuation problem.
Which portfolios are most exposed
Many investors believe they are diversified because they own multiple ETFs or a mix of stocks and bonds. But if their portfolio leans heavily toward growth stocks, rate-sensitive sectors, or long-duration assets, they may be carrying more macro risk than they realize.
The biggest exposures include:
- High-growth technology stocks.
- Long-term Treasury bonds.
- Mortgage-sensitive assets.
- Real estate investment trusts and housing-related equities.
- Broad index funds dominated by mega-cap tech.
The key issue is correlation. When inflation jumps, many of these assets can fall together. That means the investor who thought they were diversified may actually be holding several assets that all react to the same shock in the same direction.
What a better response looks like
The smart response is not to make a dramatic geopolitical bet. It is to make sure the portfolio can survive a bad energy surprise. That may mean reducing concentration in rate-sensitive names, adding some exposure to sectors that benefit from higher commodity prices, or simply keeping more liquidity available.
Investors should also pay close attention to oil prices, Treasury yields, and Fed communication. Those are the main channels through which geopolitical tension becomes a market event. When those variables start moving together, the market may be telling you that the calm period is ending.
It is also worth remembering that volatility compression often ends abruptly. Markets do not usually reprice risk slowly when the trigger is geopolitical. They often wait, ignore the warning signs, and then move all at once. That is why the time to prepare is before the shock, not during it.
Conclusion
Compressed volatility is not proof that risk is gone. In 2026, the bigger danger may be that investors have become too comfortable just as the energy backdrop is becoming less stable. If the Strait of Hormuz becomes a serious market concern, the consequences could extend far beyond oil and hit inflation, rates, and equity valuations at the same time.
For U.S. investors, the lesson is simple: calm markets do not always mean safe markets. Sometimes they just mean the market has not yet been forced to wake up.
Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk.


