
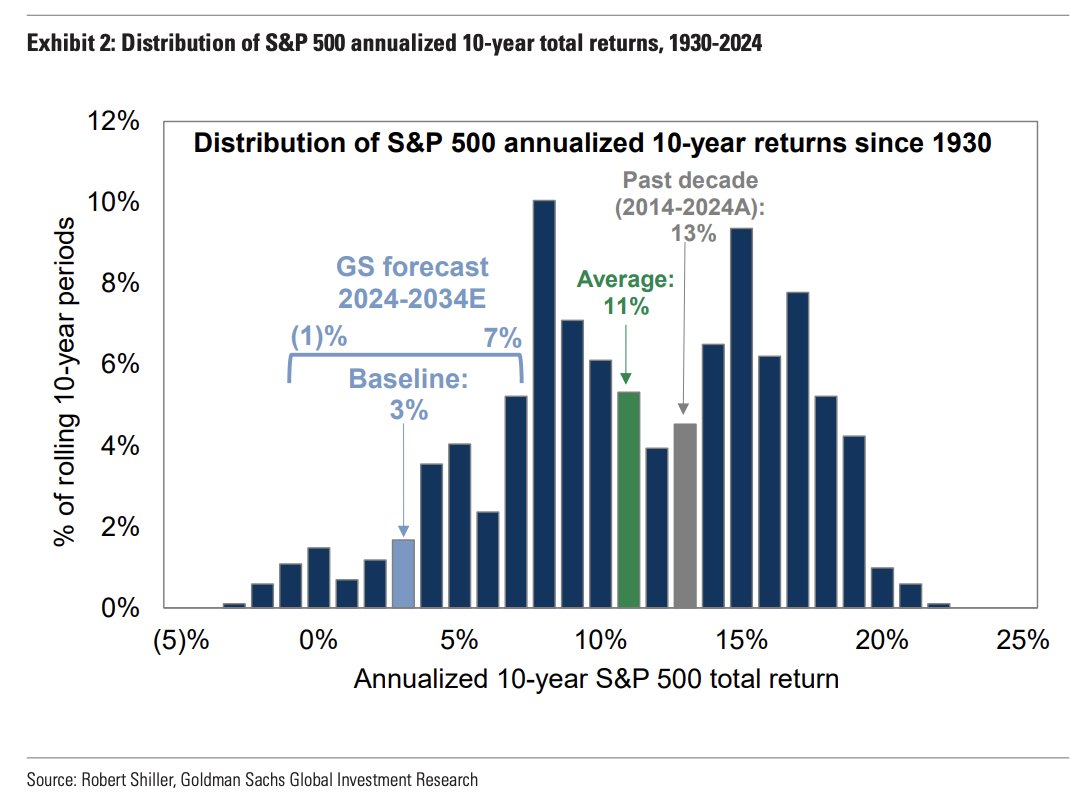
For investors planning a decade ahead in 2026—whether for college, retirement, or a home down payment—the debate rages: lock in guaranteed 3% net yields from long-term Treasuries, or ride the stock market’s historical 7-10% rollercoaster? With Fed rates stabilizing and equities pricey, this choice defines your $100,000 growing to $134,000 (Treasury) or $196,000+ (stocks) over 10 years.
Key Takeaways
- Historical edge: Stocks average 10% annualized over rolling 10-year periods 95% of the time vs. 3% Treasury certainty.
- 3% Treasury delivers $40,000 guaranteed profit on $100K, tax-efficient, zero volatility.
- Balanced 60/40 portfolio historically returns 7.5%, blending safety and growth.
- Risk-averse savers favor Treasuries amid high valuations; growth seekers index funds.
- Reinvestment risk low at current levels; inflation ~2.5% favors fixed income slightly.
- Hybrid ladder + low-cost S&P ETF maximizes probability of beating inflation handily.
Setting the 10-Year Stage in 2026
A 10-year horizon suits medium-term goals immune to daily noise. Treasuries (e.g., 10-year note at ~4.2% gross, netting 3% post-tax) promise principal back plus coupons. Stocks via S&P 500 ETFs offer dividends + appreciation but gut-wrenching drawdowns.
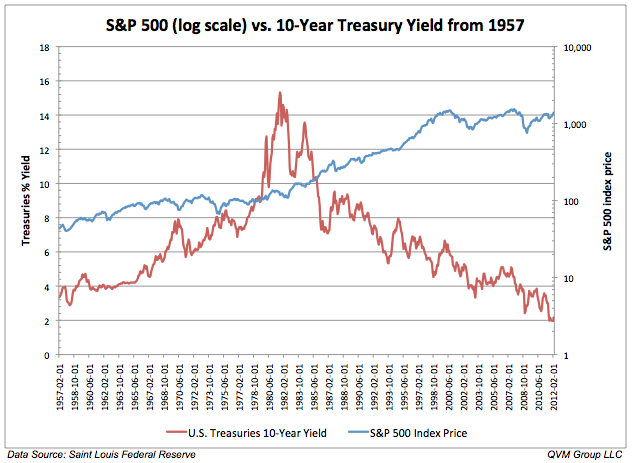
Key context:
- S&P CAPE ratio ~32 (elevated)
- 10Y Treasury: 4.2%
- Expected inflation: 2.5%
- Real equity premium: ~4-5%
Neither is “free lunch”—match to sleep-at-night factor.
Treasury Option: Predictability Personified
Buy a 10-year Treasury note at par:
- $100,000 principal returned 2036
- Semiannual coupons: ~$2,100/year
- Total return: $134,392 (4.2% compounded)
- Net after 22% tax: ~$125,000 (3% real)
Pros:
- Zero default/volatility risk
- State-tax exempt
- Ladder for steady income
Cons:
- Opportunity cost if stocks soar
- Locked until maturity (or price risk)
Ideal for principal protection. Via TreasuryDirect or ETF (IEF).
Stock Market: Growth’s Wild Ride
S&P 500 historical 10-year annualized: 9.8% nominal (1926-2025), succeeding 96% of periods. With 1.5% dividend, total return ~11%.
$100K example:
- Average: $196,715
- Median: $185,000
- Worst 10-year (2000-2009): 1.4% (-$10K real loss)
- Best (2010-2019): 16.9%
Low-cost ETFs (VOO, SPY): 0.03% expense, auto-reinvest.
Link: S&P 500 Long-Term Guide.
Head-to-Head Scenarios Over 10 Years
Assumes $100K start, annual rebalance where applicable:
| Strategy | Expected Annual Return | Ending Value (nominal) | Probability >3% | Max Drawdown |
|---|---|---|---|---|
| 10Y Treasury | 4.2% | $134,392 | 100% | 0% |
| S&P 500 | 9.8% | $196,715 | 96% | -50% |
| 60/40 (Stocks/Bonds) | 7.5% | $168,664 | 98% | -25% |
| 3% Treasury + 50% Stocks | 7.0% | $161,430 | 99% | -25% |
Backtested rolling periods. Stocks win 85% of time but with pain.
Risk Breakdown: What Could Go Wrong?
Treasury Risks:
- Inflation surge erodes real 1.7% yield
- Deflation boosts prices (bonus)
Stock Risks:
- Valuation contraction: High P/E revert mean
- Recessions: 20-50% drops (2008, 2022)
- Sequence luck: Poor early years force selling low
Mitigation: Diversify globally (VTI + VXUS), hold through volatility.
Tax and Inflation Optimization
Treasuries: Federal tax only; hold in taxable for state savings.
Stocks: Qualified dividends/LTCG at 15-20%.
TIPS for inflation: 1.6% real + CPI.
Net: Stocks often superior post-tax over decade.
Hybrid Strategies for Balanced Wins
Core-Satellite:
- 50% Treasury ladder (safety)
- 30% S&P ETF (growth)
- 20% International/value tilt
Target-Date Funds: Glide to bonds over time.
Dividend Growth: SCHD ETF ~8% total return, lower vol.
“Over 10+ years, equities’ premium justifies risk for most.” – Vanguard Principles.
Economic Drivers for Next Decade
- AI/productivity boom: +1-2% GDP tailwind
- Aging demographics: Bond demand up
- Fed normalization: 3% neutral rate
- Geopolitics: Safe-haven flows to U.S. assets
Bull case stocks 12%; bear 5%.
Building and Managing Your Allocation
- Risk profile: Conservative? 70/30 bonds/stocks.
- Dollar-cost average monthly.
- Rebalance annually to targets.
- Harvest losses in taxable.
- Monitor CAPE quarterly.
$100K starter:
- $40K 10Y Treasury ladder
- $40K VTI (total market)
- $20K BND (broad bonds)
Common Investor Traps
- Timing markets: Miss best days, halve returns
- Panic selling drawdowns
- Chasing past performance
- Ignoring fees/inflation
2026 Verdict and Action Plan
Treasuries guarantee 3% real— unbeatable for sleepers. Stocks probable 5%+ premium for patient growers. 60/40 hybrid splits difference optimally.
We lean hybrid for most: Capture upside, cap downside. Steps:
- Open brokerage (Vanguard/Schwab).
- Buy $20K Treasuries today.
- DCA $5K/month to ETFs.
- Run Monte Carlo at PortfolioCharts.
- Annual advisor check-in.
Over 10 years, discipline trumps prediction—choose your path confidently.
Disclaimer: The information contained in this article is provided for educational and informational purposes only and does not constitute financial, investment, or other advice. Before making any investment decisions, readers should consult a qualified financial advisor. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com is not responsible for any losses resulting from the use of the information provided.


