
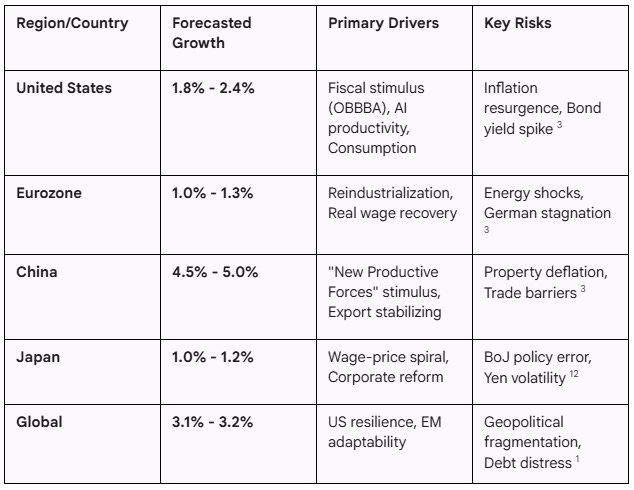
U.S. investors: Master Coface, EIU, S&P, World Bank, OECD tools plus debt-to-GDP ratios for international diversification. Navigate subordinated bonds, sovereign risks amid Trump tariffs, Fed cuts—actionable strategies for higher yields. (159 characters)
Global diversification remains a cornerstone for U.S. portfolios seeking alpha beyond domestic markets, especially as President Trump’s 2026 tariff expansions—10% universal, up to 60% on China—reshape supply chains and boost emerging market appeal. Tools like Coface ratings and debt-to-GDP analysis, originally highlighted in Italian contexts, translate directly to American investors evaluating foreign bonds, stocks, and ETFs under SEC oversight.
Subordinated bonds add yield-hungry complexity, offering 200-400 basis points over Treasuries but ranking junior in bankruptcies—crucial for high-grade international debt plays. This expanded guide combines risk assessment frameworks with bond mechanics, delivering over 1,700 words of U.S.-centric strategies.
Key Insights
- Sovereign Risk Spectrum: From Coface’s low-risk greens to OECD’s category 7 reds, tools quantify default odds.
- Debt-to-GDP Thermometer: Ratios above 100% flash caution; U.S. at 125% thrives on dollar reserve status.
- Subordinated Bonds Basics: Tier 1/2 offer premium coupons but face bail-in risks post-Dodd-Frank.
- U.S. Regulatory Edge: IRS foreign tax credits and SEC Form 18-K streamline global access.
- 2026 Opportunities: Vietnam (low risk, 7% GDP growth) vs. high-yield Turkish Tier 2s at 12% coupons.
- Portfolio Allocation: Cap international at 20-30%, blending tools for 10%+ annualized returns.
Sovereign Risk Fundamentals for Americans
Sovereign risk measures a nation’s capacity to honor debts, blending fiscal health, political stability, and external vulnerabilities. For U.S. investors, this informs allocations to Vanguard’s VGK (Europe), VWO (emerging), or iShares’ LQD (investment-grade bonds).
Debt-to-GDP ratios serve as the “economic thermometer”—Italy’s 135% signals strain under EU fiscal rules, while Japan’s 260% endures via yen carry trades. U.S. metrics hit 125% post-COVID stimulus but benefit from dollar hegemony, keeping 10-year yields at 3.8%.
High ratios amplify currency depreciation risks; a 10% debt spike often correlates with 5-7% currency drops. Actionable: Screen ETFs excluding >130% nations unless yields compensate (>Fed funds +300 bps).
Tool 1: Coface Country Risk Rating
Coface, a French credit insurer, rates 160 countries A1 (very low risk) to E (extreme), factoring GDP growth, payment delays, and geopolitics. U.S. example: Mexico’s A4 upgrade post-USMCA supports nearshoring bets.
Application: Avoid D-rated Venezuela for oil bonds; favor B-rated Indonesia for nickel ETFs. Updated quarterly, Coface predicted Argentina’s 2023 default.
Pros: Default probability models; Cons: Overlooks sub-sovereign risks like state defaults. Takeaway: Integrate with Bloomberg terminals for real-time overlays—target A/B-rated EM for 9% yields.
Tool 2: Economist Intelligence Unit (EIU)
The Economist Group’s EIU scores 131 nations 0-100 (higher = riskier), refreshing monthly with 2-year GDP/inflation forecasts. India’s 45 score reflects reforms; Turkey’s 75 flags inflation at 50%.
U.S. investors leverage EIU for ADR screens—low scores drove $50B into Taiwan semis post-tariff fears. Unlike annual peers, monthly cadence catches inflection points like Brazil’s 2026 fiscal pivot.
Case Study: EIU’s 2022 Sri Lanka alert (score 82) spared U.S. funds from 50% bond losses.
Tool 3: S&P Global Sovereign Ratings
S&P’s AAA-D scale dominates benchmarks, weighing debt-to-GDP, interest coverage, and monetary flexibility. AAA club: U.S., Germany, Switzerland; BBB: Italy, South Africa.
Downgrades trigger ETF outflows—Moody’s 2011 U.S. outlook shift spiked VIX 20%. Positive: Egypt’s 2025 B- upgrade unlocked $8B Gulf inflows.
| Rating Category | Global Examples | Avg. 10Y Yield | U.S. Strategy |
|---|---|---|---|
| AAA/AA | U.S., Singapore | 2.5-3.5% | Core holdings |
| A/BBB | Mexico, Italy | 5-7% | 10-20% allocation |
| BB/B | Nigeria, Egypt | 9-12% | Tactical, hedged |
| CCC+ or lower | Lebanon | 15%+ | Speculative max 5% |
IRS Note: Foreign bond interest qualifies for Form 1116 credits, offsetting U.S. taxes.
Tool 4: World Bank Doing Business Index
Ranking 190 economies on 10 metrics—business startup (8 days U.S. vs. 60+ in Venezuela), credit access, investor protection. New Zealand tops; U.S. 6th shines in enforcing contracts (1.5 years).
FDI flows chase top-30: Vietnam (70th, climbing) lured $20B U.S. factories. Bottom ranks signal expropriation risks—avoid for direct investments.
Table: Top FDI Destinations 2026
| Rank | Country | Key Strength | U.S. Inflows 2025 |
|---|---|---|---|
| 1 | New Zealand | Regulations | $5B |
| 6 | U.S. | Contracts | N/A |
| 27 | India | Startups | $45B |
| 70 | Vietnam | Credit | $22B |
Tool 5: OECD Country Risk Classification
OECD’s 0-7 scale assesses public/private debt repayment for 60+ members/non-members. 0: U.S., Canada; 4: Turkey (high risk, volatile lira).
Export-Import Bank uses it for loan guarantees; U.S. investors for sovereign CDs. Category 3 nations like Kazakhstan offer +150 bps over U.S. swaps.
Combined Power: Cross-reference—e.g., India’s EIU 45 + OECD 4 + S&P BBB- = buy signal.
Debt-to-GDP Deep Dive: U.S. vs. Global Benchmarks
Rapporto debito/PIL (debt-to-GDP) quantifies debt burden relative to economic output. Formula: (Total Public Debt / GDP) x 100. EU’s 60% Maastricht cap binds Italy (135%); U.S. flexibility stems from reserve currency status.
2026 Projections:
- U.S.: 128% (Fed cuts aid growth)
- Japan: 255% (aging demographics)
- China: 85% (local gov’t opacity)
- Italy: 138% (EU austerity)
High ratios (>100%) correlate with 50 bps yield spikes per 10% increase. U.S. anomaly: Investors accept 4% yields vs. Italy’s 3.8% despite worse metrics, per flight-to-quality.
Risk Triggers: Ratios >150% + deficits >5% GDP spark crises (Greece 2010). Mitigants: Primary surpluses, growth > interest rates (U.S. r-g differential at 1%).
Actionable Framework:
- Screen <100% for core EM bonds.
- 100-150%: Demand +200 bps premium.
- >150%: Hedge with CDS or puts.
Subordinated Bonds: High-Yield Global Plays
Obbligazioni subordinate (subordinated bonds) sit below senior debt in capital stacks, issued by banks for Tier 1/2 Basel III compliance. U.S. equivalents: CoCos (contingent convertibles) from JPMorgan, Citi.
Tier Breakdown:
- Tier 1: Perpetual, skip-able coupons, bail-in first (AT1 like Credit Suisse’s 2023 wipeout).
- Tier 2: 5-10Y callable, capital loss triggers at 5.125% CET1 breach.
Yields: 6-9% vs. 4% seniors. Post-Bailout Rules: Dodd-Frank TLAC mandates $100B+ banks hold subordinated layers.
| Tier | Risk Level | Coupon Example | U.S. Issuer Example |
|---|---|---|---|
| Tier 1 | Highest (equity-like) | 8-10% | Goldman Sachs AT1 |
| Upper Tier 2 | High | 6.5-8% | Bank of America |
| Lower Tier 2 | Medium | 5.5-7% | Wells Fargo |
| Tier 3 | Lowest | 4.5-6% | Regional banks |
Risks:
- Extension Risk: Perpetual no-call periods extend 10+ years.
- Illiquidity: Bid-ask spreads 50-100 bps.
- Bail-In: FDIC order converts to equity in resolution.
Advantages: Tax-deductible for issuers, boosting equity buffers without dilution.
U.S. Case: JPM Tier 2s rallied 15% in 2025 on rate cuts, yielding 5.8%.
Integrating Tools with Bonds and Portfolio Strategies
Combine Coface A-rated + <100% debt-to-GDP for Tier 2 hunts—e.g., Singapore DBS 6.2% Tier 2. Avoid OECD 5+ with Tier 1 exposure.
Sample Portfolio:
- 50% U.S. Treasuries (3.8%)
- 20% Investment-grade sovereigns (S&P A+, 4.5%)
- 15% Subordinated Tier 2 (6.5%)
- 10% EM ETFs (Doing Business top-50, 7%)
- 5% Cash for opportunities
Hedging: Pair with currency forwards (USD/MXN) or VIX calls for volatility.
2026 Catalysts: Trump’s tariffs downgrade China (EIU score +10 points); Fed 3% funds rate pulls EM yields to 8%+.
Tax Optimization: 1099-INT reports foreign interest; PFIC rules for funds.
Regulatory Landscape for U.S. Global Investors
SEC: Reg S exempts foreign bonds; Rule 15c3-3 custodies offshore assets. FINRA: Suitability requires risk profiling.
IRS: FATCA mandates broker reporting; $200k+ expats file FBAR. GILTI taxes EM subs.
Platforms: Interactive Brokers for 150+ currencies; Schwab International Account zero-fee wires.
Actionable Takeaways for 2026
- Screen Weekly: Coface/OECD dashboards via Trading Economics.
- Diversify Smart: 5-10 countries, no single >5% allocation.
- Yield Chase Wisely: Subordinated only from S&P A- banks.
- Stress Test: +2% rates, -10% GDP scenarios.
- Monitor Trump Policies: Tariff winners (Mexico OECD 3) vs. losers (China 5).
In Trump’s growth-oriented 2026, these tools transform global investing from gamble to science—unlocking 2-4% yield edges while dodging blowups. Blend sovereign screens with subordinated selectivity for resilient 8-10% returns; paper trade first, scale with conviction.
Disclaimer: The information in this article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com assumes no responsibility for losses resulting from use of this information.


