
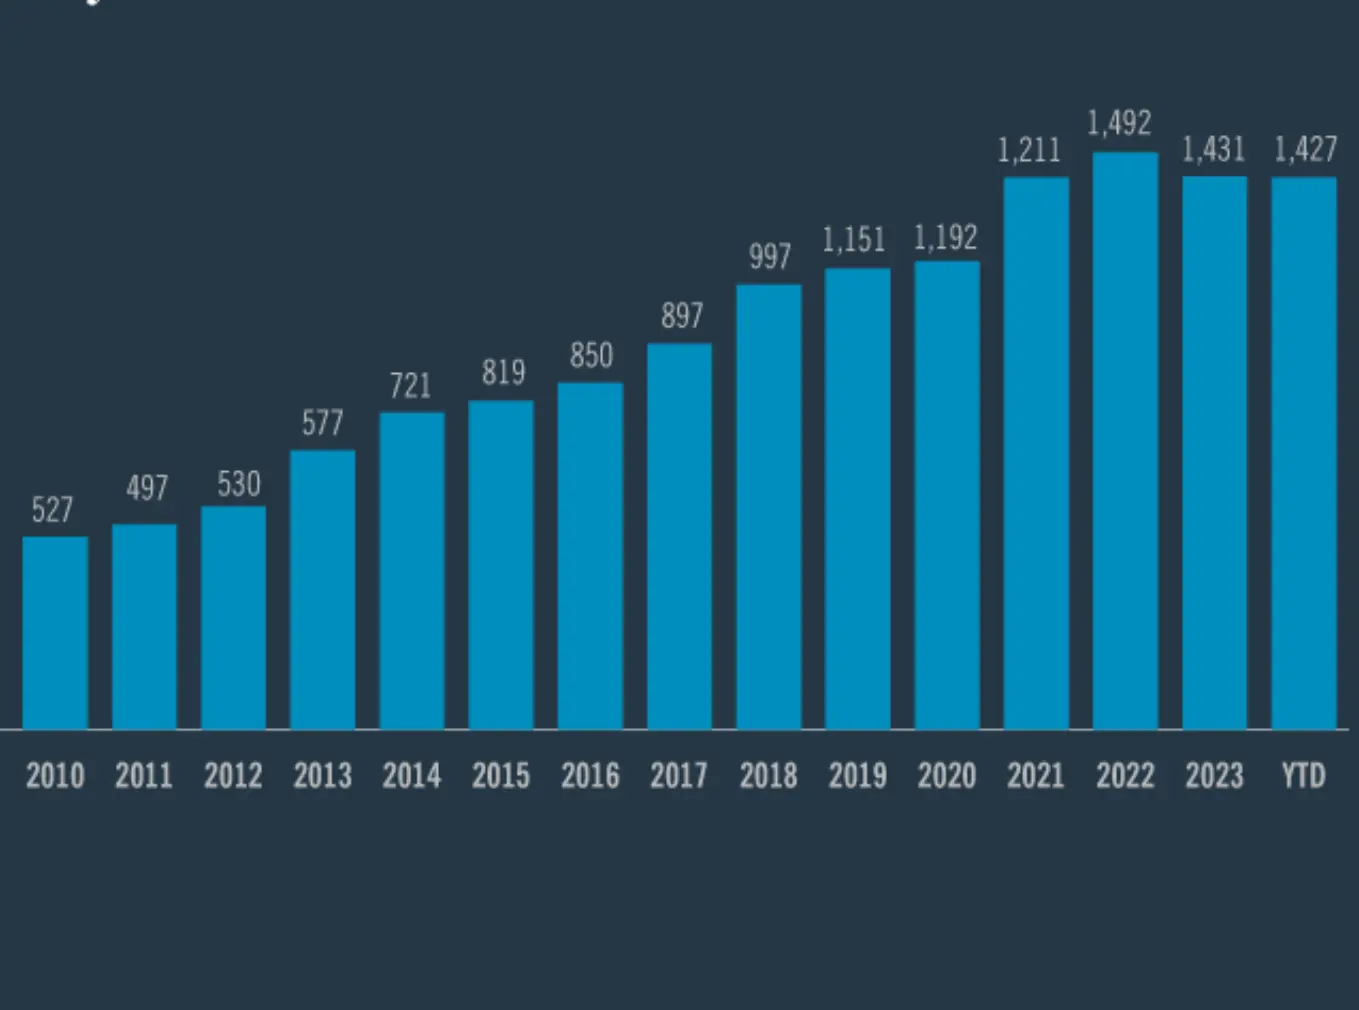
An Asset-Backed Security (ABS) is a bond or note created by pooling together financial assets—like auto loans, credit card receivables, or student loans—and selling the rights to the cash flows to investors. In essence, it transforms illiquid loans into tradable securities.
In the United States, the ABS market remains a cornerstone of the credit system, supplying funding for consumers and yield for investors. As of 2025, it represents over $2.3 trillion in outstanding issuance, according to the Federal Reserve.
When banks lend, they create credit. When they securitize, they create liquidity.
Key Insights
- Asset-Backed Securities (ABS) are bonds backed by pools of consumer or business loans.
- They allow lenders to transfer credit risk and free up capital for new lending.
- Investors receive monthly or quarterly payments derived from loan cash flows.
- ABS differ from Mortgage-Backed Securities (MBS) because they’re not tied to real estate.
- The market is regulated by the SEC, the Federal Reserve, and the FDIC.
How Asset-Backed Securities Work
The ABS process starts when an originator—such as a bank or finance company—bundles hundreds or thousands of similar loans into a special purpose vehicle (SPV).
This SPV issues bonds to investors, backed by the loan payments it receives. The SPV isolates the loans from the originator’s balance sheet, protecting investors if the lender goes bankrupt.
Example:
A bank packages $500 million in auto loans into an SPV, which issues three classes of ABS:
- Senior tranche (AAA): Lower yield, first in line for payment.
- Mezzanine tranche (BBB): Moderate yield, absorbs some risk.
- Equity tranche: Highest yield, last to be repaid.
This tranching structure tailors risk and reward to investor appetite.
Common Types of U.S. ABS
| Type | Underlying Assets | Typical Yield (2025) |
|---|---|---|
| Auto Loan ABS | Vehicle financing contracts | 4–6% |
| Credit Card ABS | Card receivables | 3–5% |
| Student Loan ABS | Federal or private education loans | 5–7% |
| Equipment ABS | Industrial and tech equipment leases | 6–8% |
| Consumer Loan ABS | Personal or fintech loans | 7–10% |
Auto and credit card ABS remain the most liquid and widely held among U.S. investors.
Why Banks and Investors Use ABS
For Banks and Lenders
- Capital Relief: Selling loans frees balance-sheet capacity.
- Liquidity: Turns long-term assets into cash.
- Risk Transfer: Moves credit exposure to investors.
For Investors
- Yield Enhancement: Higher returns than Treasuries or corporate bonds.
- Diversification: Exposure to consumer credit performance.
- Predictable Cash Flow: Payments tied to structured schedules.
The FDIC’s Quarterly Banking Profile highlights that securitization remains a key funding channel for nonbank lenders, especially in auto and fintech sectors.
Regulation and Transparency
Following the 2008 financial crisis, ABS issuance became tightly regulated.
The SEC’s Regulation AB II mandates detailed disclosure of loan-level data, credit scoring, and servicing standards.
The Federal Reserve’s Financial Stability Overview confirms that post-crisis reforms increased transparency and reduced systemic contagion from securitized products.
Today, all ABS issuers must retain at least 5% of the credit risk (“skin in the game”) to align interests with investors.
ABS vs. Mortgage-Backed Securities (MBS)
| Feature | ABS | MBS |
|---|---|---|
| Collateral | Auto, card, student, consumer loans | Residential or commercial mortgages |
| Prepayment Risk | Lower | High (early refinancing) |
| Market Size (U.S.) | ≈ $2.3 trillion | ≈ $12 trillion |
| Government Support | Limited | Strong (Fannie Mae, Freddie Mac) |
| Average Duration | 2–5 years | 5–30 years |
ABS markets tend to be shorter-term and less rate-sensitive, making them attractive during volatile interest rate cycles.
Pricing and Risk Factors
ABS yields depend on:
- Credit quality of borrowers
- Collateral type and vintage
- Payment delinquencies and charge-offs
- Prepayment speed
- Macroeconomic factors such as employment and inflation
In 2025, delinquency rates on auto ABS rose modestly to 2.4%, per Morningstar’s U.S. Credit Market Outlook, but remained below long-term averages—suggesting stability in consumer balance sheets despite tighter credit conditions.
Example: Auto Loan ABS
A finance company issues $1 billion in AAA-rated auto ABS paying 5% annual yield.
If U.S. auto borrowers remain current, investors receive timely payments of principal and interest.
If defaults rise, the subordinated tranches absorb losses first—protecting senior investors.
Such structures make ABS resilient under moderate stress scenarios, provided underlying data remains transparent.
How Investors Access ABS
Institutional investors—such as insurance firms, pension funds, and hedge funds—dominate the ABS market.
However, retail exposure is growing through:
- ABS mutual funds and ETFs
- Money market funds holding short-duration tranches
- Structured credit products offered by brokers
Morningstar reports that ABS ETFs saw inflows of $18 billion in 2024 as investors sought stable yields amid high interest rates.
Relationship with Credit Default Swaps (CDS)
ABS tranches can be hedged using CDS instruments, which transfer credit risk to counterparties.
As discussed in Credit Default Swaps Explained: How Investors Trade and Hedge Credit Risk in 2025, these instruments let institutions fine-tune exposure without selling the securities themselves.
Systemic Importance
The Federal Reserve monitors securitization trends as part of financial stability oversight.
While today’s ABS market is far smaller and safer than the pre-2008 MBS market, rapid growth in subprime consumer lending remains a watchpoint.
Higher delinquency in credit card and auto ABS could transmit stress to funding markets if unemployment rises.
Outlook for 2025
Analysts expect steady ABS issuance through 2025 as consumer credit expands and banks offload balance-sheet risk.
Morningstar forecasts 4–5% annual growth in issuance volume, led by auto and fintech platforms.
Technology-driven transparency and blockchain-based loan verification systems are improving trust between issuers and investors.
Conclusion
Asset-Backed Securities turn everyday consumer loans into global investments.
They create liquidity, distribute risk, and power the U.S. credit engine—but depend on careful structuring and transparency.
“Securitization doesn’t remove risk; it reallocates it.”
For informed investors, ABS can offer consistent income and portfolio diversification—provided they understand what lies beneath the surface.
Disclaimer:
The information in this article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com assumes no responsibility for losses resulting from use of this information.


