
February 5 brings Amazon earnings, but January jobs report’s wage growth and participation data hold keys to Fed policy and 10% S&P swings. Investor playbook for data-driven trading.
Wall Street fixates on Amazon’s February 5th after-hours earnings—consensus expects $181B revenue, AWS growth, and AI capex guidance—yet the real market catalyst drops 8:30 AM ET the same morning: January’s Bureau of Labor Statistics employment report. While AMZN might move 8-12% post-earnings ($180B market cap shift), the jobs data historically drives 2-5% S&P 500 swings affecting $2.5 trillion across all sectors by determining whether the Federal Reserve resumes rate cuts or pivots hawkish. Wage growth accelerating above 4.5%, unemployment dropping below 4.0%, or labor force participation surging past 63.5% could each trigger bond yield spikes to 4.8-5.0% and equity multiple compression, regardless of corporate earnings strength. This tactical guide, adapting European employment analysis to U.S. monetary policy dependencies, breaks down the three jobs report components markets will trade, explains why Amazon’s results become secondary in the macro context, and provides hour-by-hour positioning strategies for February 5th’s split-narrative day.
Key Insights
- Jobs report at 8:30 AM EST drives Fed expectations; Amazon at 4:00 PM becomes secondary
- Wage growth >4.5% signals persistent inflation, kills rate cut hopes, triggers -2 to -3% S&P selloff
- Nonfarm payrolls >250K with unemployment <4.0% = hawkish repricing, 10Y yields to 4.8%
- Labor force participation >63.5% = productivity boom narrative, bullish for equities if wages contained
- Amazon’s $180B revenue beat matters less than AWS margins and AI infrastructure spending outlook
- Trading playbook: Hedge pre-jobs (7-8:30 AM), trade the number (8:30-10 AM), reassess Amazon (4-5 PM)
- Portfolio positioning: Rate-sensitive sectors (REITs, utilities) most vulnerable to hot jobs data
Why January Jobs Data Trumps Amazon Earnings
Markets operate on hierarchical information: Macro indicators (Fed policy) determine discount rates for all assets, while micro earnings (even $2T mega-caps) affect individual stock valuations. The January jobs report influences Fed’s March 18-19 FOMC meeting decisions, where rate cut probabilities shifted from 75% (December 2025) to 45% (February 2026) per CME FedWatch. Another strong report crushes cut hopes entirely, repricing the entire equity market downward.
Historical precedent: February 2, 2024 jobs report (+353K vs. 185K expected) triggered a 1.6% S&P decline within 2 hours despite strong earnings from GOOGL and MSFT that same week. May 3, 2024 (+272K) caused 2.3% drop. August 2, 2024 (+114K, below 175K estimate) sparked 8% decline over 3 days (though yen carry trade amplified). Pattern: Surprises >75K from consensus move markets 1.5-3% same-day.
Amazon context: Even a 10% AMZN stock move ($2,000 → $2,200) affects S&P 500 by only 0.15% given its 3.2% index weight. Jobs data affects 100% of constituents via discount rate changes. Macro > Micro dominance.
February 5 consensus estimates:
- Nonfarm payrolls: +165K (range: 120K to 210K)
- Unemployment rate: 4.1% (prior 4.1%)
- Average hourly earnings (wage growth): +0.3% MoM, +3.9% YoY
- Labor force participation: 63.3% (unchanged)
Market-moving thresholds:
- Payrolls >225K = hawkish shock
- Unemployment <4.0% = tightening labor market concern
- Wages >4.5% YoY = inflation persistence proven
- Participation >63.5% = game-changer positive (more workers = less inflation pressure)
Component #1: Wage Growth—The Fed’s Inflation Obsession
Average hourly earnings growth determines services inflation, which comprises 60% of core CPI. Fed Chair Powell stated January 29th: “We need to see wage growth moderate to 3.5% to achieve 2% inflation sustainably.” Current 3.9% YoY (December) remains above target. January report’s 0.3% MoM equals 3.6% annualized—acceptable. Trigger: 0.4% MoM (4.8% annualized) or 4.2% YoY signals acceleration.
Sector breakdown risk: Healthcare wages +5.2%, leisure/hospitality +4.8%, government +4.5%—these dominate employment. Tech layoffs (15K announced January at Microsoft, Google, Amazon) lower overall average but don’t affect consumer-facing inflation. Net: Aggregate number matters more than composition.
U.S. specifics: Unlike Europe’s coordinated wage bargaining, U.S. wages adjust via market mechanisms monthly. Trump’s immigration policies (deportations reducing labor supply) could push wages higher structurally—markets haven’t priced this 2026-2027 risk fully. Inflation passthrough: 1% wage growth above trend adds 0.4% to core CPI with 3-month lag (Fed research).
Trading implication: Wages >4.5% = sell duration (TLT puts), buy financials (KBE) on steeper curve expectations. Wages <3.5% = buy growth (QQQ), Fed cuts back in play.
Component #2: Unemployment Rate—The Sahm Rule Watch
Unemployment at 4.1% sits near cycle lows but 0.5% above 2023’s 3.6% trough. The Sahm Rule recession indicator triggers when 3-month moving average rises 0.5% above prior 12-month low—currently at 0.43%, dangerously close. Paradox: Too-low unemployment (sub-4.0%) signals inflation risk (tight labor); rising unemployment (4.5%+) signals recession risk. Sweet spot: 4.0-4.2%.
January scenarios:
- 3.9%: Hawkish, implies 250K+ jobs created, Fed concerns reignite, -1.5% S&P
- 4.1%: In-line, market shrugs, focus shifts to wages and Amazon
- 4.3%: Dovish surprise, recession fears, +1% S&P initially but credit spreads widen
U-6 underemployment: Broader measure including part-timers wanting full-time work, currently 7.7%. Rising U-6 with stable headline unemployment suggests labor market weakening beneath surface—happened Q4 2007 before crisis. Monitor: BLS Table A-15.
Demographic considerations: Baby boomer retirements reduce labor force naturally; headline unemployment less meaningful. Adjust for prime-age (25-54) employment-population ratio, currently 80.9% (strong). Above 81% = robust; below 80.5% = concerning.
Component #3: Labor Force Participation—The Game-Changer
Participation rate measures % of working-age population employed or seeking work, currently 63.3% versus 63.4% pre-COVID. Each 0.1% increase adds ~260K workers—expanding supply without demand creates disinflationary pressure (Fed’s dream scenario). Catalyst: January data at 63.5% would be biggest monthly jump since 2022, signaling:
- Disabled workers returning (long-COVID recoveries)
- Early retirees un-retiring (savings depleted, inflation-driven)
- Immigration effects (pre-deportation surge in labor force entries)
Bull case interpretation: More workers = higher GDP potential without inflation = equity multiple expansion. S&P target rises to 6,500 (from 6,100) on productivity boom narrative. Reality check: Takes 6-12 months to confirm trend; single-month moves volatile.
Correlation analysis: Participation up + unemployment stable + wages moderate = Goldilocks. Any 2 of 3 = acceptable. All 3 together = +3 to +5% S&P rally over following month.
| Jobs Report Scenario | Payrolls | Unemployment | Wages YoY | Participation | S&P Reaction | 10Y Yield |
|---|---|---|---|---|---|---|
| Hawkish Nightmare | +250K | 3.9% | 4.5% | 63.3% | -2.5% | +15bps |
| Modest Hot | +200K | 4.1% | 4.1% | 63.3% | -1% | +8bps |
| Goldilocks | +165K | 4.1% | 3.8% | 63.5% | +1.5% | -5bps |
| Cooling | +120K | 4.3% | 3.6% | 63.2% | +0.5% | -10bps |
| Recessionary | +75K | 4.5% | 3.4% | 63.0% | -1.5% | -15bps |
External: Bureau of Labor Statistics Employment Situation
Amazon Earnings: What Actually Matters
Consensus expects Amazon Q4 2025 revenue $181.5B (+9% YoY), EPS $1.48, operating income $19.5B. Market focus areas:
1. AWS Growth Acceleration: Q3 was +19% YoY to $27.5B, reaccelerating from 12% in Q1. AI workloads (Bedrock, Trainium chips) driving enterprise migrations. Bull case: Q4 >22% growth, guidance for 25%+ in 2026 = stock +8 to +10%. Bear case: Slowing to 16-18% on Microsoft/Google competition = -5 to -8%.
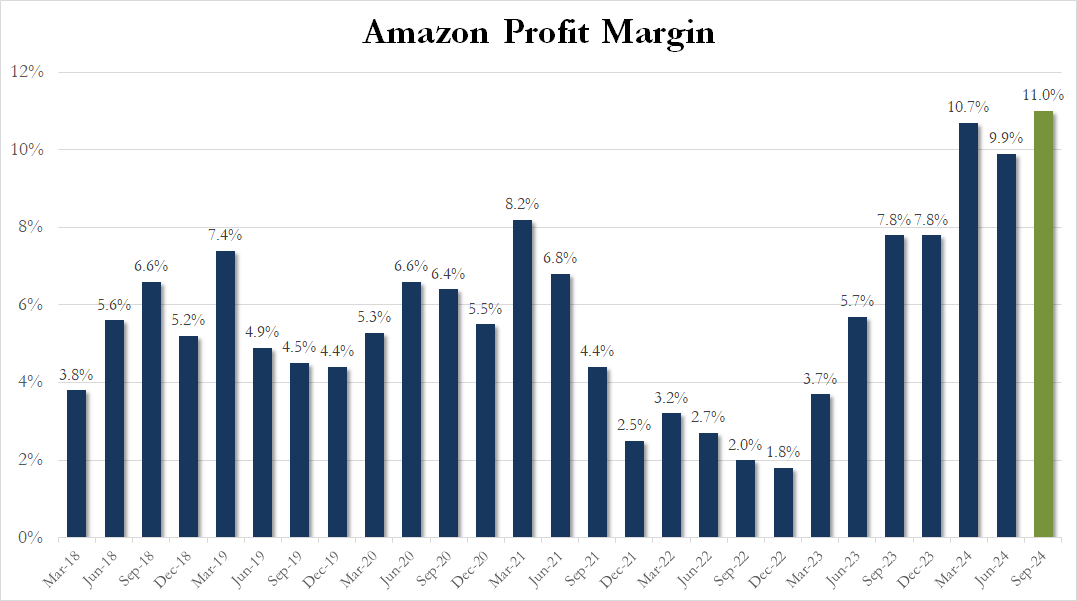
2. Operating Margin Expansion: Q3 was 11%, up from 7.8% in 2023. Efficiency gains (regionalization, automation) + AWS mix shift (70% margins) target 12-13%. Miss below 10.5% = concerns about retail profitability, ad business slowdown.
3. AI Capex Guidance: 2025 capex was $75B, mostly data centers. 2026 guidance expected $85-95B. Higher than $100B signals aggressive AWS positioning (bullish long-term, concerning for near-term FCF). Below $80B = demand worries.
4. Advertising Revenue: $14.3B Q3 (+19%), third-largest platform behind Google/Meta. Slowing to <15% suggests consumer pullback. Accelerating to >22% = retail strength.
Historical earnings moves: AMZN averages 6.8% post-earnings move (absolute value) over past 8 quarters. Largest: +12% (Q1 2024 beat), -8% (Q4 2023 miss). Options market implies 7.5% move (straddle pricing).
Why it’s secondary February 5th: Earnings released 4:00 PM, markets closed. Futures trade 6:00 PM onward, but liquidity thin until Asia open. Jobs data at 8:30 AM sets tone for entire day; by 4 PM, positioning already done. AMZN moves itself and cloud peers (MSFT, GOOGL) in after-hours, but broad market awaits next day’s open to fully react.
Hour-by-Hour Trading Playbook for February 5th
7:00-8:29 AM: Pre-Jobs Hedging
- Action: Markets nervous; VIX typically rises 5-8% pre-data
- Positioning: Close 20% long exposure if heavily bullish, or add 5% hedges (SPY puts)
- Futures watch: ES (S&P futures) range tightens; breakout direction post-8:30 determines day
8:30 AM: Data Release
- Immediate reaction (8:30:00-8:30:15): Algos parse headlines (payrolls first, then unemployment, wages last)
- Bond market leads: 10Y yield moves instantly; if +10bps, stocks will follow down in 30-60 seconds
- VIX spike: Hot data pushes VIX +15-25% in 5 minutes
8:30-9:00 AM: Initial Interpretation
- Analyst commentary floods (Bloomberg, CNBC): “This supports/undermines Fed cuts”
- Sector rotation: Rate-sensitive (REITs, utilities) fall hardest on hawkish data; financials rise on steeper curve
- Fade or follow: If knee-jerk reaction >2%, often partially reverses by 10 AM (overreaction); <1.5% tends to persist
9:30 AM: Cash Market Open
- Volume surge: First 30 minutes = 15% of daily volume
- Confirmation or reversal: Futures direction from 8:30 either confirmed (follow-through) or reversed (fade)
- Actionable: If jobs data clearly hawkish and S&P down 1.5%, add hedges targeting -2.5% day
10:00 AM: ISM Services PMI Release
- Secondary data: January ISM Services (consensus 54.2) can amplify or contradict jobs message
- Prices Paid sub-index: Above 60 = inflation concerns layer onto wage fears
- Employment sub-index: Correlation check with BLS data
10:00 AM-4:00 PM: Drift and Positioning
- Typical pattern: Initial reaction holds through lunch; 2-3 PM sees repositioning for Amazon
- Options activity: AMZN straddles/strangles peak volume 2-4 PM
- Cash raise: Some reduce exposure ahead of AMZN binary event
4:00 PM: Amazon Earnings Release
- Immediate headline scan: Revenue, EPS, AWS growth (in that order)
- Stock reaction: 4:01-4:15 PM volatile on algo parsing; 4:15-5:00 PM stabilizes as humans read full release
- Conference call: 5:00 PM (5:30 PM ET), guidance details matter most
5:00-8:00 PM: After-Hours Reassessment
- AMZN move implications: If +8%, lifts MSFT, GOOGL; if -8%, drags cloud sector
- Futures response: ES typically moves 0.3-0.5% in sympathy with AMZN direction
- Next day setup: Combine jobs data + AMZN result for February 6th open positioning
Scenario Analysis: Combined Outcomes
Scenario A: Hawkish Jobs + Amazon Beat
- Jobs: +240K, wages 4.3%, unemployment 4.0%
- AMZN: Revenue $184B, AWS +24%, raise guidance
- Market reaction: Conflicted—bonds sell off hard (10Y to 4.75%), growth stocks mixed (higher rates hurt but earnings strong), rotation to value/financials. Net: S&P -1%, Nasdaq -0.5%, DJIA +0.3%. AMZN +6% not enough to offset rate drag.
Scenario B: Goldilocks Jobs + Amazon Beat
- Jobs: +165K, wages 3.8%, participation 63.5%
- AMZN: Same strong beat
- Market reaction: Risk-on euphoria. S&P +2%, Nasdaq +2.5%, AMZN +10%. Fed cuts back in play (June), soft landing confirmed. Best outcome.
Scenario C: Weak Jobs + Amazon Miss
- Jobs: +110K, unemployment 4.3%, wages 3.5%
- AMZN: Revenue $178B, AWS +17%, cautious guidance (consumer slowing)
- Market reaction: Stagflation fears—growth slowing but not enough for aggressive Fed cuts (inflation still 2.6%). S&P -2.5%, credit spreads widen, flight to Treasuries (10Y to 4.2%). Worst outcome short-term, though Fed cuts eventually support.
Scenario D: Hot Jobs + Amazon Miss
- Jobs: +230K, wages 4.4%
- AMZN: Disappoints
- Market reaction: Maximum pain—no Fed relief, earnings concerns, S&P -3%, Nasdaq -4%, AMZN -10%. Defensive positioning into February vindicated.
Probability weights (subjective):
- A: 25%
- B: 35% (base case)
- C: 20%
- D: 20%
Sector-Specific Vulnerabilities and Opportunities
Most Vulnerable to Hot Jobs Data (avoid/short):
- REITs (VNQ): -3 to -4% on 20bps yield rise, rate-sensitive
- Utilities (XLU): -2 to -3%, similar duration risk
- High-multiple growth (ARK): -4 to -5%, discount rate compression
- Long-duration Treasuries (TLT): -1.5 to -2%
Beneficiaries of Hot Data:
- Financials (XLF): +1 to +2% on steeper yield curve, NIM expansion
- Energy (XLE): +0.5 to +1%, strong growth correlates with demand
- Value stocks (VTV): Outperform growth by 1-2%
Amazon-Correlated Plays:
- Cloud competitors: MSFT (55% correlation), GOOGL (60%)
- E-commerce: SHOP (40%), EBAY (25%)
- Semiconductors: NVDA (35% on AI capex implications)
Safe havens if both disappoint:
- Gold (GLD): +1 to +2% on risk-off
- Staples (XLP): -0.5% (defensive but not immune)
- Cash/T-bills: Preserve capital
Options Strategies for February 5th
Strategy 1: Straddle on Macro Volatility
- Setup: Buy SPY $605 straddle (ATM), Feb 7 expiry, cost $12 (2% of stock)
- Payoff: Profitable if SPY moves >2% either direction by Friday
- Risk: Time decay if data in-line and low volatility
Strategy 2: Amazon Earnings Play
- Bull call spread: Buy AMZN $2,050 call, sell $2,150 call, Feb 14 expiry, cost $35, max gain $65 (186% return)
- Bear put spread: Buy $1,950 put, sell $1,850 put, cost $32, max gain $68 (213%)
- Risk: Defined to premium paid
Strategy 3: Pairs Trade
- Long financials (XLF calls) + Short utilities (XLU puts) to capture rate-driven rotation
- Delta-neutral: Size to offset, profit from spread widening
Strategy 4: Volatility Collapse
- Sell VIX Feb calls at $22 strike if expecting calm data (VIX currently 18)
- Risk: Unlimited if data shocks, size small (1% portfolio)
Why Markets Misallocate Attention
Behavioral finance explains Amazon fixation: Narrative bias (tech earnings stories compelling), availability heuristic (recent earnings season salient), action bias (trading individual stocks feels productive vs. waiting on macro data). Institutional investors know macro dominates, but retail fixates on AMZN.
Media amplification: CNBC dedicate 15 minutes to Amazon preview, 5 minutes to jobs data. Google Trends: “Amazon earnings” searches 4x “jobs report” week of Feb 3-5. Yet professional traders (CME futures positioning, options flow) reveal macro hedging dominance.
Opportunity: Mismatch creates edge for those prioritizing 8:30 AM over 4:00 PM.
Historical February Jobs Reports: Seasonal Patterns
January employment data (released early February) exhibits seasonal quirks:
- Holiday hangover: December retail hiring reverses, showing 50-75K less payrolls
- Weather effects: Severe winters reduce construction (-20K typical), though 2026 mild
- Annual benchmark revisions: BLS adjusts prior-year data, often surprises (2024 revised down 818K total)
2022-2025 February releases:
- Feb 2022: +678K (massive beat), S&P +0.5%
- Feb 2023: +311K (beat), S&P -1.1% (inflation concerns)
- Feb 2024: +353K (big beat), S&P -1.6%
- Feb 2025: +225K (in-line), S&P +0.8%
Pattern: Beats often punished (inflation worries), misses rewarded if not recessionary. February 2026 likely continues this dynamic.
Final Positioning Recommendations
Conservative (capital preservation):
- 50% cash/T-bills earning 5.3%
- 30% core equities (SPY), hedge with 5% puts
- 20% bonds (AGG, short duration)
- Result: Downside capped at -3%, upside +1%, sleep well
Moderate (balanced risk):
- 60% equities (40% SPY, 10% XLF, 10% XLE)
- 20% bonds
- 10% gold
- 10% cash
- Result: Capture 70% of upside, 60% of downside
Aggressive (maximize alpha):
- 70% equities (20% AMZN, 20% cloud/tech, 30% SPY)
- 20% leveraged plays (options, 2x ETFs)
- 10% hedges (VIX calls)
- Result: +5% upside scenario B, -4% downside scenario D
Universal rule: Review positioning 8:31 AM post-data; don’t be stubborn. Markets provide new information—adapt.
February 5th encapsulates modern market dynamics: Macro policy (Fed) outweighs micro fundamentals (Amazon) in determining broad outcomes, yet retail attention inverts priorities. Sophisticated investors trade the 8:30 AM jobs number, let algos handle 4:00 PM earnings, and profit from the gap.
Disclaimer: The information in this article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com assumes no responsibility for losses resulting from use of this information.


