
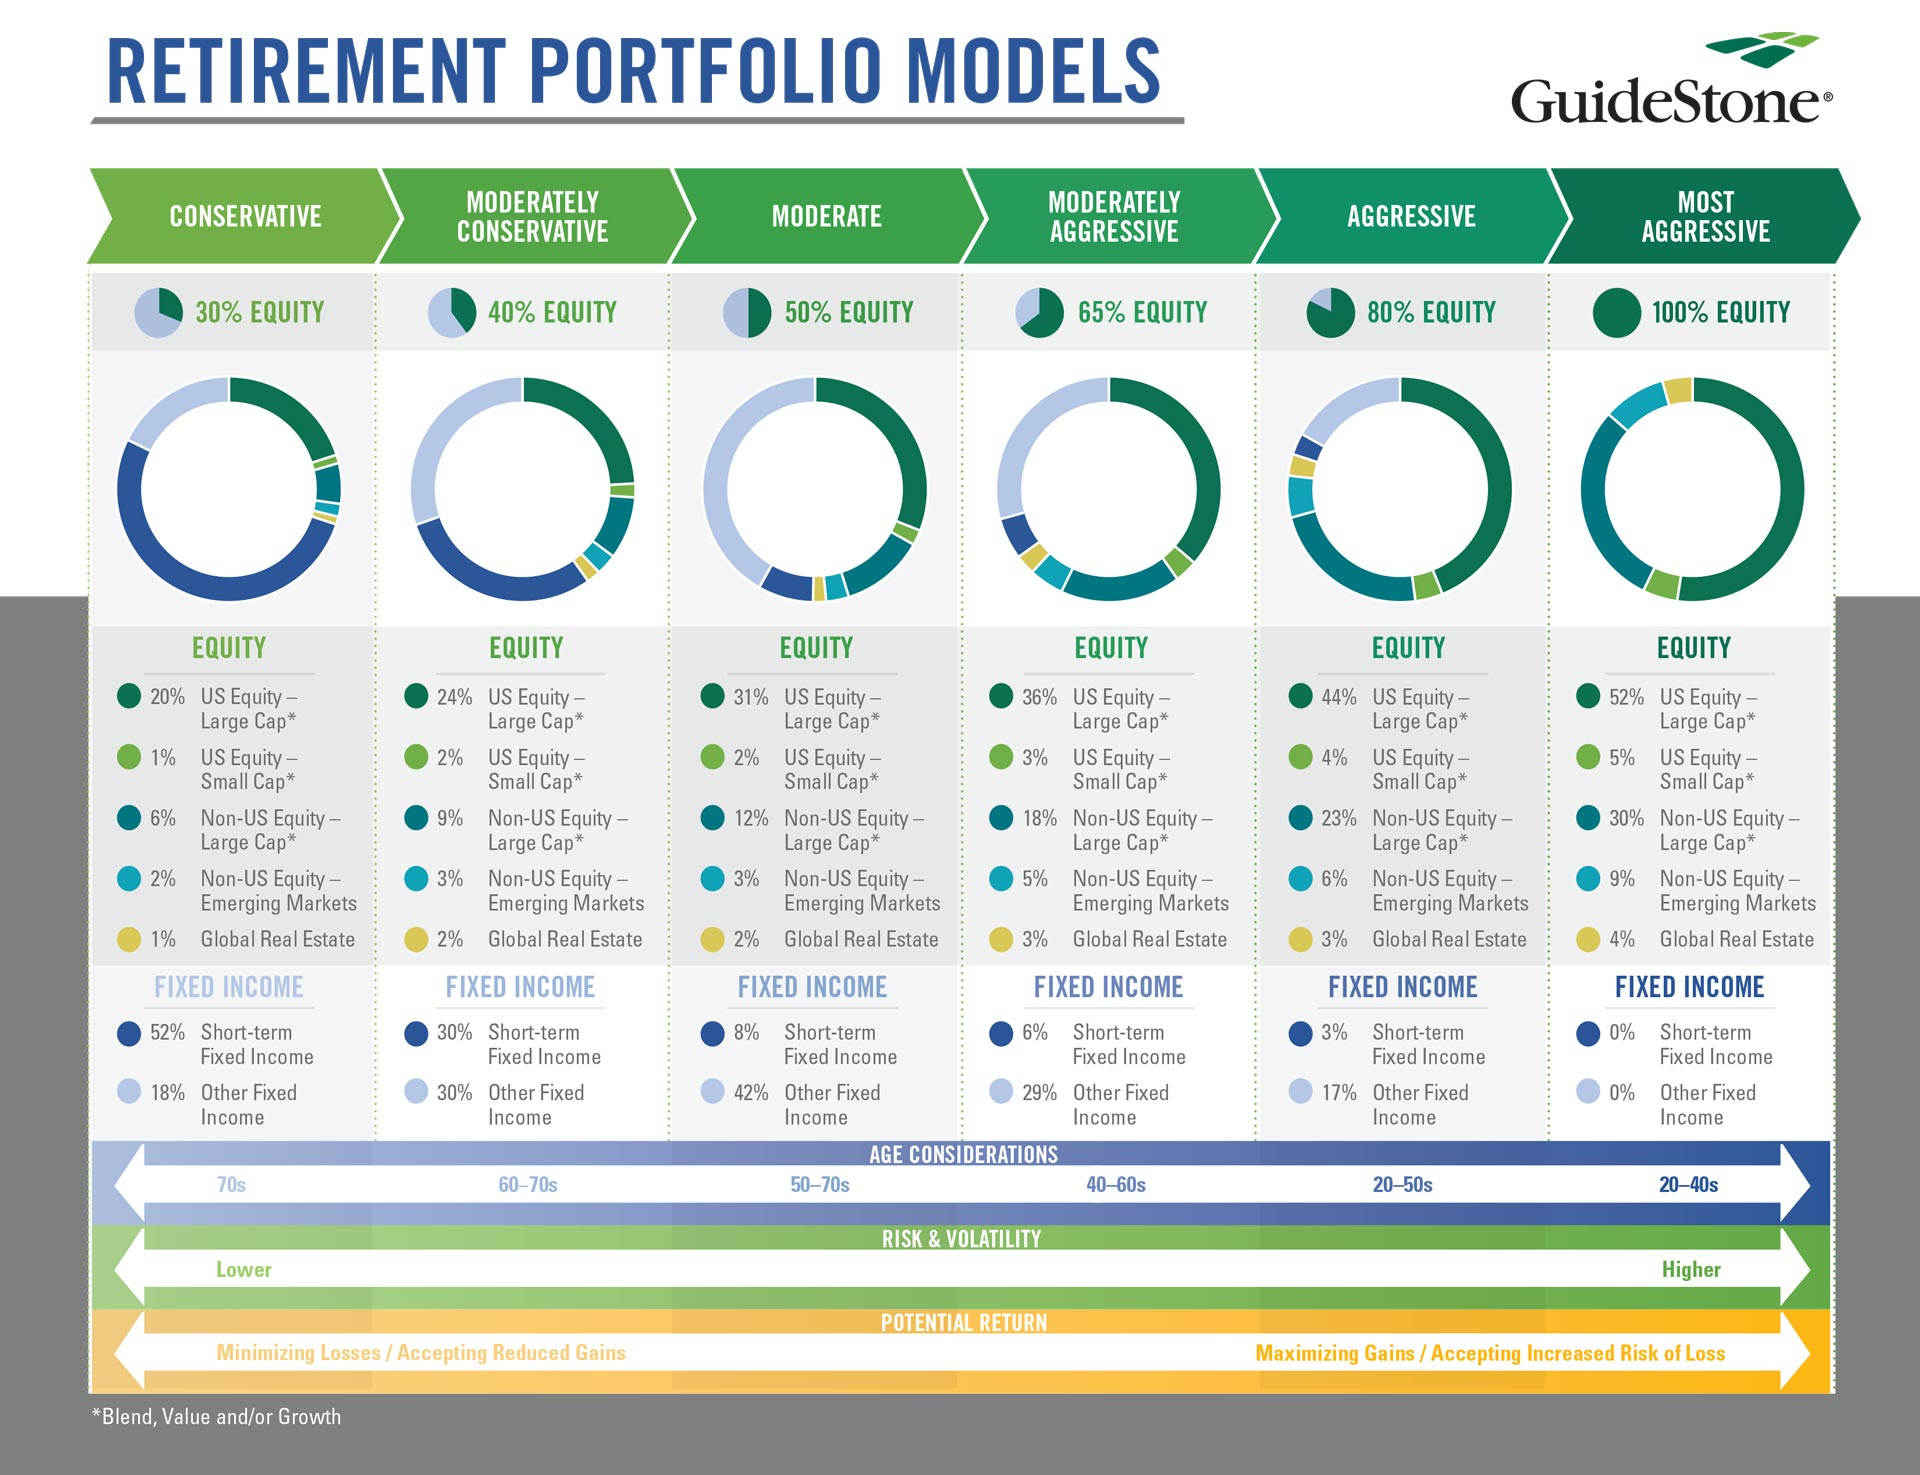
Retirement planning can be daunting. It’s often the culmination of decades of hard work, savings, and planning. One of the most critical components of retirement planning is building a balanced investment portfolio. This can ensure that you not only preserve your wealth but also grow it enough to sustain your lifestyle for decades to come. In this article, we will delve into the nuances of building a balanced investment portfolio specifically tailored for retirement.
Understanding the Importance of a Balanced Portfolio
Before diving into the nitty-gritty of portfolio construction, let’s first understand why a balanced investment portfolio is crucial for retirement. Simply put, a balanced portfolio helps mitigate risk while providing an opportunity for growth. As you transition into retirement, your investment strategy must evolve from a growth-focused approach to one that sustains your income throughout your retirement years.
A well-balanced portfolio can also help you weather the inevitable ups and downs of the market. By diversifying across different asset classes—such as stocks, bonds, and real estate—you can reduce the impact of any single investment’s poor performance on your overall portfolio.
Key Components of a Balanced Investment Portfolio
-
Stocks: These provide the potential for growth and, historically, have outperformed other asset classes over the long term. While stocks can be volatile in the short term, holding a diversified mix can mitigate this risk.
-
Bonds: As a generally safer investment, bonds can provide steady income through interest payments. They can also help stabilize your portfolio during times of stock market volatility.
-
Real Estate: Investing in real estate can offer a hedge against inflation and provide a second income stream through rental properties. However, it also requires more involvement and liquidity considerations.
-
Cash and Cash Equivalents: Cash reserves ensure you have liquidity for emergencies or short-term needs. They can also buffer your portfolio and reduce volatility.
-
Alternative Investments: These could include commodities, hedge funds, or private equity. Though they might be riskier, they can also offer diversification benefits.
Steps to Building Your Balanced Portfolio
Now that we’ve laid the groundwork, let’s explore the steps you can take to build your balanced investment portfolio for retirement.
Step 1: Assess Your Current Financial Situation
Before you can build a balanced portfolio, you need to understand where you currently stand financially. This involves evaluating your income, savings, debts, and existing investments. Gather all necessary financial documents, then create an overview of your net worth.
Also, analyze your current spending. How much do you expect to spend each month during retirement? Understanding your expenses will inform how much you will need to draw from your portfolio each year.
Step 2: Define Your Retirement Goals
What does your dream retirement look like? Whether it’s traveling the world, spending time with family, or simply relaxing at home, having a clear vision of your retirement will guide your investment strategy. Consider the following questions:
- At what age do you plan to retire?
- What are your expected annual expenses?
- Do you intend to leave a financial legacy for your heirs?
By answering these questions, you can create realistic financial goals for your retirement.
Step 3: Understand Your Risk Tolerance
Your risk tolerance will significantly influence your portfolio construction. If you’re a risk-averse investor, you might lean more heavily towards bonds and cash equivalents. Conversely, if you can stomach ups and downs, you may choose to allocate a larger percentage to stocks.
Step 4: Diversify Your Investments
Once you have assessed your current financial situation, defined your retirement goals, and understood your risk tolerance, it’s time to diversify. A diversified portfolio spreads risk by investing in various asset classes. Here’s a general guideline for asset allocation based on your age:
- In Your 20s and 30s: You can afford to take on more risk, so consider allocating about 80% to stocks and 20% to bonds or cash equivalents.
- In Your 40s: As retirement approaches, you may want to start shifting your portfolio to a more balanced approach, aiming for around 70% stocks and 30% bonds.
- In Your 50s: It’s advisable to reduce risk further. Consider a 60/40 split of stocks to bonds.
- In Your 60s and Beyond: The focus should shift to preserving capital, so think about a 50/50 allocation or even higher to bonds.
Remember, this is just a guideline; your unique situation may require a different approach.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
Step 5: Regularly Review and Rebalance Your Portfolio
Market conditions, your risk tolerance, and your financial goals can change over time. It’s essential to regularly review your portfolio—at least annually—to ensure it aligns with your retirement strategy.
Rebalancing may involve selling some of the investments that have performed well and reallocating those funds to underperforming assets to maintain your desired asset allocation. This process can help you take advantage of market fluctuations and prevent your portfolio from becoming overly weighted in one direction.
Step 6: Consider Professional Guidance
If managing your investment portfolio feels overwhelming, consider seeking assistance from a financial advisor. An advisor can help you devise a strategy tailored to your unique situation, risk tolerance, and goals. They can also keep you accountable and help to navigate complex financial markets.
Common Mistakes to Avoid
While building a balanced investment portfolio, be mindful of common pitfalls:
- Overreacting to Market Fluctuations: It can be tempting to alter your strategy based on daily market changes. However, retirement investing is a long-term game; stick to your strategy.
- Neglecting to Diversify: Concentrating too much on one asset class can expose you to undue risk.
- Ignoring Fees: Investment fees can eat away at your returns. Always consider the costs associated with any investment options.
- Procrastination: The earlier you start planning and investing for retirement, the better your chances of accumulating substantial wealth.
The Role of Tax-Advantaged Accounts
When building your balanced investment portfolio for retirement, be sure to take full advantage of tax-advantaged accounts like 401(k)s, IRAs, and Roth IRAs. These accounts can provide significant tax benefits and make your investments work harder for you.
-
401(k) Plans: Many employers offer 401(k) plans that allow you to contribute pre-tax dollars and provide matching contributions. Take full advantage of any employer match—it’s essentially free money!
-
Individual Retirement Accounts (IRA): Traditional IRAs allow for tax-deductible contributions, while Roth IRAs are funded with after-tax dollars and provide tax-free withdrawals in retirement.
-
Health Savings Accounts (HSA): If you have a high-deductible health plan, HSAs can be a valuable tool for retirement planning. Contributions are tax-deductible, and withdrawals for qualifying medical expenses are tax-free.
The Importance of Staying Educated
The investment landscape is continually evolving, and staying educated is vital to successful retirement planning. Regularly read financial news, attend workshops, and participate in retirement planning seminars. Staying informed will also enable you to make more confident and informed decisions.
In Conclusion
Building a balanced investment portfolio for retirement is not a one-size-fits-all approach. It requires careful consideration of your unique financial circumstances, retirement goals, and risk tolerance. By understanding the importance of asset allocation, diversifying your investments, and regularly reviewing your portfolio, you can set yourself up for a secure and satisfying retirement.
Remember, the earlier you start planning and investing, the better off you’ll be when the time comes to enjoy your golden years. Whether you choose to go the DIY route or enlist the help of a financial advisor, take charge of your financial future—your retirement depends on it. Happy investing!


