
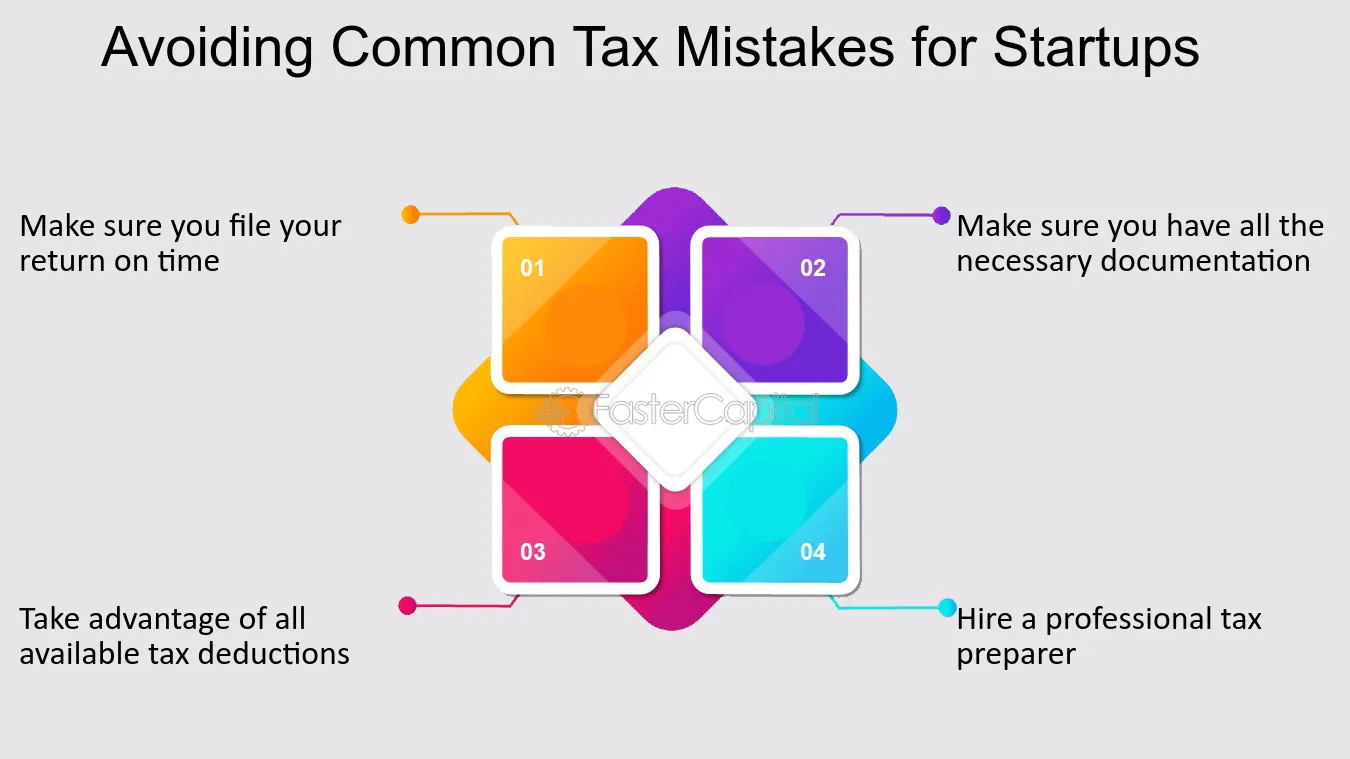
Navigating the world of tax filings can be one of the more daunting tasks for entrepreneurs and startup founders. Mistakes can happen, whether due to a misunderstanding of tax regulations or simple human error. The good news is that correcting those mistakes is possible. In this article, we will guide you through everything you need to know about correcting mistakes in your startup’s tax filings, ensuring you stay compliant and avoid penalties.
Understanding the Importance of Accurate Tax Filing
Before diving into corrections, it’s vital to grasp why accurate tax filing is crucial for startups. The fallout from a mistake can extend beyond fines; it can affect your credibility with investors and clients. Additionally, tax authorities may impose penalties that can strain your financial resources, particularly in the early days of your startup.
Correct tax filing also provides a clear picture of your startup’s financial health, allowing you to make informed business decisions. In short, getting your taxes right is integral not only to compliance but to the future success of your startup.
Common Tax Filing Mistakes Startups Make
Understanding common mistakes is the first step towards correction. Here are a few prevalent issues that startups encounter:
-
Incorrect Business Structure: Choosing the wrong business entity (LLC, S-Corp, etc.) can lead to incorrect tax filings. Each entity has different tax obligations.
-
Omitting Income: Failing to report all sources of income is a common mistake. This can occur if you overlook cash payments or income from side ventures.
-
Claiming Ineligible Deductions: Startups often try to claim deductions that aren’t permissible, such as personal expenses or incorrectly categorized business expenses.
-
Missing Deadlines: Tax deadlines are critical. Missing them can result in penalties and interest on unpaid or underpaid taxes.
-
Inaccurate Information: Simple typos or incorrect Social Security numbers can create significant issues in your tax filings.
Steps to Correct Mistakes in Your Tax Filing
If you’ve discovered a mistake in your startup’s tax filing, here’s how to address it promptly and effectively:
1. Identify the Mistake
Before you can correct any mistake, you need to clearly understand what went wrong. Gather your documents and review your tax forms thoroughly. This will help you pinpoint exactly where the discrepancies or errors occurred, whether in reported income, deductions claimed, or any other area.
2. Determine the Type of Correction Needed
Once you’ve identified the mistake, determine what type of correction is required. Here are some scenarios:
-
Amending Income: If you’ve failed to report some income, you’ll need to adjust your income reporting.
-
Adjusting Deductions: If you mistakenly claimed ineligible deductions, you’ll need to amend your filings accordingly.
-
Filing Late: If you missed a deadline, it’s wise to file as soon as possible to minimize penalties.
3. Use the Correct IRS Form
To amend your tax returns, you’ll typically need to submit Form 1040-X for personal income tax or the equivalent form based on your business structure, such as Form 1120-X for corporations. Familiarize yourself with the relevant form and make sure to indicate that you are amending a prior return.
4. Complete the Form Accurately
Filling out the form accurately is crucial. You’ll need to include:
- The Original Return: Provide a copy of the original return that you’re amending.
- The Amended Return: Complete the amended form, showcasing the corrected figures. Be clear about what has changed and why.
- Supporting Documentation: Include any documents that support your correction, such as additional income reports or proof of eligible deductions.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
5. Submit the Amended Return
Once your Form 1040-X (or the equivalent) is completed, submit it to the IRS. Keep in mind that amended returns cannot be filed electronically for most businesses; they must be mailed.
6. Track Your Amended Return
After submitting, it’s important to track your amended return. The IRS provides a tool called “Where’s My Amended Return,” which allows you to check the status. Typically, processing an amended return can take up to 16 weeks, so patience is key.
7. Prepare for Potential Audits
Correcting tax mistakes can raise red flags and may trigger an audit. While not all amendments lead to audits, it’s wise to be prepared. Maintain records supporting your corrections, including original documentation and correspondence with the IRS if applicable.
8. Consult a Tax Professional
If you’re feeling overwhelmed or if your tax situation is complex, consider hiring a tax professional. They can provide invaluable insight and ensure that your corrections are made accurately and efficiently. Experienced tax consultants can help you navigate the nuances of IRS regulations and ensure you’re making corrections in a way that minimizes your tax liability.
9. Keep Accurate Records
Moving forward, keep accurate and comprehensive records of your financial transactions. Consider utilizing accounting software tailored for startups that can help track expenses, income, and tax obligations. Regularly reconciling your books will help catch discrepancies early on and prevent future mistakes.
Proactive Measures to Avoid Future Mistakes
While correcting past mistakes is vital, preventing future errors is even more crucial. Here are some strategies to consider:
-
Educate Yourself and Your Team: Take the time to understand tax laws pertinent to your startup. Participating in workshops or enrolling in courses can be beneficial.
-
Organize Your Financial Records: Maintaining organized and accessible financial records simplifies tax filing. Implement a consistent filing system for receipts, invoices, and other financial documents.
-
Stay Updated with Tax Laws: Tax laws can change, particularly for startups and small businesses. Keep informed on any modifications that may affect your filings through networking with other entrepreneurs or following relevant news.
-
Set Reminders for Deadlines: Utilize digital calendars to set reminders for tax filings and payment deadlines. Staying ahead of deadlines ensures compliance and reduces the chance of late payments.
-
Use Comprehensive Accounting Software: Consider investing in robust accounting software that can assist in tracking your tax obligations and generating reports. Choose software that is designed specifically for your industry and business needs.
Conclusion
Mistakes in your startup’s tax filings can feel overwhelming, but they are correctable. By identifying errors, filing amendments promptly, and staying organized, you can navigate the complexities of tax regulations without undue stress. This not only protects your startup from potential penalties but also establishes a solid foundation for your business’s growth. Remember, while it’s important to rectify mistakes, it’s equally crucial to proactive measures for future success. By implementing these recommendations, you can stay ahead of your tax obligations and ensure that your startup thrives in a compliant manner.
Whether you are just starting your entrepreneurial journey or are looking to refine your existing business processes, understanding how to handle tax errors is fundamental. With the right knowledge and tools, ensuring the accuracy of your filings will become a streamlined part of your business operations. Happy filing!


