
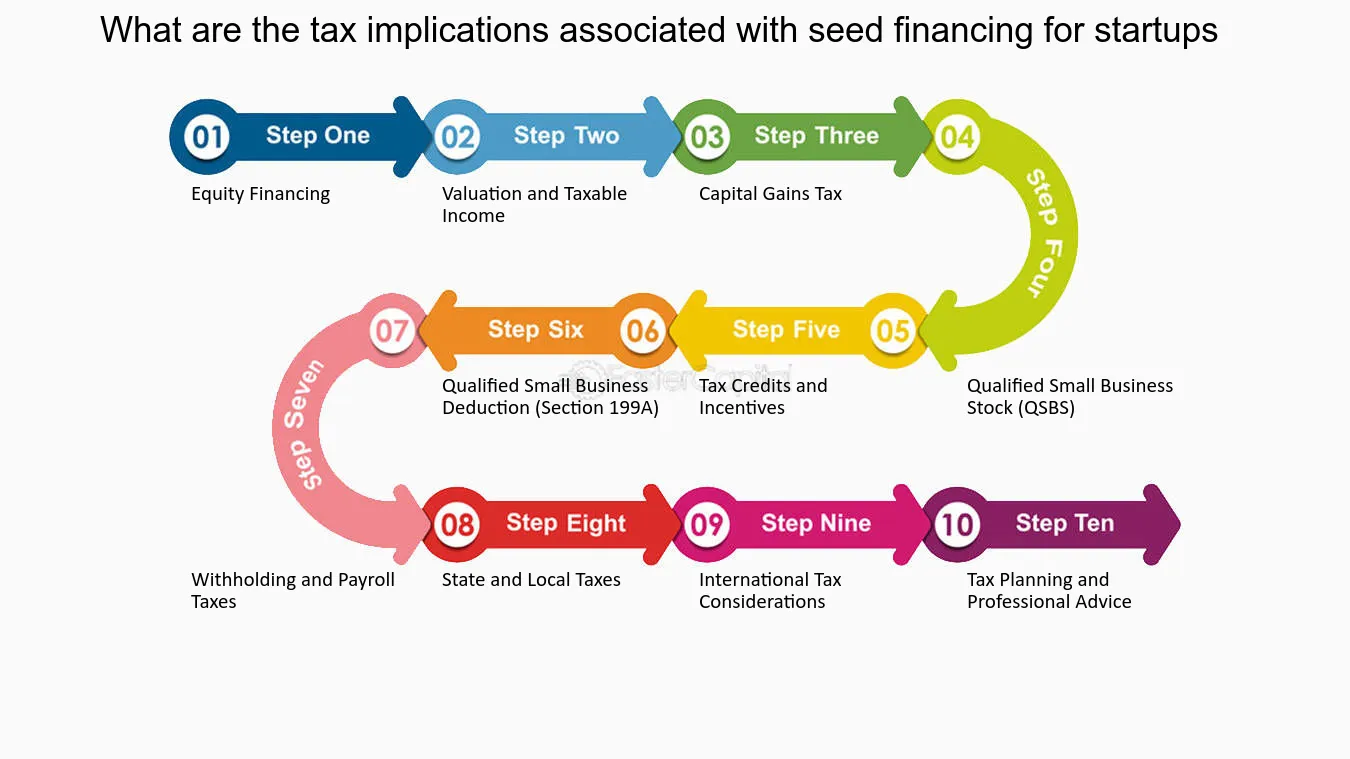
Starting a new venture in the startup ecosystem is an exhilarating journey, often filled with dreams, innovation, and the occasional existential crisis about finances and tax obligations. One of the most exciting milestones is receiving seed funding, which can provide your business with the financial boost it so desperately needs. However, with that influx of cash comes the often-dreaded reality of taxes. Understanding how to manage this effectively can mean the difference between your startup’s bright future and a sticky financial situation that leaves you scrambling to keep your head above water.
In this comprehensive guide, we’ll walk you through the winding road of taxes in the context of receiving seed funding. Whether you’re at the early stages of ideation or you’ve just closed on that all-important funding round, this piece will offer valuable insights into the rules and responsibilities that come with your newfound financial backing. Let’s jump in!
Understanding Seed Funding
Before delving into taxes, it’s crucial to get a solid grasp on what seed funding essentially is. While the definition may vary, seed funding generally refers to the initial capital that startups receive to kick-start their business operations. This money often comes from angel investors, venture capitalists, crowdfunding, or even personal contributions from founders.
The purpose of seed funding typically includes:
- Covering initial operational costs
- Product development
- Marketing initiatives
- Hiring essential staff
While securing seed funding is a significant achievement, it’s only the beginning of a nuanced financial landscape. And as your startup receives its first infusion of cash, tax obligations become an unavoidable reality.
The Importance of Proper Tax Planning
First and foremost, understanding your tax obligations is critical for the long-term sustainability of your startup. Improper handling of taxes can lead to fines, back taxes, and a tarnished reputation that is hard to shake off. Serious implications can emerge, especially if you fail to keep accurate records or do not understand what is taxable income.
Key Things to Keep in Mind
-
Tax Classification: The structure of your startup—whether it’s a sole proprietorship, LLC, corporation, or partnership—will dictate your tax obligations and responsibilities.
-
Taxable Income: Not all funding is taxable. Understanding which portions may be considered taxable income is essential to reducing your tax burden.
-
Record Keeping: Keeping detailed and organized records of all transactions, expenses, and funding rounds is crucial. This will make your life much easier during tax season.
Identifying Taxable Income
When you receive seed funding, it’s vital to distinguish what aspects of this funding may be taxable. Typically, seed investment itself is not considered taxable income, but there are exceptions:
-
Equity Compensation: If part of the seed funding involves the company issuing stock options or equity to investors as a form of capital, you’ll need to know how these forms of compensation are taxed.
-
Grants and Competitions: If your startup has benefited from grants or has taken part in competitions that award cash prizes, these funds can usually be classified as taxable income.
-
Interest and Dividends: If your funding includes any kind of return for investors, such as interest on loans or dividends via profit-sharing, those will also fall into the taxable income category.
Consulting with Tax Professionals
Given the complexities involved, reaching out to a tax professional or CPA is highly advisable. They can provide guidance based on your unique situation, ensuring you minimize any risk of making costly errors. Investing in professional tax advice early can save you considerable headaches later on.
Preparing for the Tax Responsibilities Ahead
Change in Financial Habits
The moment you receive seed funding, your financial habits might need to change. You are now responsible for tracking cash flow, recording every expense meticulously, and preparing your finances for both short-term and long-term tax implications. This is also the prime time to consider using accounting software or hiring an accountant if you haven’t done so already.
Proper Record Keeping
Make it a practice to keep all funding documents, receipts, and contracts in an organized manner. Cloud storage solutions can provide a safe and accessible way to archive these important documents. Here’s what you should keep:
- Funding Contracts: Preserve all documentation concerning your funding arrangements.
- Expense Receipts: Keep track of all expenses related to your startup, from operational costs to marketing expenditures.
- Financial Statements: Maintain accurate financial statements showing income, expenses, and investment inflows.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
Deductible Expenses for Startups
When calculating your taxable income, remember that not all income is subject to taxes. Many business-related expenses qualify as tax-deductible. This means that you can subtract these costs from your overall income, thereby lowering your taxable income.
Some common deductible expenses for startups include:
- Salaries and Wages: If you’ve hired staff, their salaries may be deductible.
- Rent and Utilities: The cost of leasing office space and associated utilities can often be deducted.
- Equipment Purchases: Items essential for doing business, such as computers and machinery, may qualify for depreciation deductions.
- Marketing and Advertising: Any funds dedicated to marketing initiatives could also be deductible.
The Timing of Your Tax Obligations
Once you receive seed funding, it’s crucial to understand the timeline for your tax obligations. Taxes for most businesses are typically due on April 15 for the previous calendar year. However, depending on your startup’s structure, you might be required to make estimated tax payments quarterly, which is something to factor in when preparing your budget.
Dealing with Different Sources of Funding
Since seed funding can come from various sources, it’s essential to track the origin of the funds meticulously. Each source may have different tax implications—especially if your funding includes convertible notes, equity, or other forms of investment.
-
Convertible Notes: These are essentially loans that convert into equity at a later financing round. Although the initial funding may not be taxable as income, you’ll need to account for any associated interest in your taxable income at some point.
-
Equity Investments: If funds come from selling equity stakes, understand that there may not be immediate tax implications, but future implications could arise when profits are distributed or when you sell the company.
-
Grants and Competitions: If your startup has received money through grants, check to see if those funds are taxable. Many government grants are categorized differently from private funding.
Staying Compliant with Regulatory Requirements
Navigating regulatory requirements can often feel like a maze. In addition to federal taxes, you also have to factor in state and local taxes. Compliance means ensuring that any taxes owed to federal, state, and local governments are paid in full and on-time. Carefully investigate what regulatory reporting is required for your startup.
Bonus: Tax Credits and Incentives
While taxes might make your head spin, don’t forget the potential for tax credits and incentives that can ease some of your financial burdens. Engaging with a tax advisor can help identify opportunities tailored to your startup’s unique circumstances. Here’s a quick overview:
- Research and Development Tax Credit: If your startup invests in research and development, you might qualify for significant tax breaks.
- Startup Tax Credits: Many states offer tax credits specifically for new businesses. Do your due diligence to identify opportunities that apply to your startup.
Creating a Long-Term Strategy
Tax handling isn’t merely a one-and-done approach; it’s part of a broader strategy for financial health. Consider creating a long-term tax strategy that can help you navigate future funding rounds, scaling efforts, and possible exits. Revisit your tax plan annually or when significant changes occur within your business.
Conclusion: Mastering the Tax Maze
Receiving seed funding is an exhilarating step in your startup journey, but tackling your tax obligations may be equally vital to your long-term success. By understanding the foundational aspects of taxation as it pertains to your new venture, preparing for upcoming responsibilities, and seeking professional guidance, you can navigate the maze of startup taxes with confidence.
Remember, tackling taxes is not about evasion—it’s about preparation, transparency, and compliance. The financial facets of your startup might seem overwhelming, but with the right tools and knowledge, you can focus on what really matters: growing your business and innovating for the future. So gear up, stay informed, and get ready to embrace the incredible journey that lies ahead!


