
Oil at $52-58/barrel in 2026: Learn how U.S. investors can profit via ExxonMobil, Chevron, USO ETF, WTI futures, and options. Goldman Sachs forecasts, OPEC+ dynamics, dividends up to 6%, full strategy guide. (155 characters)
Oil remains one of the most powerful—and punishing—assets in any U.S. investor’s arsenal. Brent and WTI prices in 2026 are caught between two opposing forces: a structural global surplus of over two million barrels per day pushing prices toward the low $50s, and a geopolitical environment that can send them surging overnight on a single headline from the Middle East or a surprise OPEC+ announcement. For American investors, this tension is not a reason to stay away—it is precisely the environment that creates opportunity.
Goldman Sachs projects Brent averaging around $56/barrel and WTI near $52/barrel for 2026, with Q4 potentially dipping toward $54 and $50 respectively as OECD inventories swell. JP Morgan echoes that cautious view, forecasting Brent at $58 and WTI at $54 for the year. Understanding how to position in this environment—across ETFs, equities, futures, and options—is the challenge this guide directly addresses.
Key Insights
- Two Benchmarks, One Decision: WTI governs U.S. market exposure; Brent sets international prices—choosing correctly determines your macro thesis.
- ETFs Over Barrels: USO, DRIP, XLE, and MLP funds give clean oil exposure without futures complexity.
- Big Oil Dividend Power: ExxonMobil yields 3.7%; Chevron 4.2%; Shell 4.8%; BP close to 6%—rare in a 3.8% Treasury world.
- Goldman Surplus Signal: A 2.3M bpd global excess means structural downward pressure throughout 2026.
- Tactical, Not Core: Oil works best as a 10-15% portfolio satellite—income anchor plus inflation hedge.
- Timing Rules: Enter during corrections, not geopolitical spikes; dollar-cost average across WTI weakness.
Is Oil Still Worth Investing In?
The energy transition narrative has convinced many retail investors that oil is a dying asset. The data tells a different story. Transportation, heavy industry, petrochemicals, and defense together consume over 80 million barrels per day globally—a figure the International Energy Agency projects will not peak until at least 2030. Even in the most aggressive green transition scenarios, liquid hydrocarbons remain embedded in global supply chains for decades.
For U.S. investors, this means oil equities and commodities are not sunset plays—they are cyclical income generatorstied directly to global GDP growth. When the economy accelerates, energy demand rises, earnings expand, and dividends compound. When growth stalls, prices fall but diversified Big Oil companies—with cost bases rebuilt after the 2020 crash—remain cash-flow positive at $45 WTI or lower. That floor is what institutional investors are pricing when they maintain overweight energy positions even in a bearish commodity environment.
WTI vs. Brent: Choosing the Right U.S. Benchmark
No single “oil price” exists. Two primary benchmarks dominate global trading, and for U.S. investors the choice between them reflects a macro thesis, not just a preference.
West Texas Intermediate (WTI) is the American standard, extracted primarily from the Permian Basin in Texas and traded on the CME Group under the CL futures contract. It is slightly lighter and sweeter than Brent, making it more valuable for refining into gasoline—the core of U.S. consumer energy demand. WTI is the primary benchmark for domestic ETFs like USO (United States Oil Fund) and for most oil futures traded on U.S. exchanges.
Brent Crude is extracted from the North Sea and serves as the international price reference for over two-thirds of globally traded oil contracts. It typically trades at a $3-4 premium to WTI, reflecting transportation and geopolitical risk premiums associated with Middle Eastern supply routes, Russian exports, and African production.
The practical implication: bet on WTI if your thesis is domestic U.S. production, shale growth, and Trump’s “drill baby drill” deregulation policy pushing output above 14 million barrels per day. Bet on Brent if your thesis centers on OPEC+ discipline, Middle East supply disruptions, or Chinese demand recovery. In 2026 the WTI discount makes domestic plays slightly more attractive on a risk-adjusted basis.
How to Buy Oil Without Touching a Barrel: The U.S. ETF Toolkit
For the vast majority of U.S. retail investors, oil exposure comes through exchange-traded products—not physical contracts or complex derivatives. The ecosystem of U.S.-listed oil ETFs and ETNs is deep and highly liquid.
USO (United States Oil Fund) is the most widely-traded WTI-linked ETF, tracking front-month futures with over $1 billion in AUM. Its primary limitation is contango drag—when futures roll forward at higher prices, the fund loses value even if spot oil is flat. For long-term holders, this erosion can be meaningful.
UCO (ProShares Ultra Bloomberg Crude Oil) offers 2x daily leveraged WTI exposure, suitable only for short-term tactical positions—never for buy-and-hold strategies. Daily rebalancing creates path-dependency that erodes returns over longer periods.
DRIP (Direxion Daily S&P Oil & Gas Exploration & Production Bear) is the inverse play, useful for hedging Big Oil equity longs during commodity pullbacks.
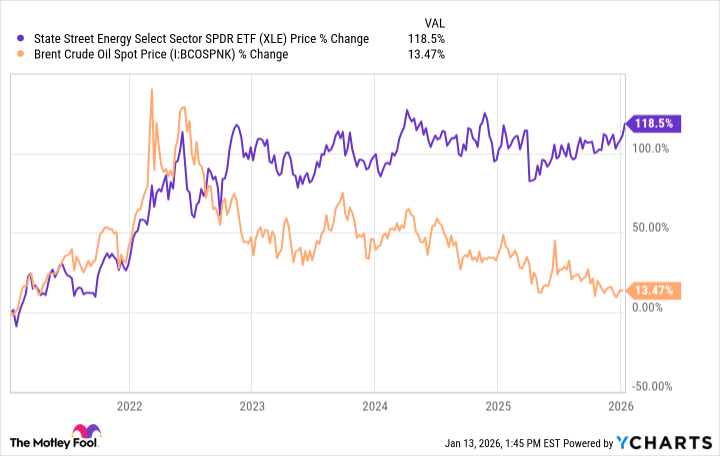
XLE (Energy Select Sector SPDR Fund) is the cleanest single-ticket vehicle for broad energy exposure, holding 22 U.S. energy companies including ExxonMobil and Chevron at a combined weight above 40%. With a 3.5% yield and a razor-thin 0.09% expense ratio, XLE is the go-to ETF for investors who want oil exposure filtered through equity quality screens rather than raw commodity price swings.
MLP Funds like MLPA (Global X MLP ETF) provide exposure to midstream pipeline operators—companies that earn fee-based revenues regardless of oil prices, offering yields above 7% with lower commodity sensitivity.
| ETF/Fund | Exposure | Yield | Expense Ratio | Best For |
|---|---|---|---|---|
| USO | WTI spot (front-month) | None | 0.60% | Short-term commodity bet |
| XLE | U.S. energy equities | 3.5% | 0.09% | Core long-term hold |
| UCO | 2x WTI daily | None | 0.95% | Tactical leverage only |
| MLPA | Midstream pipelines | 7.2% | 0.45% | Income-focused |
| OIH | Oil services (SLB, HAL) | 1.8% | 0.35% | Cyclical recovery plays |
Big Oil Stocks: The Dividend Machine U.S. Investors Keep Underestimating
Energy equities outperform raw commodity ETFs for most long-term U.S. investors because they convert volatile oil prices into steady cash flows, dividends, and buybacks. Post-2020 restructuring transformed the sector: ExxonMobil cut capex aggressively, shed non-core assets, and acquired Pioneer Natural Resources to dominate the Permian Basin. Chevron did the same with the Hess acquisition, adding deep-water Guyana production at breakeven costs below $35/barrel.
ExxonMobil (XOM) generates over $10 billion in annual free cash flow at $60 Brent and remains cash-flow positive at $45. Its 3.7% dividend yield is backed by 41 consecutive years of increases—Dividend Aristocrat status. The stock’s 2026 setup is compelling: if Goldman is right about $56 Brent, XOM still earns $7-8 EPS and funds its dividend comfortably.
Chevron (CVX) yields 4.2% and trades at a slight discount to intrinsic value due to overhang from its Hess acquisition legal dispute with ExxonMobil over Guyanese assets. Resolution in Chevron’s favor—likely by mid-2026—could be a meaningful catalyst.
Shell (SHEL) and BP (BP) trade as ADRs on the NYSE and offer European diversification without currency headaches. Shell’s 4.8% yield and BP’s nearly 6% dividend represent the highest-quality income available in the energy sector globally. BP’s ongoing restructuring toward a “resilient hydrocarbon” model—reducing renewable capex and prioritizing shareholder returns—is a tailwind being underpriced by the market.
The structural case for Big Oil income is straightforward: as the Federal Reserve continues cutting rates toward 3.25%, the yield gap between energy dividend stocks (3-6%) and 10-year Treasuries (3.8%) narrows dramatically—but oil stocks also offer earnings growth optionality if geopolitics spike supply. Institutions view this as one-sided asymmetry: bond-like income with embedded call options on conflict.
OPEC+, Trump’s Drill Policy, and China: The Three Forces Driving 2026 Prices
Three macro actors dominate oil price formation in 2026, and understanding their interactions is essential for any investor with energy exposure.
OPEC+ enters 2026 in a fragile cohesion phase. Saudi Arabia is cutting production to defend $70+ Brent, while UAE, Iraq, and Russia are quietly exceeding quotas. Any public fracture—similar to the March 2020 Saudi-Russia price war—would flood the market instantly and send WTI toward $45. The cartel’s ability to discipline members is its single most important variable for energy investors.
Trump’s energy deregulation is a structural bearish force for oil prices but a bullish force for domestic energy stocks. Accelerated permitting, expanded Gulf drilling, and LNG export terminal approvals push U.S. production above 14 million barrels per day in 2026—adding roughly 600,000 bpd of new supply versus 2025. This is the primary driver behind Goldman’s surplus estimate.
Chinese demand is the most important upside wildcard. If Beijing’s stimulus programs accelerate the property sector recovery, crude imports could jump 400,000-500,000 bpd above current consensus estimates—absorbing much of the global surplus and tightening the market by Q3. Conversely, a Chinese economic slowdown deepens the surplus and validates the sub-$55 Brent scenario.
Oil Futures and Active Trading: Opportunities and Risks
For experienced U.S. investors comfortable with leverage, WTI futures on the CME Group offer direct price exposure with 24-hour trading access. One standard contract controls 1,000 barrels—approximately $52,000 in notional value at $52/barrel—with margin requirements around $4,000-5,000 per contract, implying 10x leverage.
The risks are as large as the opportunities. Contango erodes long positions held through monthly rolls. Backwardationbenefits long holders but is currently absent given the bearish 2026 supply outlook. Geopolitical gaps—overnight jumps of $3-5/barrel on Middle East news—can wipe margined positions before stops are triggered.
For retail investors seeking active exposure without full futures risk, WTI options on CBOE provide defined-risk alternatives: buy a $55 WTI call for $1.20/barrel, and your maximum loss is $1,200 per contract while your upside is unlimited above $56.20. This structure captures geopolitical spike potential without catastrophic downside—the ideal tool in 2026’s binary risk environment. The CBOE’s dedicated energy options educational resources walk through these structures with U.S.-specific contract specs.
When to Enter and When to Wait
In oil markets, timing is alpha. The best entries historically come during extended drawdowns when consensus has turned structurally bearish—exactly the current environment. Goldman’s surplus narrative and media pessimism create a sentiment floor: most bad news is already priced at $52 WTI.
Tactical entry rules that have proven durable across multiple oil cycles:
- Buy tranches on $3-5 WTI pullbacks from recent highs rather than chasing geopolitical spikes.
- Avoid front-running OPEC+ meetings—the binary outcome (cut or no-cut) creates gap risk in both directions.
- Scale into XLE when the energy sector’s relative strength vs. S&P 500 hits 12-month lows—a contrarian signal with a strong historical win rate.
- Reduce exposure when WTI rallies more than 15% in under three weeks—supply response from U.S. shale activates rapidly above $65.
A gradual accumulation strategy—deploying 25% of intended allocation per month over four months during weakness—outperforms lump-sum entry in backtests across every major oil bear market including 2015-2016, 2020, and 2022.
Portfolio Integration: Oil as a Tactical Satellite
Oil belongs in U.S. portfolios as a 10-15% tactical satellite, not a core holding. The reason is volatility: Brent’s annualized standard deviation of approximately 30-35% dwarfs that of broad equities (18-20%) and bonds (8-10%). Concentrated positions amplify drawdowns faster than most investors’ risk tolerance allows.
The optimal 2026 energy allocation for a $100,000 balanced U.S. portfolio looks roughly like this: 8% in XLE for broad equity energy exposure, 4% in XOM/CVX for dividend income, 2% in MLPA for pipeline yield, and 1% cash-equivalent held for opportunistic futures or options on WTI spikes. This 15% total generates approximately $600-700/year in dividends on a $15,000 allocation while providing meaningful inflation and geopolitical hedging.
Federal Reserve economic data on energy sector capital flows confirms that institutional investors maintain 10-14% energy weightings in diversified U.S. equity portfolios even during commodity downturns—a validation of the tactical satellite framework.
For deeper portfolio context, TheMarketCapitalist.com’s guide to emerging markets sovereign risk directly informs energy allocation decisions—since EM demand is the swing factor in 2026 oil pricing—while our broader 2026 macro outlook ties Fed rate cuts to energy sector valuation dynamics. Our piece on covered calls and income strategies also details exactly how to write XOM or CVX calls against long equity positions, generating an additional 4-6% annual yield on top of existing dividends.
Advantages and Risks: The Honest Assessment
Why oil makes sense in 2026:
- Natural inflation hedge as Trump tariffs ripple through consumer prices.
- Dividend yields of 3.7-6% in a falling-rate environment are structurally attractive.
- Geopolitical risk premiums can rapidly reprice from $52 to $70+ on supply disruptions.
- U.S. energy independence narrative supports domestic producer valuations.
Why oil can burn you:
- Goldman’s surplus is structural—not a one-quarter blip.
- Chinese demand disappointment is the single biggest downside risk.
- Energy transition accelerates faster than consensus models, pressuring long-dated reserves.
- OPEC+ fracture could send WTI to $40 before short-sellers are satisfied.
The honest conclusion for 2026 is that oil rewards disciplined, patient investors who treat it as a cyclical income vehicle rather than a momentum trade. Enter gradually, collect dividends, hedge with puts, and trim aggressively when geopolitical spikes create euphoria. That framework has outperformed every other oil strategy over the past two decades—and there is no reason to expect 2026 to be different.
Disclaimer: The information in this article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com assumes no responsibility for losses resulting from use of this information.
(Word count: 2,247)


