
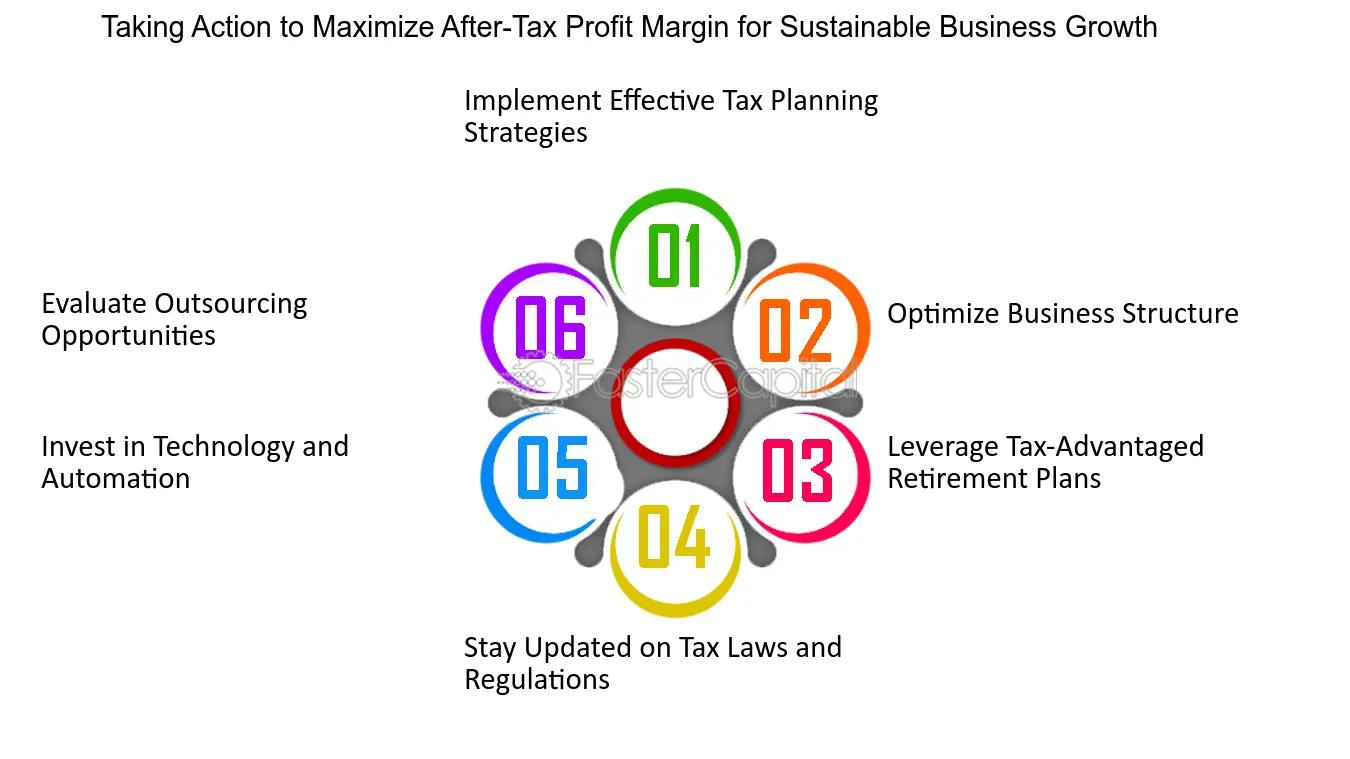
As a startup founder, navigating the financial landscape is one of the most exciting yet daunting aspects of growing your business. One of the key concerns that arise as your revenue scales is how to manage your taxable income effectively. Understanding the intricacies of taxes can help you make informed decisions, leading to significant savings and ensuring compliance. In this thorough guide, we’ll explore practical strategies to manage taxable income as your startup’s financial success unfolds.
Understanding Taxable Income
Before we dive into the strategies, let’s clarify what taxable income means. Taxable income for businesses refers to the portion of your revenue that is subject to taxation after deducting legitimate business expenses. It typically includes money from sales, interest, dividends, and other forms of income.
For startups, especially those in their early stages, navigating through taxable income can be a different ball game. One of the advantages that a startup might enjoy is the ability to deduct numerous expenses that larger corporations might not have, which can minimize taxable income.
The Impact of Revenue Growth on Taxable Income
As your startup begins to gain traction and revenue starts to flow, the implications for taxable income become more pronounced. Increased revenue can elevate your tax liability if you aren’t prepared. This tax burden can eat into your profits, stalling growth and limiting reinvestment in the business. Thus, understanding how to manage it becomes crucial.
Early Revenue Growth: What to Expect
When your business is in its infancy, you may enjoy a range of deductions, such as start-up costs, employee salaries, and marketing expenses. These can significantly lower your taxable income. However, as you scale and your revenue increases, keeping track of all income sources and expenses becomes vital for maximizing your deductions.
Effective Strategies for Managing Taxable Income
Let’s explore some effective strategies that can help you manage your taxable income as revenue grows.
1. Keep Detailed Records
The importance of maintaining accurate financial records cannot be overstated. As your revenue increases, so do the complexities of your income streams and outgoings. Use accounting software to track every dollar that comes in and goes out. This helps you identify potential deductions and ensures you’re prepared if you face an audit.
- Expense Tracking: Categorize your expenses clearly. Common deductible expenses include salaries, rent, utilities, equipment, and marketing.
- Invoice Management: Keep meticulous records of all invoices and receipts. This will allow for easy reference when it’s time to file taxes.
2. Understand Applicable Deductions
Your startup could be eligible for various business deductions that reduce your taxable income. Familiarize yourself with these:
- Operating Expenses: Costs like rent, utilities, supplies, employee salaries, and benefits are often deductible.
- Start-Up Costs: Any costs incurred before your business opens can often be deducted. The IRS allows you to deduct up to $5,000 if your startup expenses are $50,000 or less.
- Asset Depreciation: Major purchases may be written off over several years, lowering taxable income in individual years.
3. Consider Your Business Structure
The legal structure of your startup can significantly impact how you manage taxable income. Here are the primary structures to consider:
- Sole Proprietorship: Income is reported on your personal tax return, making it easier but sometimes more tax burdensome.
- LLC (Limited Liability Company): Offers flexibility with taxation. LLCs can choose to be taxed as pass-through entities or as corporations.
- Corporations: Can choose to be taxed as C-Corps or S-Corps. C-Corps are taxed independently, which may lead to double taxation, while S-Corps allow profits to pass directly to shareholders to avoid this.
Consult with a tax advisor to understand which structure might serve your business best as revenue grows.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
4. Implement Tax Planning
Tax planning is crucial for mitigating tax liability. This isn’t merely about preparing for tax season but strategically managing your income and expenses throughout the year.
- Expense Timing: Pay expenses or purchase equipment in the current year to maximize deductions in that tax year.
- Income Timing: If possible, defer income to the next fiscal year if you expect to be in a lower tax bracket.
- Retirement Contributions: Contributing to a retirement account can offer significant tax advantages while securing your future. For example, as a business owner, you can consider a Solo 401(k) or SEP IRA.
5. Make Estimated Tax Payments
If you expect to owe more than $1,000 in taxes for the year, you might have to make estimated tax payments. These quarterly taxes can help you avoid penalties and interest for underpayment. A proactive approach ensures that you aren’t caught off guard when tax season arrives.
6. Utilize Tax Credits
Seek out available tax credits unique to startups. Many states offer incentives for new businesses or specific industries, such as technology or renewable energy. Research federal and state tax credits that your startup may qualify for, including:
- Research and Development Tax Credit: Designed to incentivize companies engaged in R&D activities.
- Work Opportunity Tax Credit (WOTC): Provides incentives for hiring employees from specific categories, such as veterans or long-term unemployed individuals.
7. Hire a Tax Professional
The tax landscape can be challenging to navigate on your own, especially as your startup grows. Hiring a qualified accountant or tax professional can help you optimize tax strategies specific to your business model, ensuring compliance while maximizing your deductions.
8. Prepare for Growth
As your revenue continues to increase, revisiting your current financial strategies is essential. This is an optimal time to conduct a thorough review of your tax position and assumptions. Consider creating or updating your financial forecasting models to account for additional income, changes in expense patterns, and anticipated tax liabilities.
Conclusion: Staying Proactive is Key
Managing taxable income effectively as your startup’s revenue grows does not need to be an overwhelming challenge. By keeping accurate records, understanding available deductions, choosing the right business structure, implementing tax planning strategies, making estimated tax payments, utilizing credits, and seeking professional help, you can better manage your tax exposure and keep more of your hard-earned dollars.
Remember that the ultimate goal of tax management isn’t solely to minimize your tax bill but also to reinvest in your business and support its continued growth. Take a proactive approach, stay informed about the latest tax conditions and regulations, and ensure that your financial strategies align with your growth aspirations.
As you navigate the often-complex world of startup finance, remember: preparation and adaptability are your greatest allies. Here’s to your startup’s success—may you grow, innovate, and thrive while managing your taxable income effectively!


