
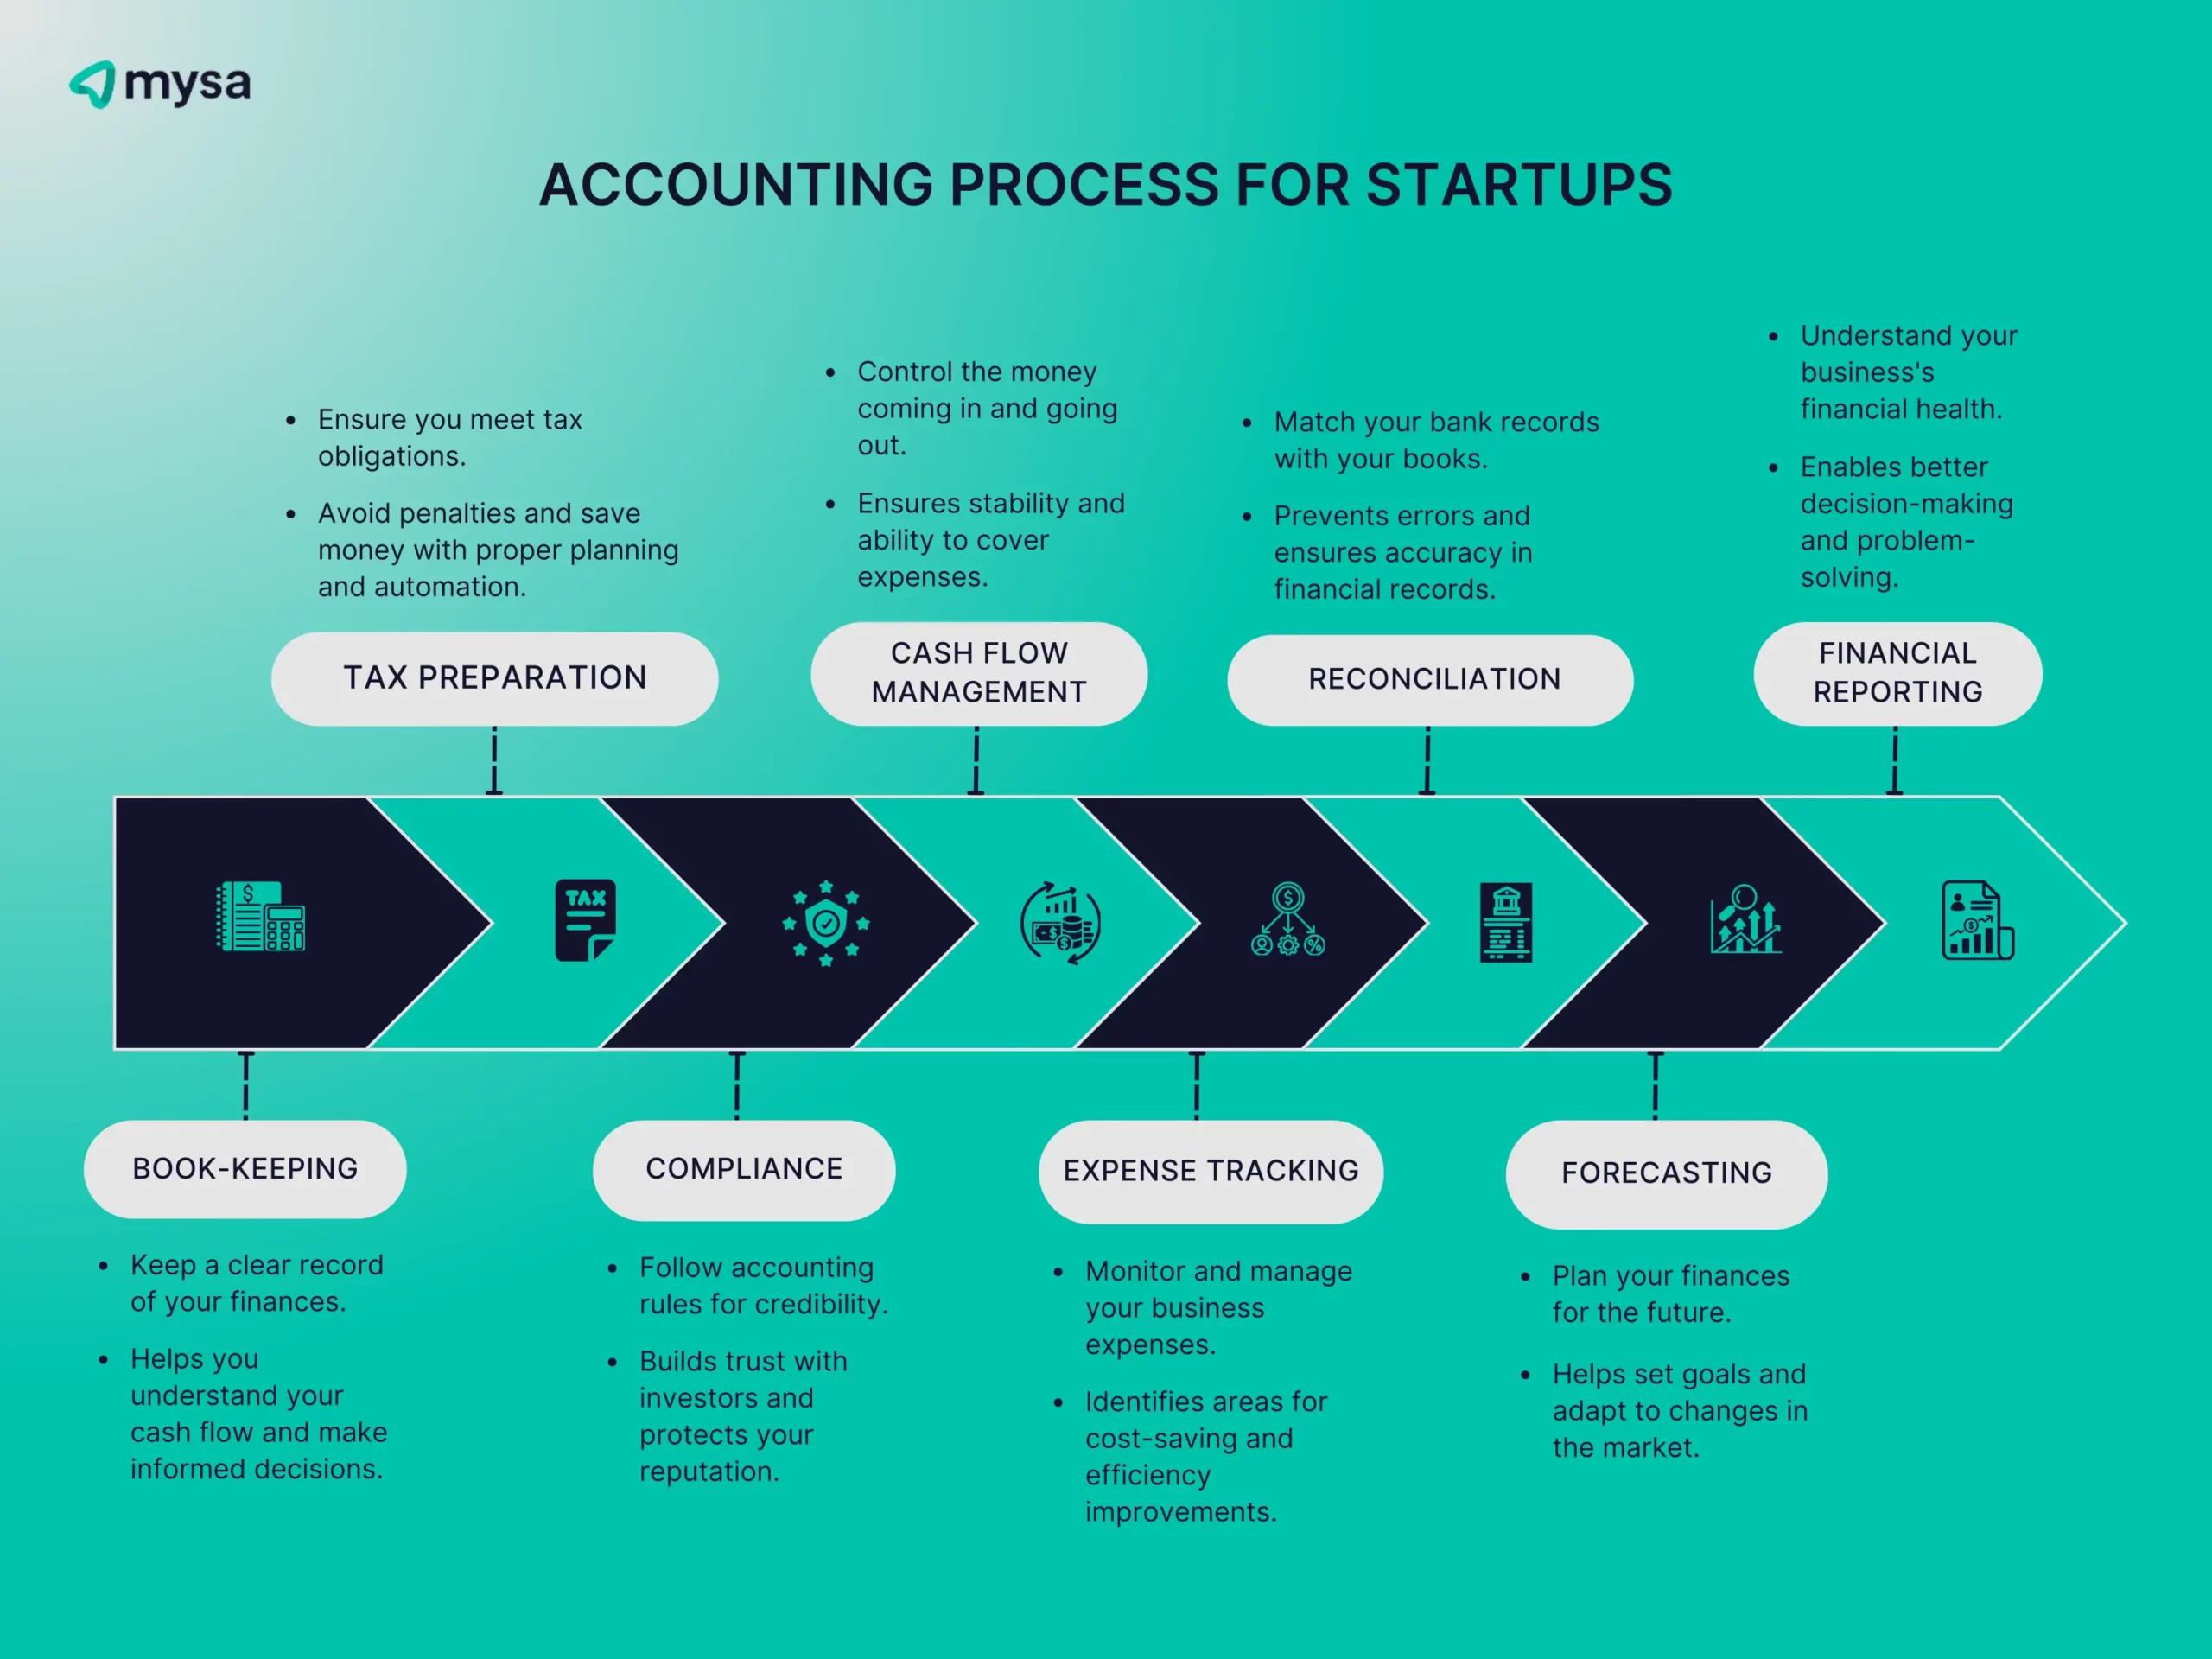
Entrepreneurship is an exhilarating journey filled with countless challenges and rewards. One of the most significant hurdles for any startup is managing finances, especially during tax season. If you’re a startup founder, understanding how to account for your revenue is crucial to compliance and to ensuring the financial health of your fledgling business. This guide will delve into the intricacies of properly accounting for startup revenue in your tax filings, offering insights that can set you on the path to success.
Understanding Startup Revenue
Before we jump into tax strategies, it’s essential to establish what constitutes startup revenue. Revenue refers to the income generated from the operations of your business, which can come from various sources such as:
- Sales of Products or Services: This is the primary source of revenue for most startups.
- Consulting Fees: If your startup provides expert advice or consulting services, consider these as income.
- Grants and Subsidies: Certain startup ventures might qualify for government grants that can also be construed as revenue.
- Investments and Capital Contributions: While not traditional revenue, funds from investors can be classified as capital injections that affect overall financial reporting.
The Importance of Proper Revenue Accounting
Accurate accounting for revenue is not merely a tax issue; it helps you gauge the performance of your startup. Properly tracking these financial metrics can inform your business strategies and forecast growth. Moreover, mistakes in revenue reporting can lead to audits, penalties, and even legal issues, making clarity and accuracy paramount.
The Basics of Revenue Recognition
Revenue recognition is the accounting principle that outlines how and when revenue is recognized in financial statements. This principle dictates that revenue should be recorded when it is earned, not necessarily when the cash is received. For startups, adhering to the following basic rules can be incredibly beneficial:
-
Identify the Contract with the Customer: This includes any verbal agreements, written contracts, or purchase orders that define the transaction.
-
Determine the Performance Obligations in the Contract: Identify what products or services you have promised to deliver.
-
Determine the Transaction Price: The price must be clear and measurable. Adjustments might be necessary for discounts, refunds, or incentives.
-
Allocate the Transaction Price: If a contract has multiple performance obligations, allocate the price to each based on its standalone selling price.
-
Recognize Revenue When Performance Obligations are Satisfied: This happens when control of a good or service is transferred to the customer.
This systematic approach ensures compliance with Generally Accepted Accounting Principles (GAAP) and can help prevent future discrepancies.
Different Accounting Methods
There are two primary accounting methods startups can use to record income: cash basis and accrual basis. The method you choose impacts how you report revenue.
Cash Basis Accounting
In cash basis accounting, revenue is recorded only when it is actually received, and expenses are recorded only when they are paid. This method is straightforward and beneficial for startups that deal primarily in cash since it provides a clearer picture of cash flow at any given moment. However, it may not give an accurate picture of long-term profitability, particularly if you provide a service that will be paid for at a later date.
Accrual Basis Accounting
Conversely, accrual basis accounting recognizes revenue when it is earned, regardless of when the cash is received. This means if you complete a service in December, but the payment is received in January, you would still report that income in December. This method is generally preferred for startups seeking investment or loans, as it provides a clearer view of financial health and profitability, allowing stakeholders to make better-informed decisions.
Keeping Accurate Records
Regardless of which accounting method you choose, detailed record-keeping is vital. Here are some essential records every startup should maintain:
- Sales Invoices: Keep a copy of all sales invoices for products or services rendered.
- Receipts: Document all expenses that are incurred during business operations.
- Bank Statements: Regularly reconcile these statements to verify the accuracy of your records.
- Contracts and Agreements: Maintain clear documentation of all agreements that impact your revenue.
Maintaining meticulous records can simplify your tax filing process, ensuring that you have all necessary information at your fingertips.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
Tax Obligations for Startups
Every startup has unique tax obligations depending on your business structure. Common structures include sole proprietorships, partnerships, limited liability companies (LLCs), and corporations. Here’s a brief overview of how tax obligations can vary:
-
Sole Proprietorship: Income is taxed as personal income on your tax return. Schedule C (Profit or Loss from Business) needs to be filed to account for revenue and expenses.
-
Partnership: Revenue must be reported on Form 1065 (U.S. Return of Partnership Income) and passes through to partners who report it on their personal returns.
-
LLC: Tax treatment depends on whether the LLC is a single-member (like a sole proprietorship) or multi-member (like a partnership).
-
Corporation: Corporations are taxed separately from their owners. Income is reported on Form 1120 (U.S. Corporation Income Tax Return).
Understanding your tax obligations is vital for effective revenue accounting and compliance.
Deductions That Can Minimize Your Tax Burden
As a startup, you may not only be responsible for reporting income; you also need to understand the deductions you can leverage to lower your taxable income. Here are some common deductions relevant for startups:
-
Startup Costs: The IRS allows you to deduct up to $5,000 of startup costs in the first year of business, with amortization over 15 years for any remaining costs.
-
Business Expenses: Ordinary and necessary business expenses, such as rent, utilities, and office supplies, can be deducted.
-
Employee Wages: Wages and benefits paid to employees and contractors can be deducted from your taxable income.
-
Depreciation: Significant purchases (like equipment and vehicles) can be depreciated over their useful life.
-
Home Office Deduction: If you operate from home, you might qualify for a home office deduction.
Consult a tax professional to ensure you’re making the most of available deductions.
Seeking Professional Help
Navigating the complexities of tax filings and revenue accounting can be daunting for startup founders. Engaging a qualified accountant or tax advisor with experience in startup finances can be incredibly beneficial. These professionals can provide personalized advice, help you set up accounting systems, and ensure your tax filings are accurate and compliant.
Conclusion
Properly accounting for startup revenue in your tax filings is critical for your business’s success. From understanding revenue recognition principles to choosing the right accounting method and maintaining accurate records, startup founders must be diligent in managing their finances. Additionally, the right deductions can help minimize tax burdens, allowing you to invest more in your startup’s future.
Creating a culture of transparency and responsibility concerning finances from the get-go will not only ease your tax filing process but also lay the foundation for sustainable growth. As you grow and scale your business, these financial practices will be essential in making informed decisions and ultimately achieving your entrepreneurial dreams. Whether you’re a first-time entrepreneur or a seasoned business owner, understanding how to account for revenue properly will empower you to navigate your financial future confidently.
Taking control of your financial health today will propel your startup toward success tomorrow.


