
When you think about retirement, what comes to mind? Palms waving gently in the breeze, a cozy beachside cottage, or perhaps endless travel through exotic locales? If you’re a millennial looking forward to this chapter of life, you might find that retirement feels like a distant dream, or perhaps an overwhelming challenge. However, with the right approach to retirement planning and investing, it’s entirely possible to transform such dreams into reality. In this comprehensive guide, we delve into effective retirement planning for millennials, equipping you with essential tips and strategies to secure your financial future.
Why Retirement Planning Matters
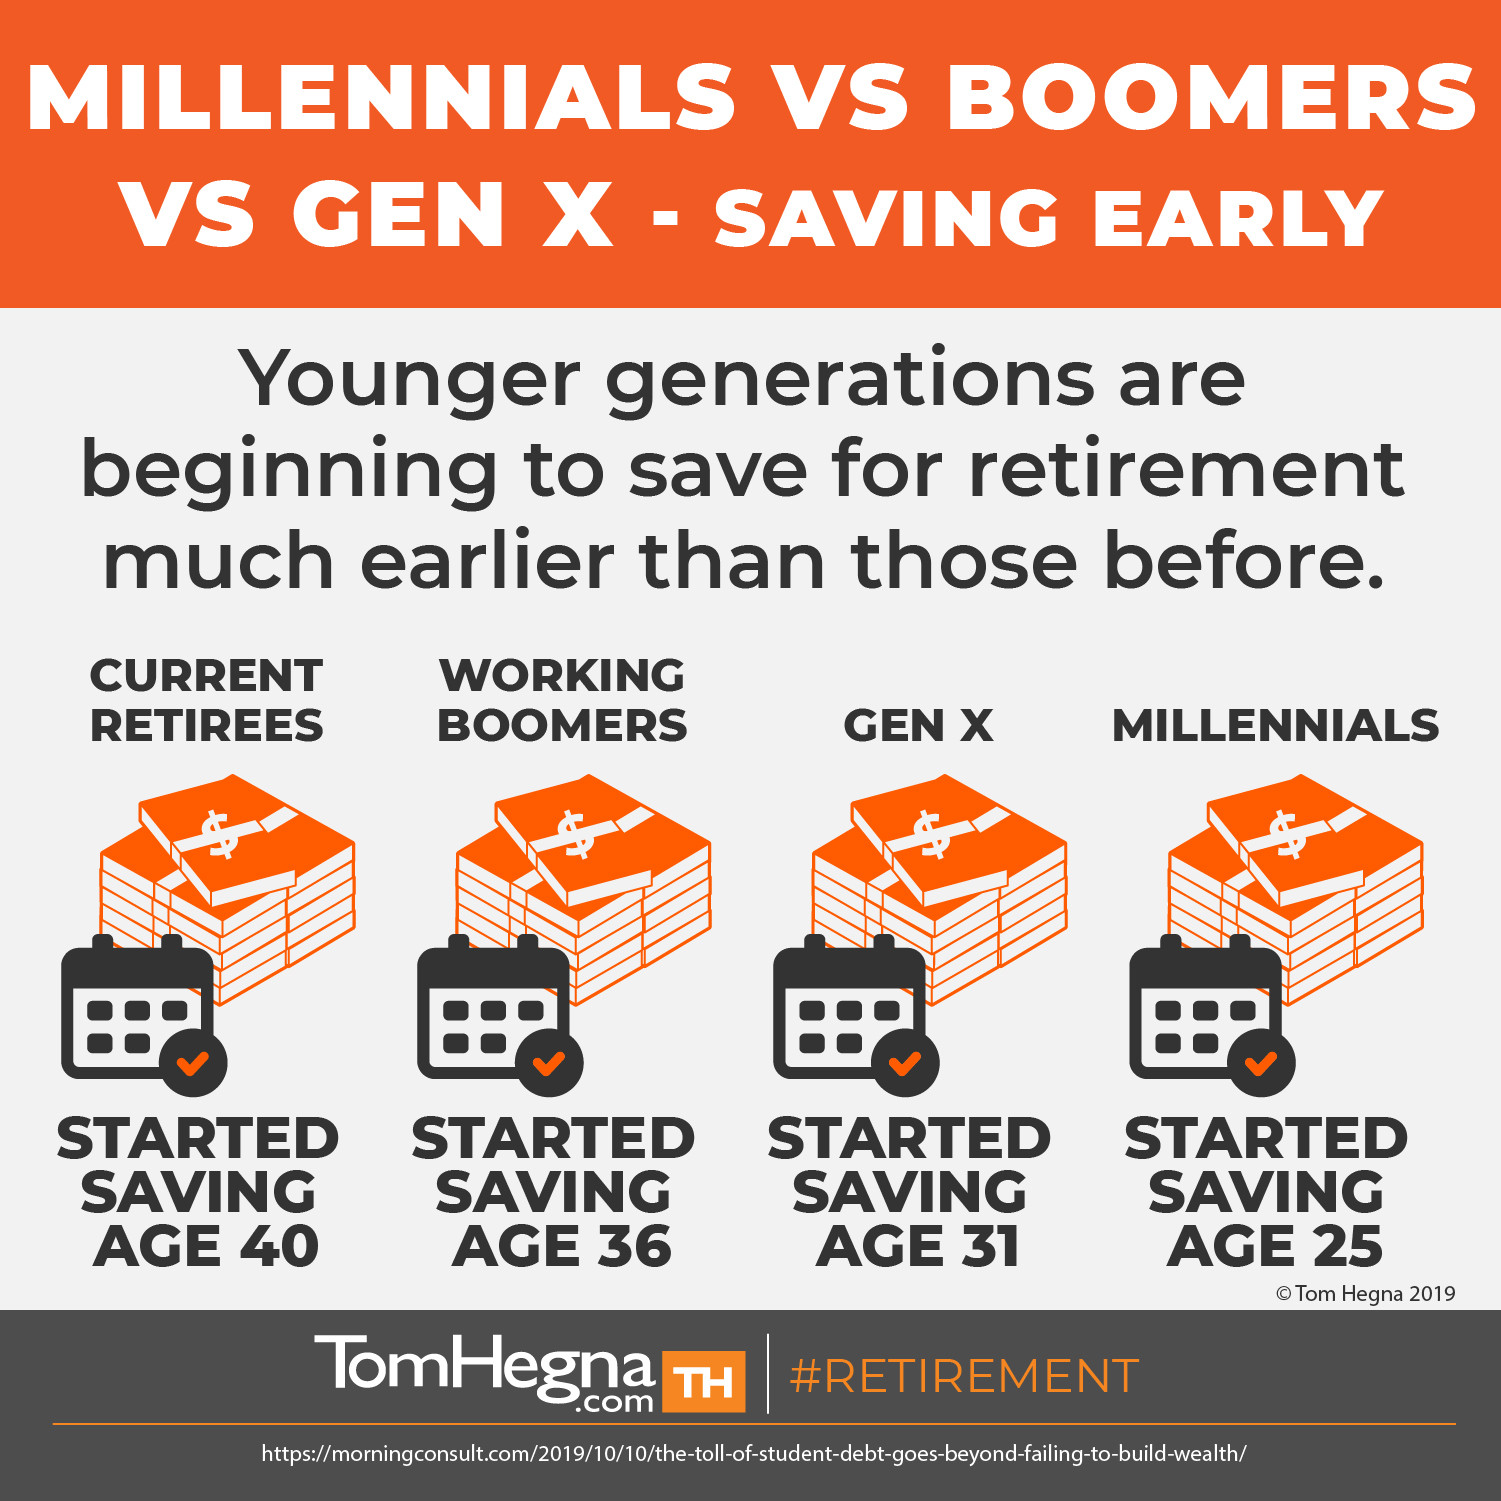
You might wonder why retirement planning is essential, especially if you’re in your 20s or 30s. You may feel you have plenty of time, but the earlier you start, the more robust your financial foundation will be. This crucial time allows your investments to grow through the power of compounding. According to financial experts, starting early can significantly impact how much you can accumulate by the time you’re ready to retire.
Understanding Millennials’ Financial Landscape
To effectively plan for retirement, it’s vital to understand the unique financial challenges millennials face. Student loan debts, escalating costs of living, and the rising price of healthcare are just a few hurdles that can impede retirement savings. Additionally, millennials often prioritize immediate needs such as homeownership, travel, and lifestyle choices over long-term savings. However, integrating smart financial planning into your life doesn’t mean sacrificing enjoyment—it’s about striking a balance.
Step 1: Set Clear Retirement Goals
Before diving into investment options, clarify your retirement goals. Ask yourself:
– At what age do you want to retire?
– What kind of lifestyle do you envision?
– Where would you like to live?
– Do you plan to travel or maintain other interests when you retire?
Once you’ve envisioned your retirement, create specific, measurable, achievable, relevant, and time-bound (SMART) goals. This clarity will help you determine how much you need to save and invest.
Step 2: Know Your Retirement Accounts
Familiarize yourself with the various retirement accounts available, as each serves different purposes and tax implications.
-
401(k) Plans: If your employer offers a 401(k) plan, take advantage of it. Many companies provide matching contributions, essentially free money that can significantly boost your retirement savings. Aim to contribute enough to get the full employer match.
-
Individual Retirement Accounts (IRAs): Options include Traditional IRAs and Roth IRAs. Traditional IRAs allow for tax-deductible contributions, but you’ll pay taxes on withdrawals. Conversely, contributions to a Roth IRA are made with after-tax dollars, and qualified withdrawals in retirement are tax-free.
-
Health Savings Accounts (HSAs): While primarily for medical expenses, HSAs can function as an additional retirement account. Contributions are tax-deductible, and funds can grow tax-free if used for qualified expenses.
Step 3: Create a Budget and Save
Budgeting is essential for financial stability. Track your expenses and determine areas where you can cut back to maximize your savings. Here’s a step-by-step approach to budgeting:
- Assess Your Income: Calculate your net monthly income after taxes and deductions.
- List Your Expenses: Break down fixed expenses (rent, utilities) and variable expenses (entertainment, dining).
- Identify Areas to Cut: Look for patterns in your spending that could be optimized. Can you dine out less or skip that coffee? Every little bit adds up.
- Automate Your Savings: Set up automatic transfers to your retirement accounts each month. Treating your savings like a fixed expense makes it easier to stick to your plan.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
Step 4: Diversify Your Investments
Investing isn’t just about picking stocks; it’s about finding the right mix of assets to ensure stable growth over time. Here are some investment vehicles to consider:
-
Stocks: Investing in individual stocks can offer high potential returns. Research companies you believe will grow or use an index fund that tracks the market, reducing individual risk.
-
Bonds: Bonds typically offer more stability than stocks and generate regular income. They are a great way to balance risk in your portfolio.
-
Mutual Funds and ETFs: These funds pool money from several investors to purchase a diversified portfolio of stocks and bonds. They are an excellent option for those who prefer a hands-off investment approach.
-
Real Estate: Investing in real estate can provide passive income and increase your net worth. Whether through rental properties or real estate investment trusts (REITs), real estate can be a solid addition to your investment strategy.
Step 5: Educate Yourself on Market Trends
The investment landscape is always evolving. Stay informed by reading financial news, attending seminars, or engaging in online courses. Here are some resources to keep you updated:
- Follow financial blogs and YouTube channels.
- Listen to personal finance podcasts.
- Consider joining finance-related online communities.
Understanding market trends can help you make informed decisions and adjust your investment strategy as necessary.
Step 6: Consult a Financial Advisor
As your financial situation grows, it may be worthwhile to consult a financial advisor. A professional can provide personalized advice, develop a comprehensive retirement plan, and assist in navigating investment options. Look for someone with experience working with millennials, as they’ll understand your unique circumstances and goals.
Step 7: Regularly Review Your Plan
Retirement planning isn’t a one-and-done task. It requires periodic reviews and adjustments based on changes in your life circumstances, financial goals, and market conditions. Set a schedule—monthly or quarterly—to assess your progress and make necessary tweaks to your savings and investment strategies.
Step 8: Prioritize Debt Management
High-interest debt, such as credit card balances, can severely hinder your ability to save for retirement. Focus on paying off such debts first. Here’s how you can tackle debt effectively:
-
List Your Debts: Write down all your debts, including interest rates and minimum payments.
-
Create a Payoff Plan: Choose between the snowball method (paying off the smallest debts first) or the avalanche method (focusing on high-interest debts).
-
Negotiate Lower Interest Rates: Contact credit card companies or lenders to ask for lower rates, especially if you have a solid payment history.
Step 9: Embrace Flexibility and Adapt
The world is unpredictable—economic downturns, job changes, and sudden expenses can all alter your financial landscape. Be prepared to adapt your retirement plan to accommodate these shifts. Embrace a flexible mindset and adjust your budget and investment strategy as necessary.
Conclusion: Start Planning Today!
Retirement planning may seem daunting, but by taking small, consistent steps, you can successfully pave the path to financial security. As a millennial, you have a unique opportunity to leverage time for your benefit. By setting clear goals, incorporating smart savings strategies, diversifying your investments, and staying informed, you can build the future of your dreams.
Remember, the journey may be long, but with perseverance, discipline, and a bit of financial savvy, you can retire on your terms – enjoying the lifestyle you’ve envisioned all along. Start now. Your future self will thank you!


