
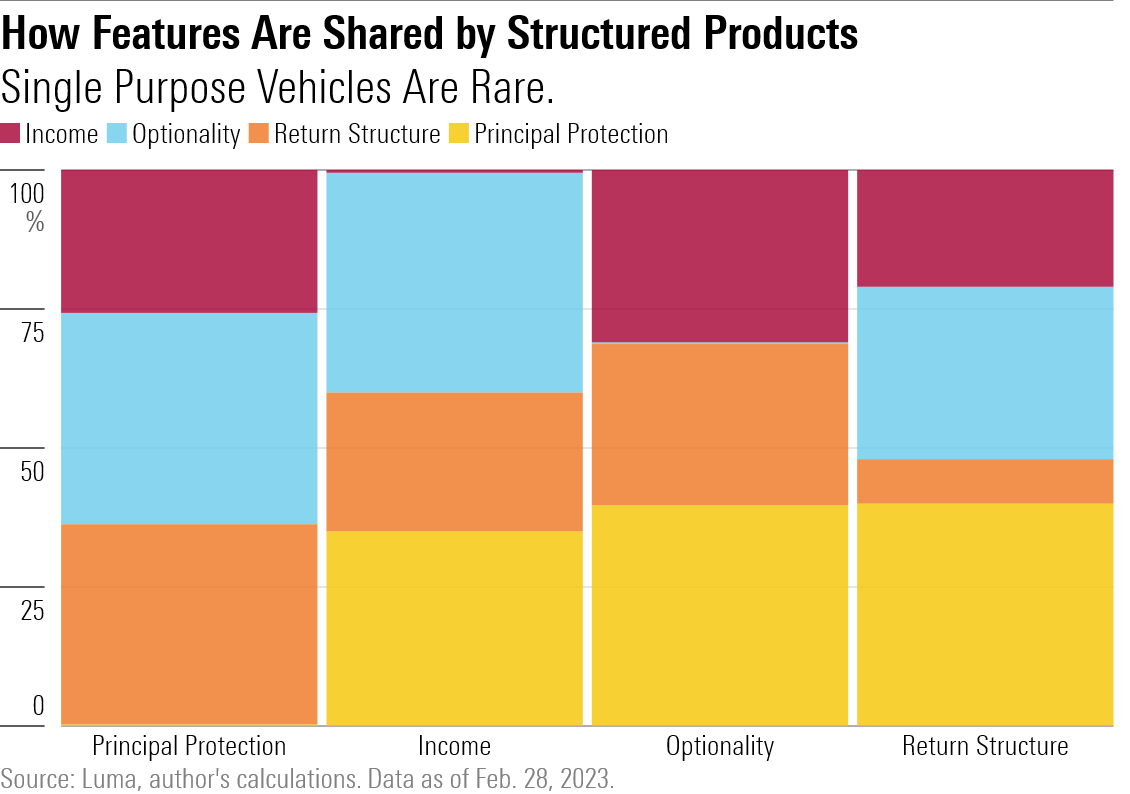
Structured notes—often called structured products—are hybrid financial instruments that combine a traditional bond with one or more derivatives. In the U.S., they are issued primarily by major banks (J.P. Morgan, Morgan Stanley, Citi, Goldman Sachs) and tailored to provide customized exposure to stocks, indices, interest rates, volatility, or commodities.
The appeal is simple: they promise downside protection, enhanced yield, or conditional returns that are hard to replicate with standard investments.
The danger is equally simple: complexity hides risk, and investor outcomes depend heavily on the note’s structure and the issuer’s creditworthiness.
With U.S. Treasury yields still near 4.5% in December 2025 and equity markets trading near record valuations, structured notes have surged back into popularity—especially among income-seeking investors who want protection against volatility.
Structured notes look safe on the surface—but the details decide who profits.
Key Insights
- Structured notes combine a bond component and a derivative component.
- They offer contingent downside protection and enhanced yield, but carry issuer risk.
- U.S. issuance exceeded $120 billion in 2025, up 14% YoY.
- Most popular structures today: buffered notes, autocallable notes, and market-linked CDs.
- Performance depends on the underlying asset, volatility, and interest rates.
What Structured Notes Are
A structured note is built from two parts:
- Bond ComponentEnsures some return of principal (partial or full), depending on note type.
- Derivative ComponentLinks performance to an underlying such as the S&P 500, Nasdaq 100, VIX, gold, oil, or individual stocks.
The combination allows banks to promise customized outcomes—higher yield, downside buffers, or conditional growth.
Example (2025 U.S. market):
A bank issues a 3-year S&P 500 buffered note offering:
- 12% annual coupon
- 20% downside protection
- Full participation up to a cap
If the S&P 500 falls 15% at maturity, investors lose nothing.
If it falls 40%, they lose 20% (after the buffer).
If it rises 10%, they earn 10%.
If it rises 30%, they earn up to the cap (e.g., 18%).
Why Structured Notes Are Popular in 2025
Three macro forces boosted demand:
- High interest rates:With Treasury yields stable above 4.5%, banks can fund attractive coupons.
- Elevated volatility in tech stocks:Higher implied volatility lets banks price richer derivative components.
- Demand for downside protection:Investors fear buying equities near all-time highs and seek conditional protection.
Morningstar’s U.S. Structured Products Outlook 2025 confirms that demand is highest among retirees, high-net-worth investors, and advisors using market-linked CDs in diversified portfolios.
Types of Structured Notes (Most Used in the U.S.)
Buffered Notes
Offer partial downside protection (10–30%) with participation in upside.
Most common note across U.S. brokerage platforms in 2024–2025.
Autocallable Notes
Pay high coupons (9–16%) and automatically redeem if the underlying asset stays above a barrier.
If the underlying drops, coupons may be suspended.
Market-Linked CDs
FDIC-insured principal protection + market-linked upside.
Safer but with capped returns.
Principal-Protected Notes (PPNs)
Return 100% principal at maturity, but upside is limited by caps or participation rates.
Reverse Convertible Notes
High coupons but high risk.
Investor may receive depreciated shares instead of principal.
How Structured Notes Are Valued
Structured notes depend on:
- Interest rates (higher rates = stronger bond component)
- Implied volatility (higher volatility = richer option premiums)
- Underlying asset behavior
- Issuer credit risk
This is why notes from banks with weaker credit ratings pay higher coupons—they compensate for risk.
The Federal Reserve’s Financial Stability Overview stresses that structured products add complexity to household balance sheets and require careful transparency on issuer risk.
Benefits for U.S. Investors
1. Downside Protection
Great for volatile markets where investors want exposure but fear drawdowns.
2. Enhanced Income
Yields often exceed what bonds or dividend stocks pay.
3. Customized Market Exposure
Investors can target specific outcomes (range-bound markets, sideways markets, modest growth scenarios).
4. Lower Entry Cost Than Direct Options Trading
Built-in options exposure with simpler execution through a bank or advisor.
Risks That Investors Overlook
1. Issuer Credit Risk
If the bank fails, protection collapses.
The FDIC’s Quarterly Banking Profile highlights rising credit concentration in structured-product portfolios.
2. Liquidity Risk
Structured notes are hard to sell before maturity and often priced at a discount.
3. Complex Terms
Caps, barriers, buffers, and triggers can drastically change returns.
4. Market Gaps and Tail Risk
During extreme events, barriers may be breached instantly—invalidating protection.
5. Opportunity Cost
Capped upside can cause underperformance during strong bull markets.
Morningstar warns that 36% of structured notes underperformed simple index ETFs in 2023–2025, mainly due to return caps and barrier breaches.
Structured Notes vs. ETFs
| Feature | Structured Notes | ETFs |
|---|---|---|
| Liquidity | Low | High |
| Costs | Embedded, opaque | Low and transparent |
| Downside Protection | Possible | None |
| Upside | Capped | Unlimited |
| Complexity | High | Low |
Structured notes are tools—not core holdings. ETFs remain more efficient long-term vehicles.
When Structured Notes Make Sense (2025 Conditions)
✔ When markets are expensive
Forward S&P 500 P/E ~20.3× in Dec 2025 → capped returns acceptable.
✔ When volatility is elevated
Implied volatility around 17–20 makes options cheaper for banks to package.
✔ When interest rates are high
4.5% Treasury yields boost the bond component and fund attractive buffers.
Example: 2025 S&P 500 Autocallable Note
- 15% annual coupon
- Autocall if index stays above 90% of initial value
- 30% downside barrier
- 3-year maturity
Scenario outcomes:
- Flat or up market → Autocalls early with 15% coupon
- Moderate correction (−10 to −25%) → Coupons paid, no loss
- Severe crash (below −30%) → Investor takes the full loss beyond barrier
Good for sideways markets—not suitable for bearish environments.
Who Should Avoid Structured Notes
- Investors needing liquidity
- Investors who don’t understand derivatives
- Investors who chase yield without studying barriers and triggers
- Anyone uncomfortable with issuer credit risk
As explained in Understanding the P/E Ratio and Understanding the Beta Coefficient, traditional stocks offer transparent valuation drivers—structured notes do not.
Outlook for 2026
Morningstar expects:
- Continued growth in FDIC-insured market-linked CDs
- Increased regulatory scrutiny on illiquid retail products
- Rising buffers as interest rates slowly decline in late 2026
- More AI-driven issuance tailored to specific volatility regimes
Structured notes will remain popular as long as investors want both protection and yield—but complexity will keep them a niche tool for informed buyers.
Conclusion
Structured notes allow investors to customize risk and return in ways traditional assets cannot.
But they’re complicated, illiquid, and dependent on issuer strength.
“If you don’t understand every line of a structured note’s term sheet, you probably shouldn’t buy it.”
Used carefully, they can complement—but never replace—core portfolio holdings like ETFs, Treasuries, and blue-chip U.S. stocks.
Disclaimer:
The information in this article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com assumes no responsibility for losses resulting from use of this information.


