
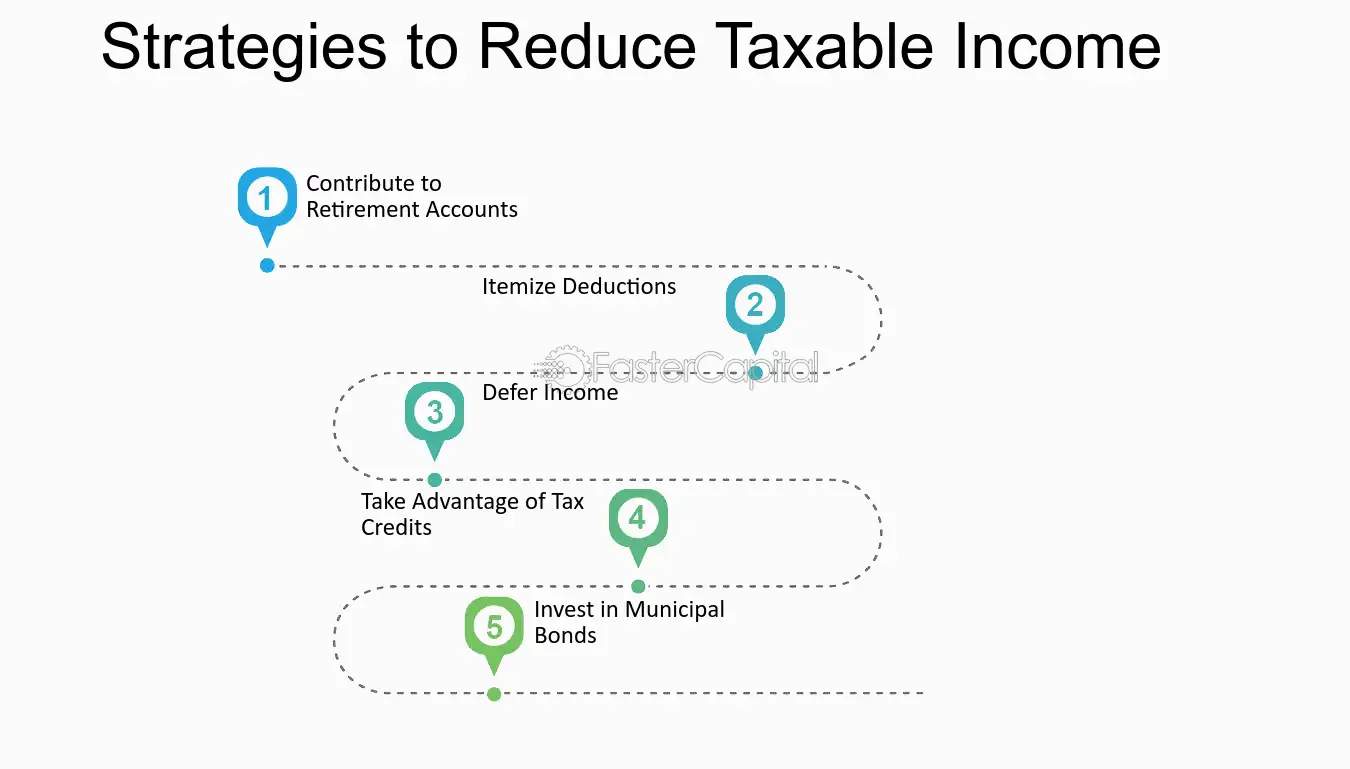
Starting a new business is a thrilling adventure full of opportunities and challenges. One of the most significant challenges founders face is navigating the complex world of taxes. While taxes are an inevitable part of running a business, there are strategies to reduce the taxable income of your startup, allowing you to reinvest more of your profits back into your company. This article will explore the best strategies for reducing taxable startup income, helping you maximize your resources and thrive as an entrepreneur.
Understanding Startup Income
Before diving into tax-reduction strategies, it’s crucial to grasp what constitutes startup income. Startup income can include revenue generated from sales, services, or other activities that contribute to your business. Understanding how this income is classified can help you develop effective strategies for lowering your tax burden.
For startups, the IRS generally categorizes income into two parts: ordinary income and capital gain. Ordinary income is the money earned from the day-to-day operations of your business, while capital gains stem from selling business assets like stocks or equipment at a profit. Recognizing the type of income generated by your startup can help you strategize appropriately.
1. Leverage Deductions Effectively
One of the most powerful tools for reducing taxable income is knowing what deductions you qualify for as a startup. Several deductions available to business owners can significantly lower your taxable income:
a) Startup Costs
The IRS allows new businesses to deduct certain startup costs incurred before the business begins operations. These may include:
- Market research expenses
- Advertising costs
- Employee training
- Professional fees
Startups can deduct up to $5,000 in qualified startup expenses in the first year, with any remaining costs amortized over the next 180 months. Keeping meticulous records of these expenses and working with a tax professional can ensure you maximize these deductions.
b) Operational Expenses
All necessary expenses incurred in running your business can generally be deducted. This includes:
- Rent for office space
- Utilities and internet
- Salaries and wages
- Inventory purchases
- Office supplies
It’s essential to document these expenses accurately. Use accounting software or hire an accountant to ensure that every eligible expense is accounted for during tax time.
2. Optimize Retirement Plans
Setting up a retirement plan not only benefits your future but can also lower your taxable startup income. Contributions to retirement plans can often be deducted from your taxable income, reducing your overall tax burden. Here are a couple of retirement plans suited for startups:
a) Solo 401(k)
If you’re a sole proprietor or a small business owner with no full-time employees (other than your spouse), a Solo 401(k) allows for substantial annual contributions. In 2023, you can contribute up to $22,500 as an employee, plus an employer contribution, potentially reaching a total of $66,000.
b) SEP IRA
A Simplified Employee Pension (SEP) IRA is another excellent option for self-employed individuals. As an employer, you can contribute up to 25% of your income, capped at $66,000 for 2023. This can significantly lower your taxable income while simultaneously building your retirement funds.
3. Take Advantage of Tax Credits
In addition to deductions, tax credits can directly reduce your tax liability, making them highly advantageous. Many startups may qualify for various federal and state tax credits, such as:
a) Research and Development Tax Credit
If your startup is involved in developing new products, processes, or software, you may qualify for the Research and Development (R&D) tax credit. This credit not only incentivizes innovation but can also be a substantial savings opportunity for qualifying startups.
b) Hiring Credits
Certain hiring credits may be available to your startup if you employ specific groups, such as veterans, individuals from low-income communities, or those with disabilities. For example, the Work Opportunity Tax Credit (WOTC) rewards businesses for hiring unemployed veterans or individuals from designated groups, providing a substantial tax break for eligible hires.
4. Embrace Home Office Deductions
If you run your startup from home, there’s an opportunity to leverage home office deductions. The IRS allows you to deduct a portion of your home expenses attributed to your business use of the home. This can include:
- A percentage of your rent or mortgage
- Utilities
- Internet costs
- Home insurance
To qualify for this deduction, your home office must be used regularly and exclusively for business purposes. Keeping detailed records and understanding the IRS guidelines can maximize your home office deductions.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
5. Implement Cost Segregation
Cost segregation is a tax-saving strategy used by businesses that own real estate. This method allows you to separate the components of a property to accelerate depreciation for tax purposes, reducing immediate taxable income.
By conducting a cost segregation study, you can categorize various components of your buildings (such as furniture, fixtures, and certain improvements) and depreciate them over shorter lives, leading to significant tax savings in the early years of owning the property. This is particularly beneficial for startups planning to invest in commercial space.
6. Revisit Your Business Structure
The legal structure of your business can impact your tax liability. Typically, businesses can be classified as either sole proprietorships, partnerships, limited liability companies (LLCs), or corporations. Each structure has its benefits and drawbacks in terms of taxes.
For example:
- Sole Proprietorships: Simple and straightforward but leave owners personally liable for business debts.
- LLCs: Provide limited liability while allowing pass-through taxation, meaning profits and losses are reported on your personal tax return. This may reduce taxable income if losses occur in the early years.
- S Corporations: Allow owners to pay themselves as employees, potentially lowering self-employment taxes.
Consult with a tax advisor to determine which business structure is best suited for your startup, considering long-term goals and financial strategy.
7. Maintain Proper Accounting Records
Accurate accounting records are vital for any startup looking to minimize taxable income. Maintaining proper records ensures you capture all eligible deductions, and it can help when it’s time to file taxes. Additionally, organized documentation makes it easier to track your financial performance and make informed business decisions.
Consider investing in accounting software like QuickBooks or Xero or hire a professional accountant. With good record-keeping practices in place, you can stay ahead in managing your finances and taxes.
8. Keep Business and Personal Finances Separate
When starting your business, it’s vital to keep personal and business finances separate. Open a dedicated business bank account and use it exclusively for business transactions. Not only does this simplify your accounting, but it also ensures that you defend your deductions in the event of an audit.
By keeping accurate financial records and maintaining clear boundaries between your personal and business expenses, you can identify all eligible deductible expenses better and minimize the chances of missing out on tax savings.
9. Consult a Tax Professional
Lastly, one of the best strategies for reducing your taxable startup income is consulting a tax professional. They can help you identify available deductions and credits specific to your industry and business structure. Tax laws vary, and the knowledge of a certified public accountant (CPA) or tax advisor can streamline your tax strategy and optimize your cash flow.
Utilizing the expertise of a tax professional can equip you with the insights needed to make informed decisions, ultimately saving you time and money.
Conclusion
Starting a new company comes with a myriad of responsibilities, including navigating the ins and outs of taxes. By understanding the various strategies for reducing your startup’s taxable income—such as maximizing deductions, exploring tax credits, and seeking professional advice—you can significantly minimize your tax burden and position your business for long-term success. Remember, every dollar saved on taxes is a dollar that can be reinvested into your startup, fueling your growth and sustainability in a competitive landscape.
As you embark on your entrepreneurial journey, keep these strategies in mind, and don’t hesitate to seek support from tax professionals who can guide you through the complexities of the tax system, ensuring your focus remains on building a thriving business.


