
As a startup founder, you’re likely wearing many hats. You’re the visionary, the marketer, the salesperson, and yes, even the accountant from time to time. One of the most critical aspects of managing a startup is understanding your tax obligations. As we step into 2024, it’s essential to grasp the nuances of filing taxes for your startup to ensure compliance and optimize your financial health. This ultimate guide will walk you through the critical steps, important deductions, and strategic tips to effectively file taxes for your startup this year.
Understanding Your Startup’s Tax Structure
Before diving into the nuts and bolts of filing taxes, it’s crucial to understand the different business structures available for startups. Your choice of entity—whether a sole proprietorship, partnership, LLC, or corporation—will significantly impact your tax obligations and benefits.
Sole Proprietorship
A sole proprietorship is the simplest business structure. As a sole proprietor, you report your business income and expenses on your personal tax return (Form 1040, Schedule C). While this structure is easy to manage, remember that you’re personally liable for all debts and obligations incurred by the business.
Partnership
If you start your business with one or more partners, you’ll likely form a partnership. Partnerships must file an informational return (Form 1065) but do not pay federal income taxes themselves. Instead, profits or losses are passed through to individual partners, who then report them on their personal tax returns.
LLC (Limited Liability Company)
An LLC combines the flexibility of a sole proprietorship or partnership with the liability protection of a corporation. By default, single-member LLCs are treated as sole proprietorships, while multi-member LLCs are treated as partnerships for federal tax purposes. However, LLCs also have the option to elect to be taxed as a corporation.
Corporation
Corporations are more complex and are taxed independently from their owners. Although this structure offers liability protection, it comes with higher compliance costs and regulatory obligations. Corporations file tax returns using Form 1120 and may choose between being taxed as a C-Corporation or an S-Corporation.
Registering for an EIN
Once you’ve decided on a business structure, the next step is obtaining an Employer Identification Number (EIN) from the IRS. An EIN is a unique identifier for your business and is required for most business tax filings. It’s essential for payroll processing, as well as opening a business bank account.
Here’s how to apply for an EIN:
1. Visit the IRS website: The application is free and can be filled out online.
2. Provide necessary information: This includes your business name, structure, and your personal identification information.
3. Receive your EIN immediately: Once you complete the application, you’ll receive your EIN instantly.
Key Tax Deadlines for Startups in 2024
Filing taxes can be a daunting process, but keeping track of key deadlines can help alleviate some stress. Here’s a list of important dates to remember for 2024:
- January 15, 2024: Fourth Quarter estimated tax payment due for sole proprietors, partners, and S-Corporation shareholders.
- March 15, 2024: Deadline for S-Corporations and partnerships to file returns (Form 1120S and Form 1065).
- April 15, 2024: Deadline for C-Corporations to file federal tax returns (Form 1120) and for sole proprietors to file their personal tax return (Form 1040, Schedule C).
- September 15, 2024: Third quarter estimated tax payments due for sole proprietors, partners, and S-Corporation shareholders.
- October 15, 2024: Extended deadline for S-Corporations and partnerships.
Staying organized and setting reminders for these important deadlines will help you avoid costly penalties.
Deductions and Credits for Startups
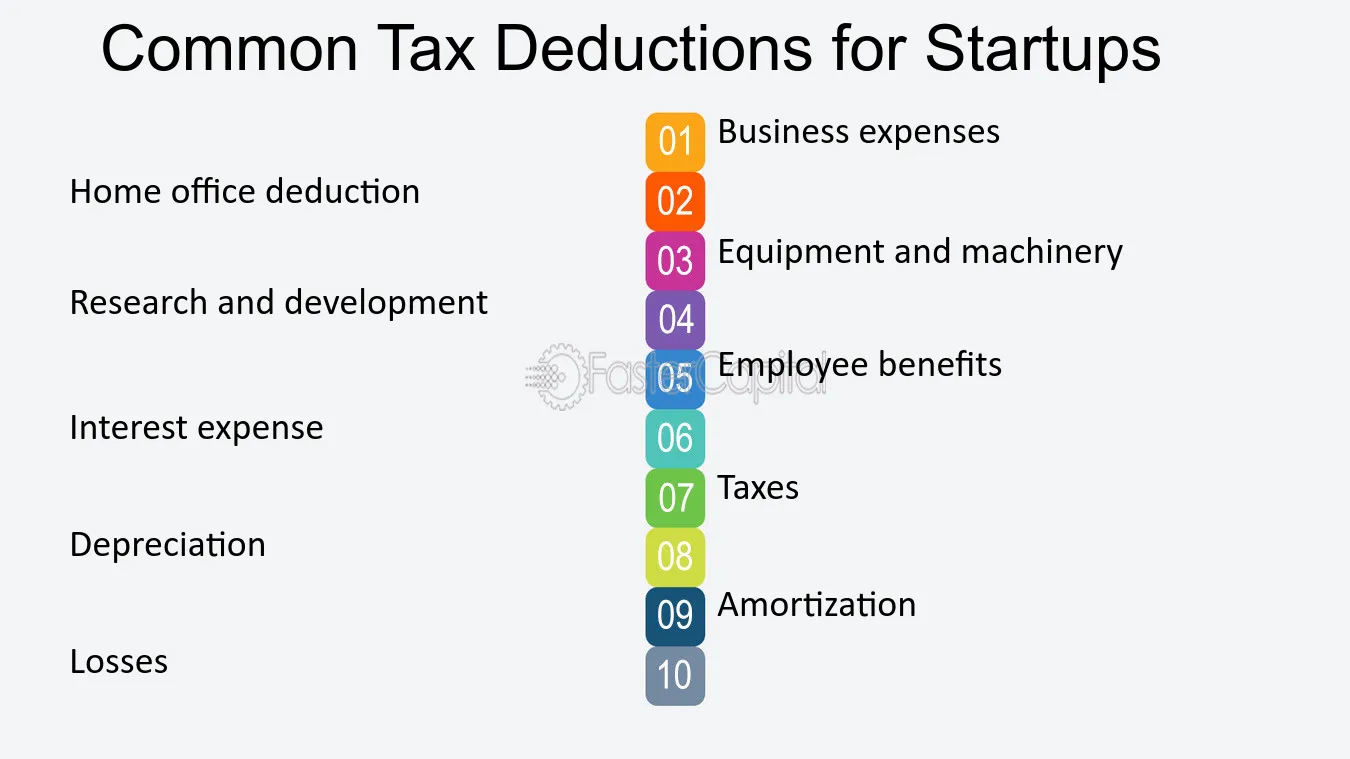
Understanding tax deductions and credits is essential to minimize your taxable income and maximize your returns. As a startup, take advantage of the following deductions and credits available in 2024:
1. Startup Costs Deduction
According to the IRS, you can deduct up to $5,000 in startup costs in your first year if your total startup expenditures are $50,000 or less. If your startup costs exceed $50,000, the $5,000 deduction gradually decreases. Be sure to keep all receipts and documentation of your expenses!
2. Home Office Deduction
If you’re running your startup from home, you may qualify for a home office deduction. This deduction applies if a portion of your home is used exclusively for business activities. You can choose between the simplified option, which allows a flat rate deduction of $5 per square foot of your home office (up to 300 square feet), or the regular method, which involves calculating actual expenses related to your home office.
3. Business Vehicle Expenses
If you use a vehicle for business purposes, you can deduct either the actual expenses incurred (such as fuel, maintenance, and insurance) or use the standard mileage rate, which the IRS updates annually. In 2024, the standard mileage rate is expected to be around $0.65 per mile. Keep accurate records of your mileage and expenses to claim this deduction.

- Overcome negative thought patterns, reduce stress, and live a worry-free life
- Overthinking is the biggest cause of unhappiness
- Don't get stuck in a never-ending thought loop
- Stay present and keep your mind off things that don't matter, and never will
- Break free of your self-imposed mental prison
4. Qualified Business Income (QBI) Deduction
If your startup is structured as an LLC, partnership, or S-Corporation, you may be eligible for the QBI deduction, which allows you to deduct up to 20% of your qualified business income. This deduction is subject to various limitations based on your taxable income, so it’s essential to consult a tax professional to navigate its complexities.
5. Employee Benefits
Offer benefits such as health insurance, retirement plans, and other employee perks can provide tax advantages for both your business and employees. Contributions to COBRA or Flexible Spending Accounts (FSAs) are tax-deductible for employers and can significantly reduce taxable income.
6. Research and Development (R&D) Tax Credit
If your startup is involved in developing new products, processes, or software, you may qualify for the R&D tax credit. This credit incentivizes innovation by allowing eligible businesses to receive a tax credit against federal income tax obligations.
7. Cost of Goods Sold (COGS)
If your startup involves selling products, you can deduct the cost of goods sold, which includes direct costs related to production, such as materials and labor. Properly tracking your inventory and related costs is vital to maximizing this deduction.
Common Mistakes to Avoid When Filing Taxes
Navigating the complex world of tax filings can be overwhelming, but avoiding common pitfalls can save your startup from unnecessary headaches. Here are some mistakes to watch out for:
1. Failing to Keep Accurate Records
Maintain meticulous financial records year-round, including receipts for all business-related expenses. Utilize accounting software to track expenses, invoices, and payments. This practice simplifies the filing process and provides documentation in case of an audit.
2. Ignoring Estimated Tax Payments
Many startup founders forget that they are responsible for estimated taxes if they expect to owe $1,000 or more in tax when filing. Be proactive and set aside funds to cover these payments and avoid penalties.
3. Neglecting to Separate Personal and Business Expenses
One of the biggest blunders new entrepreneurs make is mixing personal and business expenses. Open a separate business bank account and credit card. This separation not only simplifies bookkeeping but also protects your personal assets.
4. Overlooking Deductions
It’s easy to miss out on valuable deductions, especially in the early stages of your business when expenses are high. Stay informed about available deductions and consult a tax professional to ensure you’re maximizing potential savings.
The Importance of Hiring a Tax Professional
While it’s possible to file taxes independently, hiring a tax professional can be invaluable for your startup. As tax laws evolve and become more complex, a knowledgeable tax advisor can help you navigate compliance issues, identify potential deductions, and keep your business organized.
Choosing the Right Tax Professional
When selecting a tax professional, consider the following:
- Expertise: Look for someone with experience in startup taxation and a solid understanding of your industry.
- Certifications: Ensure they’re a licensed CPA, enrolled agent, or tax attorney.
- Communication: Choose a professional who is approachable and willing to explain tax strategies clearly.
Planning Ahead for Next Tax Season
As you wrap up your tax filing process for 2024, it’s time to start planning for the next season. Implementing proactive strategies will make the next tax season less daunting.
1. Establish a Budget for Taxes
Set aside a percentage of your revenue throughout the year specifically for taxes. This budgeting strategy will help you avoid cash flow issues when tax payments are due.
2. Regularly Review Financial Statements
Monthly or quarterly reviews of your financial statements help identify trends and ensure that you’re on track. Analyzing your income and expenses will empower you to make informed decisions for your startup.
3. Stay Informed on Tax Changes
Tax laws are subject to change, and new incentives may become available. Subscribe to relevant financial or tax-related publications and follow the IRS for updates.
Conclusion
Filing taxes for your startup doesn’t have to be an overwhelming chore. By understanding your business structure, keeping organized records, and staying informed about deductions and credits, you can successfully navigate the tax landscape in 2024. Don’t hesitate to seek the advice of a tax professional to assist you in optimizing your tax strategy. With the right preparation and proactive approaches, you can focus on what matters most: growing your startup into a successful and thriving business.


