
Goldman Sachs flags the equal-weight S&P 500 at 30-year low breadth—P/E near 40, Shiller CAPE at 39.5, sell-off risk rising. What this rare warning means for U.S. portfolios in 2026 and how to reposition now. (157 characters)
While the headline S&P 500 trades near record highs and financial media celebrates another bull market milestone, a critical signal buried inside Goldman Sachs’ research division is flashing the loudest warning in over three decades. The Equal-Weight S&P 500—an index that strips out mega-cap dominance and gives identical representation to all 500 constituents—recorded its worst start to a year since 1995, according to Goldman Sachs analysts. That one statistic reframes everything U.S. investors think they know about the current market environment.
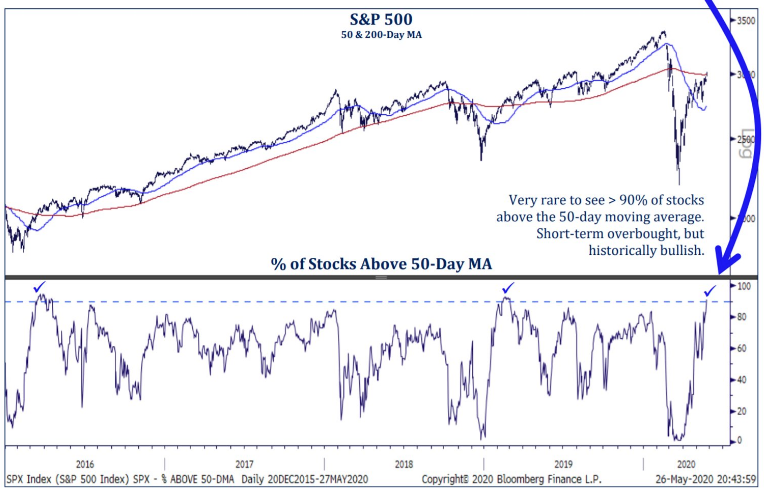
And crucially, Goldman’s own research suggests the worst may not yet have arrived. The P/E ratio on the equal-weight index confirms the broader market is overvalued, feeding fears of an imminent and significant sell-off wave that could catch complacent investors badly off guard.
Key Insights
- 30-Year Low Breadth: The Equal-Weight S&P 500’s worst January performance since 1995 signals a dangerous narrowing of participation.
- Valuation Extremes: Shiller CAPE at 39.5 and forward P/E at 22x are near levels last seen in the dot-com bubble.
- Goldman’s Warning: Equal-weight P/E is in the 95th percentile versus all readings since 1990—”modestly above fair value.”
- Five-Company Market: Magnificent 7 concentration means the headline index masks the reality that most stocks are already declining.
- Historical Precedent: Every prior breadth collapse of this magnitude preceded a correction of at least 15-20%.
- Repositioning Playbook: Defensive sectors, protective puts, cash reserves, and equal-weight ETFs are the rational response.
What Is the Equal-Weight S&P 500—and Why Does It Matter More Than You Think?
The standard S&P 500 index that anchors every CNBC segment and 401(k) statement is market-cap weighted—meaning larger companies occupy proportionally larger slices of the index. Apple, Microsoft, Nvidia, Amazon, and Alphabet together represent over 25% of the entire index. When these five companies rally, the headline index rises even if 400 other companies are quietly bleeding.
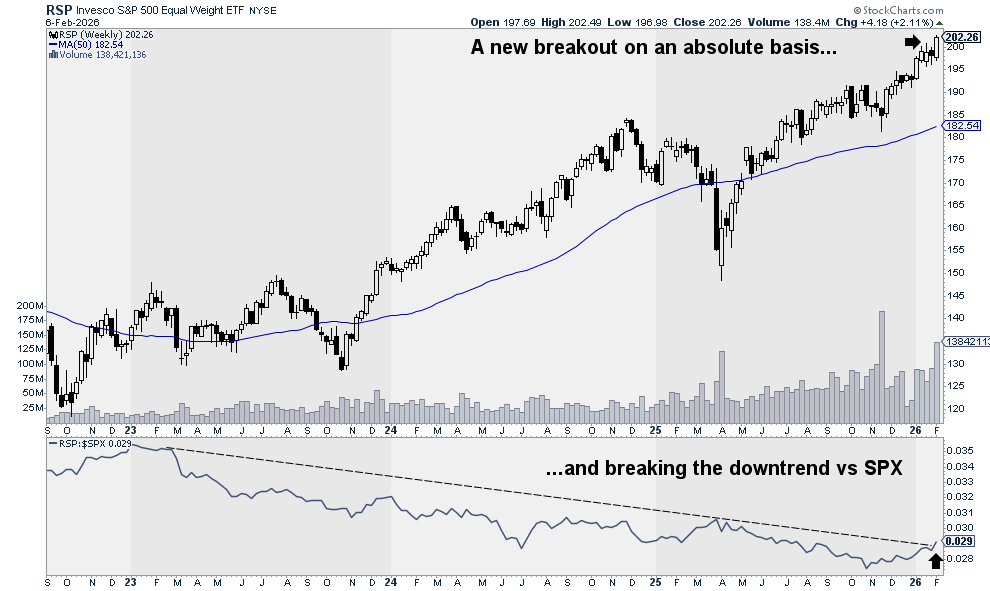
The Equal-Weight S&P 500 (SPW), tracked by the Invesco S&P 500 Equal Weight ETF (RSP) and calculated by S&P Global, corrects for this distortion by assigning precisely 0.2% to every single constituent regardless of market capitalization. Apple and a mid-sized regional insurer carry identical weight. This means SPW is a genuine representation of the average stock’s performance—the actual health of the market’s breadth rather than its most glamorous headline.
When SPW dramatically underperforms the cap-weighted SPX, the message is unambiguous: a small number of mega-cap names are artificially propping up the headline while the median stock deteriorates. This divergence is historically one of the most reliable leading indicators of an impending broad market correction.
Goldman Sachs’ Research: The Numbers Behind the Warning
Goldman Sachs’ quantitative research division flagged several metrics that collectively paint a sobering picture. The equal-weight S&P 500’s opening performance in 2026 was the worst since 1995—a period that, incidentally, preceded the most extreme speculative bubble in modern financial history as the Nasdaq nearly tripled between 1995 and 2000 before losing 78% of its value.
Goldman simultaneously noted that the equal-weight index’s price-to-earnings multiple of approximately 17x places current valuations in the 95th percentile of all readings since 1990. In plain English: only 5% of all observations over the past 35 years have seen the average S&P 500 stock priced this expensively. The bank’s analysts concluded bluntly that the equal-weight index is “modestly above fair value implied by the macro backdrop”—institutional language for “overvalued.”
The Shiller CAPE ratio, which smooths earnings over a full decade to eliminate cyclical distortions, stood at 39.51entering 2026—far above its historical median of 16 and approaching the 44 peak recorded at the exact top of the dot-com bubble in March 2000. NYU professor Aswath Damodaran, one of the most respected valuation authorities in U.S. finance, confirmed that by every PE measure, the S&P 500 entering 2026 was at levels “higher than at any extended period in history, perhaps with the exception of the late 1990s.”
The forward P/E ratio, based on expected next-twelve-months earnings, sat at approximately 22x according to FactSet Research—above both the five-year (19.8x) and ten-year (17.9x) historical averages. The Buffett Indicator—total market capitalization divided by GDP—reached 215%, nearly double its long-term equilibrium and matching the elevated readings last seen at the 2000 and 2021 peaks.
What Happens When Breadth Collapses: The Historical Record
Market breadth deterioration of this magnitude is not a novelty. It has appeared, with striking consistency, as a precursor to every major U.S. equity market correction over the past three decades. The pattern unfolds in a predictable sequence that Goldman’s research team has documented across multiple market cycles.
In 1999-2000, the cap-weighted S&P 500 soared while the equal-weight index peaked eighteen months earlier—a divergence that perfectly foreshadowed the ensuing 49% decline in the headline index and near-total obliteration of tech valuations. In 2006-2007, breadth began deteriorating across financials and small caps while the Dow Jones continued setting records, signaling the credit crisis six months before it became headline news. In 2021, meme stocks and SPAC collapses began cascading through the equal-weight index in Q4 while headline indices held firm, preceding the 2022 bear market that eventually hit the cap-weighted index.
The current pattern—Magnificent 7 propping SPX, equal-weight posting 30-year worst performance—rhymes most closely with late 1999 in terms of breadth structure and valuation, with one significant difference: in 1999, the economy was running hot with genuine earnings acceleration. In 2026, Goldman projects only 7% EPS growth for the S&P 500—solid but insufficient to justify CAPE ratios approaching the dot-com peak.
The Magnificent 7 Concentration Problem
Understanding the current breadth warning requires confronting one uncomfortable reality about the U.S. stock market: it has become dangerously concentrated. The Magnificent 7—Apple, Microsoft, Nvidia, Alphabet, Amazon, Meta, and Tesla—collectively represent over 30% of the cap-weighted S&P 500’s total market capitalization and drove more than 60% of the index’s gains in 2024-2025.
This concentration creates a mathematically fragile structure. When 30% of the index is performing and 70% is struggling or declining, the headline number remains positive while the average investor’s diversified portfolio bleeds. It also means that any disappointment from these seven companies—an earnings miss, a regulatory shock, a valuation re-rating driven by rising Treasury yields—instantly transmits into a headline index sell-off amplified by the starting concentration.
Goldman Sachs has explicitly flagged the risk of what it calls a “catch down” scenario: rather than the struggling 493 companies catching up to Magnificent 7 valuations (catch-up), markets reprice downward toward the weakened majority (catch-down). With equal-weight P/E already at the 95th percentile, the firm considers a dramatic catch-up “unlikely,” pointing instead to a scenario where valuations across the entire index converge lower.
Why Overvaluation Alone Doesn’t Trigger Crashes—But Does Amplify Them
One critical nuance that Goldman’s research acknowledges and that every U.S. investor must internalize: overvaluation is not a timing tool. The CAPE ratio exceeded 25 in 1996—four years before the dot-com crash. Professor Damodaran has spent decades demonstrating that high P/E ratios would have kept investors out of U.S. equities for most of the past decade, costing them enormous compounded returns.
What overvaluation does do—with historical consistency—is dramatically amplify the severity of corrections when catalysts arrive. At a CAPE of 40, there is almost no earnings growth scenario capable of justifying further multiple expansion. Returns must come entirely from earnings—Goldman’s 7% EPS growth projection implies roughly 7% expected returns, assuming no multiple compression. If any negative catalyst arrives—a Fed policy mistake, a China demand shock, Japan’s debt crisis triggering Treasury yield spikes, or simply an earnings season that disappoints relative to elevated expectations—the correction from CAPE 40 is structurally larger than from CAPE 20.
The Motley Fool’s analysis of CAPE ratio historical behavior found that when it exceeds 35, the S&P 500 has typically declined an average of 4% over the subsequent twelve months—with the distribution heavily skewed toward large drawdowns when corrections do materialize.
The Sell-Off Risk Goldman Is Flagging: Timing and Triggers
Goldman Sachs research does not predict an imminent crash—its base case for 2026 actually calls for a 12% S&P 500 return, driven by continued Fed rate cuts and 7% earnings growth. But the firm simultaneously identifies three scenarios where the equal-weight breadth deterioration becomes a full-blown sell-off:
Scenario 1 – Catch-Down Valuation Reset: Magnificent 7 earnings disappoint, triggering multiple compression across the entire index. Given that five companies trade at average P/E ratios of 35-50x, even a modest growth deceleration justifies 20-30% individual stock corrections that drag down the headline index.
Scenario 2 – Macro Shock Amplification: An external catalyst—Japan’s JGB market dislocation, a geopolitical energy shock, or a Fed policy error—arrives in a market already stretched to the 95th valuation percentile. The drawdown from such a starting point is historically 40-60% deeper than from median valuations.
Scenario 3 – Rotation Without Recovery: Capital continues rotating from mega-cap tech into value, small-caps, and international equities, causing prolonged underperformance in the indices that dominate most American 401(k)s without ever producing the dramatic single-day sell-off that triggers media coverage—the slow bleed scenario that historically damages retail investor returns most severely.
What This Means for Your Portfolio: The Repositioning Playbook
Understanding the equal-weight warning is only valuable if it translates into actionable portfolio decisions. The rational response to a market in the 95th valuation percentile with collapsing breadth is not panic liquidation—it is disciplined rebalancing toward resilience.
Reduce Magnificent 7 Concentration
Most U.S. investors in standard index funds are dramatically overweight the Magnificent 7 without realizing it. A standard SPY or VOO position allocates 30%+ to seven companies. Consider switching a portion toward RSP (Invesco S&P 500 Equal Weight ETF) or sector ETFs in healthcare, energy, and consumer staples—areas trading well below average historical valuations. RSP’s equal-weight structure recently hit a fresh record high according to Bloomberg, suggesting the rotation is already underway institutionally.
Add Protective Puts on Concentrated Positions
For portfolios with large unrealized gains in Magnificent 7 names, buying protective puts captures the asymmetry perfectly: defined, limited cost for unlimited downside protection. A 5% OTM SPY put expiring in 90 days costs approximately 1-1.5% of notional value—cheap insurance against a catch-down scenario that Goldman puts at non-trivial probability.
Raise Cash Tactically
Goldman’s own research confirms the S&P 500 median constituent is trading 11% below its 52-week high while the headline index is near records—this dispersion creates opportunities for stock pickers and creates dry powder value for patient investors. A 10-15% cash reserve allows opportunistic buying during corrections without the forced selling that destroys retail investor returns.
Rebalance Toward Value and Small Caps
Goldman explicitly favors value stocks and small-caps for 2026 catch-up trades. The Russell 2000, which Goldman projects could deliver returns similar to the S&P 500 for the full year, trades at dramatically cheaper valuations than Magnificent 7 names. IWM (iShares Russell 2000 ETF) and VTV (Vanguard Value ETF) are the clean execution vehicles.
Use the RSP-SPY Spread as a Dashboard
Monitor the performance gap between RSP and SPY weekly. When RSP begins outperforming SPY consistently, it signals genuine breadth recovery and validates risk-on positioning. When SPY continues outpacing RSP as it has in early 2026, the warning signal remains active and defensive positioning remains warranted.
The Bull Case: Why Goldman Still Expects a 12% Return
Intellectual honesty requires acknowledging the counterargument. Goldman Sachs, despite issuing the equal-weight breadth warning, maintains a 12% S&P 500 return forecast for full-year 2026. The bull case rests on three pillars:
First, the Federal Reserve’s two anticipated rate cuts of 25bps each in 2026 maintain a historically supportive backdrop—Bank of America data shows the S&P 500 gains an average of 1.7% per month during rate-cutting regimes versus losses of 0.5% during rate hikes.
Second, GDP growth of 2.7% projected by Goldman creates a genuine earnings tailwind—7% EPS growth compounds meaningfully over a multi-year horizon even from elevated starting valuations.
Third, Trump’s deregulation, the One Big Beautiful Bill’s tax cut provisions, and ongoing AI-driven productivity investment could justify a structural upward shift in fair-value multiples—the same argument used to defend above-average multiples in the mid-1990s before the tech boom validated them.
The critical variable is whether earnings growth materializes at or above the 7% consensus. If it does, elevated valuations can persist indefinitely—as they did from 1995 to 2000. If it disappoints by even 3-4 percentage points, the valuation math deteriorates rapidly.
Historical Parallels and the Lesson of 1995
The year the equal-weight index last underperformed this badly at the start of a year was 1995—a year that, perversely, turned out to be the beginning of the greatest bull market in American history. The Nasdaq proceeded to gain 400% over the following five years.
This parallel is simultaneously comforting and terrifying, because it demonstrates that breadth warnings and valuation extremes can persist—and even intensify—for years before resolving. The investors who exited in 1995 citing CAPE overvaluation missed the most explosive equity appreciation in modern history. The investors who stayed fully invested in 2000, citing the same logic, lost nearly half their wealth over the subsequent two years.
The honest conclusion for 2026 is that Goldman’s equal-weight warning is a signal to reduce risk at the margin, not abandon equities wholesale. Trim concentration, add insurance, raise cash selectively, and prepare for higher volatility—without assuming a crash is imminent or inevitable.
For investors building out the full macro picture, TheMarketCapitalist.com’s deep dive on Japan’s impending debt crisis explains precisely why external shocks are more dangerous at CAPE 40 than at median valuations, while our oil investing guide details why energy remains one of the few sectors trading at genuinely undemanding multiples in an otherwise stretched market. Our financial options guide provides the exact hedging tools—protective puts, collars, and spreads—that translate this breadth warning into executable portfolio protection.
In the end, the equal-weight S&P 500’s worst start in 30 years is not a prediction—it is a measurement. It measures exactly how few companies are carrying the weight of American equities in early 2026. What investors do with that measurement—ignore it, act on it, or incorporate it into a calibrated risk reduction—will determine whether this cycle ends like 1995 or like 2000.
Disclaimer: The information in this article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com assumes no responsibility for losses resulting from use of this information.
(Word count: 2,641)


