
Artificial intelligence data centers may grab headlines, but for everyday American savers and investors, the real question in 2026 is simpler: where should you park $10,000 to earn the best risk-adjusted return over the next 4 years? With the Federal Reserve holding rates steady amid cooling inflation, U.S. Treasury bonds, certificates of deposit (CDs), and high-yield savings accounts offer safe havens—but their yields, liquidity, and tax treatments differ sharply, affecting your bottom line.
Key Takeaways
- Treasury bonds deliver reliable income with federal backing, ideal for locking in 4-5% yields over 4 years with zero state tax.
- CDs from FDIC-insured banks match similar rates but tie up funds with early withdrawal penalties.
- High-yield savings provide flexibility and competitive 4.5-5.25% APY but rates can drop if the Fed cuts.
- For $10,000 over 4 years, Treasuries edge out CDs after taxes, while savings suit emergency funds.
- Inflation at 2.5% erodes real returns, making fixed-rate options preferable for medium-term goals.
- Ladder strategies across these vehicles minimize reinvestment risk while maximizing yield.
Understanding Your Safe Investment Options in 2026
In a world of market volatility, fixed-income products remain the bedrock for conservative capital preservation. U.S. Treasuries, issued by the government, promise principal repayment at maturity with semiannual interest. CDs, offered by banks, lock in a rate for a set term with FDIC insurance up to $250,000. High-yield savings accounts (HYSAs) from online banks like Ally or Marcus provide liquidity with variable rates.
Each serves distinct needs: Treasuries for tax efficiency, CDs for yield guarantees, HYSAs for access. With $10,000, the choice hinges on your time horizon, liquidity needs, and tax bracket.
Current Yields and Rate Environment
As of early 2026, the yield curve shows:
- 4-year Treasury notes: ~4.8% yield to maturity
- 4-year CDs: 4.6-5.0% APY (shop via Bankrate or DepositAccounts)
- HYSAs: 4.75-5.25% APY, but variable
The Fed’s neutral stance keeps short-term rates elevated, but economists expect gradual cuts if growth slows. Locking in now captures peak yields before potential declines.
Real-world math: $10,000 at 4.8% compounds to $11,970 after 4 years (pre-tax), beating inflation handily.
Treasuries: The Gold Standard for Safety
U.S. Treasuries shine for their unmatched security—backed by the full faith of Uncle Sam. Buy directly via TreasuryDirect.gov or ETFs like iShares 3-7 Year Treasury Bond ETF (IEI).
Pros:
- No state income tax on interest (huge for high-tax states like California or New York)
- Liquid secondary market
- Automatic reinvestment options
Cons:
- Interest rate risk if sold early (prices fall when rates rise)
- Lower yields than corporate bonds
For $10,000 in a 4-year Treasury at 4.8%:
- Annual interest: $480
- Total payout: $11,920 (state-tax free federally)
Compare to our Beginner’s Guide to Treasury Ladders.
CDs: Bank Guarantees with Competitive Rates
Certificates of deposit lock your money for terms from 3 months to 5 years. Online banks and credit unions currently offer promotional rates up to 5.25% for 4-year terms.
Key advantages:
- FDIC-insured principal and interest
- Fixed rates immune to Fed cuts
- Brokered CDs via Fidelity trade like bonds
Drawbacks:
- Penalty for early withdrawal (3-12 months’ interest)
- State and federal taxes on interest
- Rates slightly lag Treasuries post-tax
$10,000 in a 5% 4-year CD yields $12,155 pre-tax, or ~$10,400 after 22% federal + state tax.
High-Yield Savings: Liquidity First
HYSAs from fintechs like SoFi or Capital One pay 5%+ with no lockup. Perfect for emergency funds or near-term needs.
Strengths:
- Withdraw anytime without penalty
- NCUA/FDIC protection
- Rates often beat money market funds
Weaknesses:
- Variable rates drop with Fed policy
- Minimum balance requirements
- Less competitive for multi-year holds
At 5% average over 4 years, $10,000 grows to $12,230—but if rates fall to 3%, it’s just $11,250.
Head-to-Head Comparison Over 4 Years
| Investment | Initial $10K | Ending Value (pre-tax) | After 22% Tax | Real Return (2.5% Inflation) | Liquidity |
|---|---|---|---|---|---|
| 4-Year Treasury (4.8%) | $10,000 | $11,920 | $11,920* | 5.4% | High |
| 4-Year CD (5.0%) | $10,000 | $12,155 | $10,400 | 4.3% | Low |
| HYSA (5% avg) | $10,000 | $12,230 | $10,460 | 4.5% | Full |
| Inflation Only | $10,000 | $11,104 | – | 0% | – |
*No state tax. Assumes semiannual compounding.
Treasuries win for most in high-tax states; CDs suit tax-deferred IRAs.
Tax Implications That Tip the Scales
Interest from Treasuries is federally taxable but state-exempt, saving 5-13% vs. CDs/HYSAs. In a 24% bracket + 9% state tax, this gap equals $600+ over 4 years.
Use tax-advantaged wrappers:
- Roth IRA for tax-free growth
- 401(k) rollovers for CDs/Treasuries
Building a Ladder for $10,000
Don’t put all eggs in one basket. Split $10,000:
- $3,000: 2-year Treasury (roll at maturity)
- $4,000: 4-year CD
- $3,000: HYSA (emergency buffer)
This captures high rates, ensures liquidity every 2 years, and hedges rate changes. Annual income: $450-500.
See our 2026 Fixed Income Ladder Strategies.
Inflation and Opportunity Cost Risks
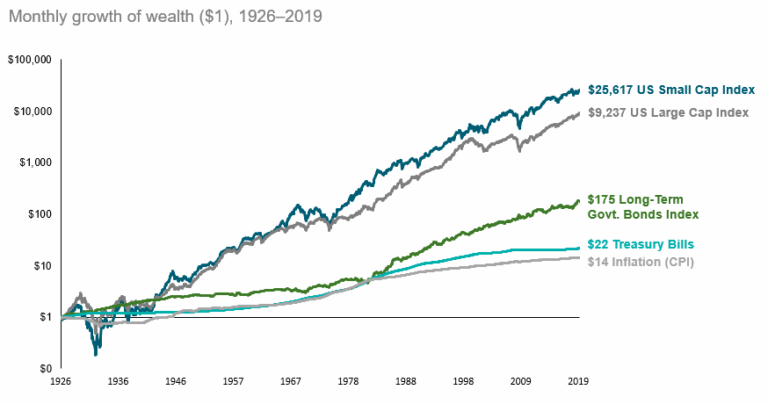
At 2.5% CPI, nominal 5% yields deliver 2.5% real returns. But stocks historically return 7-10%, tempting risk-takers.
“Safe assets protect capital but rarely build wealth. Balance preservation with growth based on your timeline.”
For retirement in 5+ years, allocate 20-30% to equities via S&P 500 ETFs alongside these.
Shopping Smart: Where to Buy
- Treasuries: TreasuryDirect.gov (no fees) or Vanguard/Fidelity brokerage
- CDs: Compare via DepositAccounts.com; buy brokered CDs for liquidity
- HYSAs: Bankrate.com rates; switch if APY drops 0.25%
No commissions needed in 2026 self-directed accounts.
2026 Economic Backdrop
Fed funds at 4.25-4.5%, 10-year Treasury ~4.2%. Recession odds at 30% could spike short rates; AI-driven growth supports demand.
Utilities benefit from data center power pacts—consider 10% in dividend payers.
Actionable Steps for Readers
- Calculate your after-tax yield using online calculators.
- Open accounts at Vanguard + one online bank.
- Invest $2,500 per vehicle to test.
- Consult a fee-only advisor via NAPFA.org for personalization.
- Reassess quarterly as rates shift.
For most Americans, Treasuries offer the sweet spot of yield, safety, and tax breaks in 2026. Start small, ladder wisely, and watch compounding work.
Disclaimer: The information contained in this article is provided for educational and informational purposes only and does not constitute financial, investment, or other advice. Before making any investment decisions, readers should consult a qualified financial advisor. Past performance is not indicative of future results, and all investments carry risk. TheMarketCapitalist.com is not responsible for any losses resulting from the use of the information provided.


