
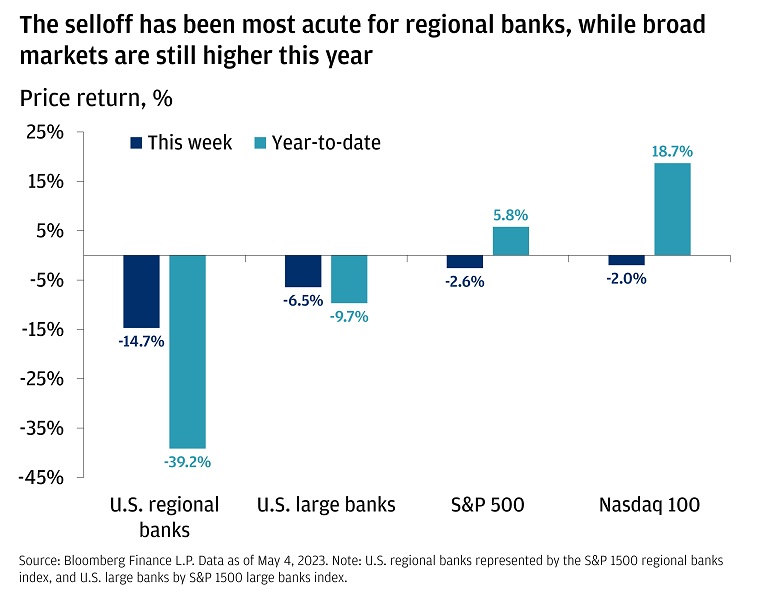
Regional banks in the United States are once again under pressure. After the turmoil of early 2023, many believed the worst was over. Instead, 2025 has brought renewed stress: falling stock prices, deposit outflows, tightening credit conditions, and rising concerns about commercial real estate exposure.
For investors, this is not just a banking story — it’s a macro story. Regional banks are the backbone of U.S. small-business lending and commercial property financing. When they weaken, the entire real economy feels the shock.
Key Insights
- Several mid-size and regional banks have seen renewed drops in market capitalization due to liquidity stress and weakening loan portfolios.
- Commercial real estate — especially office properties — remains the single largest vulnerability.
- High interest rates continue to suppress loan demand and tighten margins.
- Regulators are stepping up oversight and stress-testing requirements.
- Investors should brace for consolidation, credit restrictions, and potential spillovers into labor markets and real estate.
Why Regional Banks Are Falling Again
Declining deposits
Even though panic-driven withdrawals have slowed compared to 2023, deposits continue to drift toward larger banks and money-market funds. Higher yields elsewhere are pulling liquidity away from regional lenders, leaving them with a more expensive funding base.
Pressure on net interest margins
Regional banks depend on the spread between what they pay for deposits and what they earn on loans. With policy rates remaining elevated and depositors demanding higher payouts, margins have tightened to their weakest levels in years.
Commercial real estate exposure
This is the elephant in the room.
Regional banks hold a disproportionately high share of loans tied to:
- office buildings,
- retail centers,
- multi-family housing,
- small-business facilities.
Office vacancies remain historically high. Refinancing waves at higher rates are pushing many borrowers toward distress. As loan books deteriorate, markets are pricing in further write-downs.
Bond losses and balance-sheet fragility
Many regional banks still carry large portfolios of long-dated bonds purchased when rates were near zero. These assets remain underwater. Unrealized losses weigh on capital ratios and limit the ability to lend.
What’s Different From 2023
The current situation lacks the immediate panic of the Silicon Valley Bank failure. Instead, the stress today is slower and more structural:
- profitability is eroding,
- capital is tightening,
- loan demand is weakening,
- refinancing pressures are rising.
This kind of slow-motion deterioration can be just as dangerous for unprepared institutions.
How This Affects the Broader U.S. Economy
Credit tightening
Regional banks are the primary lenders to small businesses. When they pull back, the consequences cascade into:
- lower hiring,
- reduced investment,
- slower wage growth,
- more cautious consumer spending.
Real estate markets
Distressed commercial properties can spill into local economies. Falling valuations hurt municipal revenues and weigh on construction activity.
Potential contagion
If one or more mid-size lenders fail, confidence could deteriorate quickly across the sector. Even without panic withdrawals, funding costs could spike further.
What Investors Should Expect in 2025
More bank mergers
Consolidation becomes a way to shore up capital and diversify risk. Stronger banks will acquire weaker ones at discounted valuations.
Stricter regulation
Expect more capital requirements, tougher liquidity standards, and closer supervision. Compliance costs will rise for many institutions.
Higher loan defaults
Commercial real estate and consumer credit — especially credit cards — are showing early signs of strain. Defaults will likely continue rising through 2025.
Lower earnings
Regional banks will struggle to grow profits unless interest rates fall meaningfully. Any temporary relief will depend on monetary policy shifts.
Opportunities and Risks for Investors
Where risks are highest
- Small and mid-size banks with concentrated commercial-property exposure
- Institutions dependent on uninsured deposits
- Lenders with large unrealized bond losses
- Banks operating in cities with high office-vacancy rates
Where opportunities may emerge
- Select stronger regionals benefiting from consolidation
- Banks with diversified loan books and stable core deposits
- Financial institutions expanding into wealth management or fee-based services
- Companies providing restructuring, advisory, and asset-management services
How Investors Can Protect Themselves
- Review balance sheets carefully. Focus on capital ratios, deposit stability, and exposure to commercial real estate.
- Avoid institutions with high unrealized losses and heavy reliance on volatile funding sources.
- Diversify financial exposure. Don’t over-concentrate in smaller banks during a stress cycle.
- Monitor labor and credit conditions. Banking stress will show up in these indicators before it shows up in official earnings.
- Take a long-term perspective. While current volatility is high, crises often create opportunities for disciplined investors.
Conclusion
The renewed decline in U.S. regional banks is a warning sign. While not yet a systemic crisis, the pressures — commercial real estate, high funding costs, and lower profitability — are real and persistent. Investors must be selective, cautious, and data-driven.
The coming year will likely bring further consolidation, rising defaults, and a tighter credit environment. Those who understand where the vulnerabilities lie — and where resilience is emerging — will be best positioned to navigate this cycle successfully.
Disclaimer: The information in this article is for educational and informational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results, and all investments carry risk.


